



Intelligent Power Modules Market: Beyond the 7.1% CAGR to 6.15B by 2032

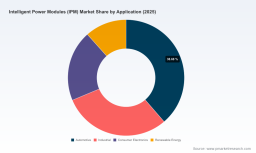
Intelligent Power Modules Market: Strategic Trends and Commercial Opportunities
The Intelligent Power Module (IPM) market is undergoing a structural transformation, driven by the convergence of electrification, efficiency mandates, and semiconductor integration. Over the past five years, the segment has grown from approximately $2.7 billion in 2020 to an estimated $3.8 billion in 2025, reflecting a compound annual growth rate of 7.1% through 2032. By the end of the forecast period, revenue is projected to approach $6.15 billion, signaling a market that is steadily outgrowing legacy power electronics cycles. This trajectory is not merely a function of volume expansion; it reflects a deeper shift in how power conversion systems are designed, manufactured, and deployed across automotive, industrial, consumer, and renewable energy applications.
Market concentration remains moderate, with the top three players capturing roughly 55% of revenue and the top five accounting for about 60%. This concentration indicates a landscape where established incumbents hold meaningful share, yet sufficient fragmentation and regional variation leave room for targeted entrants and technology specialists. The Asia-Pacific region continues to anchor demand, while North America and Europe sustain steady growth through industrial automation, automotive electrification, and grid modernization programs. Understanding where value is created, where supply constraints emerge, and how incumbents are differentiating is essential for executives navigating procurement, product roadmap, and capital allocation decisions.
Market Overview and Core Challenges
The IPM market's expansion is anchored by a clear technological migration: discrete power devices and standalone drivers are increasingly being consolidated into integrated modules that combine IGBTs, MOSFETs, or wide-bandgap devices with gate drivers, protection circuits, and thermal management features. This integration reduces board space, simplifies design, improves reliability, and shortens time-to-market for end systems. The payoff is visible in the revenue trend, where steady year-over-year growth has accelerated as automotive electrification and industrial motor control adoptions reach scale. Yet the path forward is not without friction.
Three challenges define the current inflection point:
-
Wide-bandgap supply tension. SiC and GaN substrates have become strategic bottlenecks. In 2025, SiC wafer availability constraints pushed lead times for 1200V dies to as long as 26 weeks, causing some OEMs to delay platform launches by up to six months. Similar substrate pressures extended IPM component lead times beyond 16 weeks across multiple end markets, complicating EV and grid equipment schedules.
-
Geopolitical and materials risk. Export controls on gallium and related critical minerals introduced new uncertainty for GaN and SiC substrate supply chains. Combined with broader trade restrictions on semiconductor materials, logistics and customs variability have added risk to module procurement and production planning.
-
Cost and integration trade-offs. As module content grows more sophisticated, balancing die count, packaging footprint, and unit cost becomes a tighter optimization problem. Competitive pressure is intensifying around compact packages, high-voltage SiC integration, and price points that appeal to high-volume appliance and industrial motor applications.
For decision-makers, these challenges are not merely operational nuisances; they shape product timing, bill-of-materials stability, and the feasibility of design wins. A module that looks compelling on paper can become a schedule risk if substrate availability or packaging capacity is constrained. Conversely, early alignment with suppliers that have secured substrate access or alternative packaging paths can translate into a durable competitive advantage.
Key Drivers Shaping the Market
The IPM market's momentum is the result of several reinforcing forces. Technology innovation, regulatory pressure, demand-side behavior shifts, and supply chain evolution are interacting in ways that reward integrated architectures and penalize fragmented designs.
Technological Innovation and Integration
Integration is the central narrative. Modern IPMs combine power switches, drivers, and protection functions into a single package, enabling designers to shrink solution size while improving thermal performance and reliability. IGBT-based modules remain the volume backbone for many industrial and automotive motor control applications, but the rise of SiC and GaN-based IPMs is expanding the performance envelope in high-efficiency inverters, HVAC compressors, data-center drives, and e-mobility propulsion. The emphasis is increasingly on die-level optimization, package miniaturization, and high-voltage capability that reduces system-level cost despite higher device unit prices.
Recent product movements illustrate this direction. In September 2025, Mitsubishi Electric began shipping samples of a new compact DIPIPM series that uses RC-IGBTs to achieve a 53% smaller footprint for packaged air conditioners and heat pumps. The move highlights how packaging innovation can unlock design wins in space-constrained HVAC applications without sacrificing performance. Around the same time, ON Semiconductor introduced its EliteSiC SPM 31 series, a 1200V SiC MOSFET-based IPM aimed at reducing system costs for HVAC and data-center drives. This launch underscores a broader trend: SiC adoption is increasingly justified not just by efficiency gains, but by total system cost reductions when module integration lowers passive counts, simplifies thermal design, and improves power density.
Regulatory and Policy Environment
Policy and regulatory pressure continue to push end-use applications toward higher efficiency and lower emissions. Motor drive efficiency standards, building electrification incentives, and emissions regulations in automotive and industrial sectors all reward more compact, more efficient power conversion. In parallel, export controls and materials-related restrictions have added a strategic dimension to procurement. The May 2025 Chinese export controls on gallium and related critical minerals have heightened attention on GaN and SiC substrate dependencies, prompting OEMs and module suppliers to diversify sourcing, secure long-term agreements, and evaluate alternative material paths where feasible. The regulatory backdrop is therefore not only a compliance story; it is becoming a supply strategy story.
Demand-Side Shifts
Demand is being reshaped by three macro behavior changes. First, electrification in mobility and industrial equipment is expanding the addressable base for integrated power modules, especially where traction, auxiliary power, and motor drives require compact, reliable solutions. Second, energy efficiency mandates and operating cost pressures are accelerating adoption in HVAC, heat pumps, renewable energy inverters, and industrial automation. Third, consumer and commercial product designs increasingly favor smaller form factors and faster development cycles, which favors modules that reduce component count and simplify certification. These shifts increase the premium on modules that can deliver high integration, predictable availability, and scalable pricing.
Supply Chain and Cost Structure Dynamics
Cost structures are evolving as integration increases. On one hand, combining functions into a module can lower total system cost by reducing external components and simplifying assembly. On the other hand, substrate availability, wafer lead times, and high-voltage SiC pricing can compress margins or delay programs. Supply chain volatility in Si wafers and AlN substrates has extended module lead times beyond 16 weeks in multiple instances, reinforcing the importance of multi-source strategies and forward visibility. For high-volume applications, pricing and lead-time stability are becoming as important as performance specifications, and suppliers that can balance integration with reliable delivery are gaining leverage.
Competitive Landscape and Leading Strategies
The IPM market is contested by a mix of broad-line semiconductor majors, power-specialist incumbents, and technology-focused niche players. The competitive posture varies by application focus, device technology, and packaging capability. What separates leaders is not simply product breadth, but the ability to align technology choices with end-market needs, secure substrate and packaging capacity, and deliver solutions that reduce system-level complexity.
Incumbents and Their Strategic Positioning
STMicroelectronics continues to emphasize integrated power modules with IGBT and MOSFET drivers and protection features, particularly for industrial and automotive motor control. Its positioning centers on design simplification and application-specific integration that helps reduce development risk for motor drive and control applications. Infineon's CIPOS portfolio extends this logic to high-integration IPMs for motor drives, EV traction, and renewable energy systems, reinforcing a strategy built on application coverage and system-level value. Renesas focuses on embedded control IPMs with integrated drivers for industrial and automotive uses, aligning module offerings with microcontroller-centered design architectures. Fuji Electric has pushed higher-generation IGBT IPMs aimed at high-efficiency production equipment and energy-saving inverters, targeting industrial customers who value efficiency gains and proven reliability.
On the wide-bandgap side, ROHM and ON Semiconductor are advancing SiC and GaN IPMs for compact, high-efficiency inverters and motor drives. ON's EliteSiC SPM series and ROHM's GaN/SiC focus reflect a strategy of competing on efficiency and power density while expanding into HVAC, data-center drives, and e-mobility. Mitsubishi Electric's compact DIPIPM and SiC-based IPMs for packaged air conditioners, heat pumps, and industrial inverters illustrate a parallel strategy: using packaging innovation and device-level optimization to win in high-volume, space-constrained applications. Texas Instruments emphasizes isolated power modules and integrated solutions for data centers, EVs, and industrial systems, positioning around isolation, signal integrity, and system-level robustness. Semikron Danfoss targets high-reliability IPMs for industrial automation, EV, and renewable energy drives, appealing to applications where durability and long service life are paramount.
Smaller or more specialized players are carving out niches. Toshiba's SiC and IGBT IPMs address high-voltage industrial and automotive drives, Alpha and Omega Semiconductor has moved aggressively on compact BLDC motor drive IPMs with its Mega IPM-7 and IPM5 series, and Wolfspeed's SiC-based IPMs target e-mobility propulsion and high-efficiency inverters. NXP contributes power management IPMs for industrial and consumer motor control, while Sensitron focuses on radiation-tolerant, high-reliability modules for space and industrial scenarios. This mix shows a market where scale players compete on breadth and integration, while specialists compete on application fit, technology differentiation, or reliability requirements.
Recent Developments as Strategic Signals
Recent product and production events provide a window into how competition is evolving. In April 2025, Alpha and Omega Semiconductor launched the Mega IPM-7 series for brushless DC motor drives, offering 600V devices in a compact 18mm by 7.5mm package with pricing around $1.80 at 1,000-piece quantities and a 16-week lead time. The offering signals a focus on price-competitive, footprint-optimized modules for appliance and industrial motor applications. By April 2026, high-volume production of the IPM5 series, integrating 17 dies, commenced at a Kaynes Semicon OSAT facility in Sanand, Gujarat, indicating a push to scale manufacturing and secure packaging capacity for integrated modules. Mitsubishi Electric's September 2025 sample shipments for the compact DIPIPM series, with a 53% footprint reduction using RC-IGBTs, reinforce the industry's emphasis on miniaturization in HVAC and heat pump applications. ON Semiconductor's March 2025 EliteSiC SPM 31 launch highlights the growing relevance of 1200V SiC IPMs for system cost reduction in HVAC and data-center drives.
These moves are not isolated product launches; they reflect a broader competitive logic. Suppliers are racing to reduce footprint, increase integration, secure packaging and substrate capacity, and align device technology with the cost and efficiency requirements of high-volume applications. At the same time, the wide-bandgap supply constraints and materials-related risks noted earlier mean that execution discipline, availability, and lead-time management are becoming decisive competitive factors.
How the Landscape Is Evolving
The market is showing signs of both consolidation and differentiation. Scale players are expanding integration and application coverage, while device and packaging specialists are targeting specific voltage classes, form factors, or end markets. New entrants and regional manufacturers are finding opportunities where compact packaging, price-competitive pricing, or localized supply offers an edge. At the same time, substrate constraints and materials controls are likely to favor suppliers with diversified sourcing, long-term capacity agreements, and the ability to offer alternative technology paths where appropriate. The result is a landscape in which winning strategies combine technology choice, supply resilience, and application-specific integration rather than relying on device performance alone.
Future Trends to Watch
Looking ahead three to five years, several trends are likely to shape where value accrues and where risk concentrates.
-
Wide-bandgap IPMs move from premium to mainstream in targeted applications. SiC and GaN modules will increasingly be adopted where efficiency, power density, and system cost reduction justify the device premium, especially in HVAC, data-center drives, e-mobility, and renewable energy inverters. Adoption will be uneven, shaped by substrate availability, 1200V-class supply, and total cost-of-ownership calculations rather than device specs alone.
-
Packaging and integration become the primary battleground. As footprint reduction and die integration increase, packaging innovation, thermal performance, and reliability will differentiate suppliers. Compact modules for motor drives, inverter compressions, and high-voltage industrial applications will continue to pressure traditional discre te approaches, rewarding suppliers that can deliver integration without compromising availability.
Worldwide Automotive Power Distribution Modules Market -
Supply resilience overtakes pure cost optimization in procurement strategies. With SiC wafer constraints, advanced substrate shortages, and critical mineral export controls introducing volatility, buyers and manufacturers will place greater weight on multi-source arrangements, forward capacity commitments, and regional supply options. Programs that depend on single-source high-voltage SiC substrates or constrained substrates will face greater schedule risk.
These trends create commercial opportunities for manufacturers that can align product roadmaps with integration and availability, for suppliers that can secure substrate and packaging capacity while offering compelling system-level value, and for investors who can identify players with credible wide-bandgap execution and diversified supply strategies. At the same time, uncertainty remains. Substrate and wafer availability may ease in some periods and tighten in others; trade and materials policies can shift quickly; and pricing pressure in high-volume applications can compress margins even as integration increases. The winners will be those who treat supply strategy and technology choice as a combined problem rather than separate workstreams.
Strategic Actions for Decision-Makers
Different roles face different priorities, but a few guiding actions apply across the board.
Intelligent Power Module Board Market
For Manufacturers and Product Leaders
-
Match device technology to application economics. Use IGBT-based IPMs where volume and cost sensitivity dominate, and reserve SiC or GaN IPMs for applications where efficiency, power density, or system cost reduction clearly justify the premium. Avoid over-specified solutions that add cost without measurable system benefit.
-
Design for supply resilience. Evaluate multi-source options for critical substrates and high-voltage dies, and factor lead-time variability into program timelines. Where possible, qualify alternative packages or technology paths to reduce exposure to single-point constraints.
PW Consulting -
Prioritize integration that reduces system complexity. Select modules that lower passive count, simplify thermal design, and accelerate certification. The value of an IPM increasingly lies in total solution simplification, not just switch performance.
For Investors and Strategy Teams
-
Assess execution on wide-bandgap supply, not just product announcements. Track substrate access, packaging capacity, and lead-time management as leading indicators of which suppliers can convert technology Roadmaps into revenue.
-
Look for application concentration and differentiation. Companies with strong positions in HVAC, data-center drives, e-mobility, or industrial motor control may command more durable demand than those dependent on a single end market with cyclical exposure.
-
Watch for consolidation and scaling signals. Manufacturing scale-up events, OSAT partnerships, and footprint-reduction launches can indicate which players are building the capacity and cost structure needed to compete in high-volume segments.
For Procurement and Supply Chain Leaders
-
Move from transactional purchasing to strategic alignment. Secure visibility into lead times, substrate constraints, and capacity commitments, especially for SiC and high-voltage modules. Early engagement with suppliers can reduce the risk of platform delays.
-
Build flexibility into design wins. Where feasible, qualify more than one module option or technology path to avoid lock-in to a constrained substrate or single supplier. This flexibility can be decisive when materials controls or wafer availability shift.
-
Balance cost and availability. In high-volume applications, a modest price premium for more predictable supply can protect program schedules and reduce downstream costs associated with delays or redesigns.
The IPM market is moving from a phase of steady expansion into one where technology choice, integration depth, and supply resilience determine competitive outcomes. For executives and investors, the most valuable insight is that the next wave of differentiation will be less about individual device specifications and more about how well modules reduce system complexity, fit into constrained form factors, and remain available amid materials and geopolitical uncertainty. Detailed segmentation data, supplier-level capacity assessments, and application-specific cost modeling can sharpen these decisions further, and comprehensive research reports provide the structured detail needed to translate these trends into concrete action.
For detailed analysis of this topic, please visit the official page: Intelligent Power Modules (IPM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


