



The Real Drivers Behind PEG Market's 6% CAGR Growth Trajectory to 2032

The Polyethylene Glycol Market: Strategic Trends and Commercial Opportunities Through 2032
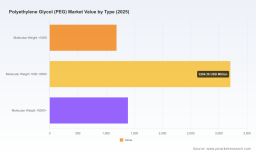
The global landscape for polyethylene glycol (PEG) is undergoing a quiet but significant transformation. Valued at approximately 5,780 million USD in 2025, the market has expanded steadily from a base of roughly 4,400 million USD in 2020, reflecting a compound annual growth rate of about 6.0 percent through 2032. While the headline trajectory suggests steady expansion, the underlying dynamics tell a more nuanced story. Demand composition, regulatory pressure, regional production footprints, and raw material volatility are reshaping where growth will materialize and which players will capture it.
PW Consulting
For executives, strategists, and investors, PEG is no longer a commodity chemical with uniform margins and predictable demand. It is a differentiated specialty input where formulation requirements, compliance standards, and sourcing resilience increasingly determine competitive advantage. The next several years will reward companies that can align technical capabilities with shifting regulatory and demand-side expectations while managing cost exposure across a tightening supply chain.
Market Snapshot and Core Challenges
The PEG market's scale and growth rate mask important structural pressures. Historical revenue patterns from 2020 through 2025 show consistent year-over-year gains, with forward projections indicating continued expansion into the early 2030s. Growth, however, is no longer evenly distributed across applications or regions. Certain end-use segments are absorbing demand faster than others, and regional production centers are repositioning to serve localized compliance and logistics requirements.
Several interconnected challenges define the current inflection point.
Regulatory scrutiny of environmental persistence is reshaping formulation choices. Authorities in key markets have tightened restrictions on polymers that demonstrate persistence in aquatic ecosystems, including certain PEG derivatives. Because PEG is derived from petroleum-based ethylene oxide and is not inherently biodegradable, these regulatory shifts are prompting formulators and producers to reassess product specifications, documentation, and lifecycle profiles. For markets that depend on consumer-facing and pharmaceutical applications, compliance is becoming a gatekeeping function rather than a back-office consideration.
Raw material cost volatility is compressing margins and complicating planning. Ethylene glycol prices in Asia moved largely downward during the second half of 2025 under strong supply pressure, illustrating the kind of input fluctuation that can disrupt cost structures across the value chain. While lower feedstock costs can improve producer margins in the short term, the broader pattern is one of unpredictability. Manufacturers and buyers alike face challenges in forecasting landed costs, negotiating long-term contracts, and maintaining consistent pricing in end products that rely on PEG as a functional ingredient.
Concentration among leading producers creates both resilience and strategic risk. The market remains moderately concentrated, with a small group of major suppliers holding a substantial share of total revenue. This concentration can stabilize supply for large-scale buyers, but it also introduces dependency risk when regulatory changes, capacity constraints, or regional disruptions affect a handful of critical facilities. Companies that rely on narrow sourcing channels are increasingly exposed to price resets and qualification delays, especially when switching to alternative grades requires revalidation.
These challenges are not abstract. They directly affect product roadmaps, procurement strategies, and investment timing. The companies that navigate them best will treat regulatory alignment, cost controllability, and supply diversification as strategic design parameters rather than operational afterthoughts.
Key Drivers Reshaping the Market
Market momentum is being driven by a combination of technical, regulatory, demand-side, and supply chain forces. Understanding how these drivers interact is essential for anticipating where growth will concentrate.
Technical Innovation and Formulation Differentiation
One of the strongest catalysts for change is continued innovation in PEG grades and reactive derivatives. Producers are expanding portfolios that support more precise solubility, viscosity, and reactivity profiles for specialized formulations. For example, the introduction of reactive polyethylene glycol grades for industrial formulators in Europe reflects a broader push toward tailored performance rather than volume-only supply. Such developments matter because they expand the addressable use cases for PEG in complex formulations where standard grades are insufficient.
The strategic implication is clear. Differentiation is increasingly tied to grade specificity, purity profiles, and application support rather than price alone. Manufacturers that can offer documented quality, regulatory readiness, and technical assistance are better positioned to deepen relationships with formulation-intensive buyers. This shifts competition from a transactional model toward a value-added partnership model, particularly in pharmaceuticals and personal care, where compliance and consistency carry a premium.
Regulatory and Compliance Evolution
Regulatory dynamics are not merely constraints; they are also shaping demand for compliant supply and prompting regional capacity realignment. As authorities increase scrutiny of polymer persistence and environmental impact, buyers in regulated sectors are prioritizing suppliers with robust documentation, GMP-aligned production, and traceable quality systems. This environment elevates the importance of production sites that can demonstrate compliance with recognized pharmaceutical and excipient standards.
A notable example is the expansion of GMP-compliant manufacturing capacity in the United States for pharmaceutical-grade PEG excipients, creating a localized production node designed to serve pharma formulations and extend reach into adjacent markets such as Latin America. Moves like this illustrate how regulatory pressure and customer qualification requirements are driving regional production strategies. For buyers, access to compliant, regionally positioned supply reduces qualification risk and shortens response times. For producers, it strengthens positioning in high-value segments where compliance is a competitive moat.
The practical takeaway is that regulatory shifts are accelerating a structural preference for suppliers with verifiable quality credentials and diversified geographic footprints. Companies that proactively align product lines with evolving expectations will face fewer barriers to adoption and fewer interruptions to qualification cycles.
Demand-Side Shifts in Pharmaceuticals and Personal Care
Demand patterns continue to reflect the centrality of PEG in medical and personal care applications, where it functions as an excipient, solubilizer, and formulation aid. Medical applications remain a major demand anchor, supported by ongoing formulation needs in oral, topical, and other pharmaceutical dosage forms. Personal care demand is similarly sustained by the material's functional versatility in creams, lotions, and other consumer products.
At the same time, demand is becoming more selective. Formulators are increasingly balancing performance objectives with concerns about environmental profile, supply continuity, and regulatory acceptability. This does not necessarily reduce PEG usage, but it does elevate the importance of grade selection and supplier reliability. Buyers are more likely to favor established grades with clear documentation when formulation integrity and regulatory approval are at stake, while also seeking options that support evolving sustainability expectations.
This shift favors suppliers that can communicate application-specific benefits clearly and support customers through changes in formulation architecture. It also creates opportunities for companies that can bridge technical performance with compliance assurance, particularly in markets where personal care and pharma overlap in quality expectations.
Supply Chain Reconfiguration and Cost Structure pressures
The PEG value chain remains tied to ethylene oxide-based production, which links market economics to broader petrochemical dynamics. Feedstock movements, regional capacity additions, and logistics considerations all influence cost structures and availability. The recent downward price pressure on ethylene glycol in Asia is one indicator of how quickly supply conditions can change, but it also highlights the importance of flexible procurement strategies.
Supply chain reconfiguration is being driven by more than cost. Regionalization of production, qualification requirements, and the desire to reduce lead-time variability are encouraging buyers and producers to build more localized or near-localized supply relationships. This is especially relevant where compliance-sensitive applications require close oversight of manufacturing conditions. As a result, the market is gradually moving toward a multi-node supply model in which regional production serves regional demand, supported by specialized grades and documented quality systems.
For decision-makers, the strategic question is not simply where costs are lowest today, but where supply can be secured with acceptable risk over the next several years. Cost optimization still matters, but it is increasingly balanced against resilience, qualification speed, and regulatory alignment.
Competitive Landscape and Leadership Strategies
The PEG market features a mix of global chemical specialists and regional producers, each pursuing distinct strategic positions. Rather than competing solely on volume, leading companies are differentiating through portfolio breadth, compliance readiness, regional capacity, and technical support. This competitive diversity is creating a landscape in which customers encounter both broad-scale suppliers and niche specialists, depending on the application and grade requirements.
Strategic Positioning Among Leading Players
Several companies have established recognizable positions by aligning their offerings with the most demanding segments of the market.
- BASF SE emphasizes specialized ethoxylated polymer-solubilizers and reactive PEGs for oral and topical pharmaceutical formulations, along with USP-compliant grades for excipients. Its portfolio orientation reflects a focus on formulation support and regulatory-grade consistency, particularly in pharma-adjacent applications.
- Dow Inc. maintains a broad PEG series positioned across solvency, lubricity, and formulation use in personal care, pharmaceutical, and industrial applications. Its scale and multi-application coverage make it a reference point for buyers seeking functional versatility across categories.
- Clariant has concentrated on excipient-grade PEG under recognized compliance standards, with recent expansion into North American GMP-compliant production. This move strengthens its ability to serve pharmaceutical customers with regionally accessible, compliance-oriented supply.
- INEOS produces key grades through ethylene oxide polymerization for industrial and personal care applications, reinforcing a position tied to reliable large-scale output and established production pathways.
- Lotte Chemical and Sanyo Chemical Industries both serve industrial, personal care, and pharmaceutical segments, with product ranges that reflect regional strengths and specialty demand. Their presence underscores the importance of Asian manufacturing capability in meeting varied application requirements.
- India Glycols and Chinese producers such as Jiangsu Haian Petrochemical Plant and Liaoning Oxiranchem focus significantly on industrial and personal care markets, often with an emphasis on scale and cost-competitive supply. These players illustrate how regional production hubs serve high-volume application demand while increasingly navigating compliance expectations.
- Croda International contributes PEG excipients and additives for personal care and pharmaceutical uses, aligning with markets where quality documentation and application expertise carry strategic weight.
Differentiation and Competitive Advantages
The most effective differentiators in this market are not abstract. They are concrete capabilities that reduce risk and improve outcomes for buyers. These include:
- Grade specificity and reactive functionality that enable more tailored formulations
- Documented compliance with recognized excipient standards and production controls
- Regional manufacturing footprints that shorten supply routes and support qualification needs
- Application-level technical support that helps formulators integrate PEG into complex systems
- Portfolio breadth that allows customers to consolidate supply without sacrificing performance
Companies that combine several of these capabilities are better positioned to defend margin and deepen customer relationships. By contrast, suppliers competing primarily on price in undifferentiated segments face greater exposure to input volatility and substitution risk.
Polyethylene Oxide (PEO) Market
Landscape Evolution: Consolidation, Fragmentation, and New Entry
The competitive landscape is evolving along multiple axes. In compliance-intensive segments, there is a tendency toward consolidation of preferred suppliers as buyers reduce the number of qualified sources to simplify procurement and quality oversight. At the same time, specialized grades and application-specific solutions create room for fragmentation, with smaller or regional players capturing niche demand that larger incumbents may under-serve.
New entry is most likely where alignment between production capability, compliance readiness, and regional demand is strong. Rather than entering broadly, successful newcomers often establish a defensible position by focusing on a specific grade range, a targeted regional market, or a compliance-critical application. This pattern suggests that the market will continue to reward focused strategies over undifferentiated scale alone.
For buyers, this evolving landscape means that sourcing decisions increasingly involve balancing scale, specialization, compliance assurance, and geographic reliability. For producers, it means that long-term competitiveness depends on being able to demonstrate value beyond volume.
Outlook for the Next Three to Five Years
Looking ahead to the late 2020s and into the early 2030s, several trends are likely to shape PEG market outcomes. These trends are interconnected, and their combined effect will influence both growth distribution and the character of competition.
Trend One: Compliance-Integrated Supply Becomes a Baseline Expectation
As regulatory scrutiny around polymer persistence and environmental impact continues to mature, compliance-integrated supply will move from a differentiator to a baseline requirement in many applications. This does not imply a sudden contraction in demand; rather, it suggests that access to qualified grades and documented production standards will become more central to purchasing decisions. Producers that proactively strengthen compliance documentation, expand GMP-aligned capacity where relevant, and maintain transparent quality communication will face fewer barriers to adoption.
The commercial opportunity here lies in reducing friction for customers. Companies that can shorten qualification cycles, supply regionally appropriate grades, and provide reliable documentation will be better positioned to capture demand in pharmaceutical and personal care segments where approval and consistency are paramount. The risk is that producers with weaker compliance infrastructure may see slower adoption or limited access to higher-value applications, even if their base materials are cost-competitive.
Trend Two: Regionalization of Capacity and Procurement Accelerates
The combination of qualification requirements, logistics considerations, and the desire for supply resilience is likely to accelerate regional capacity strategies. Buyers in multiple markets will continue to favor supply arrangements that reduce lead-time variability and simplify oversight. Producers, in turn, will keep adjusting their footprints to serve regional demand more directly, particularly where regulated or formulation-sensitive applications are concerned.
Strategically, this trend favors companies that can offer localized production or near-localized supply without sacrificing grade consistency. It also creates opportunities for partnerships and capacity investments that align production location with end-market concentration. The uncertainty lies in how quickly regionalization will propagate across all segments. Industrial applications may remain more price-sensitive and globally traded, while pharma and personal care may shift faster toward regional compliance-linked supply.
Trend Three: Value Moves Toward Specialized Grades and Application Support
Growth is expected to increasingly tilt toward specialized grades that deliver specific performance outcomes, rather than toward undifferentiated bulk supply. Reactive PEG derivatives, carefully controlled molecular weight ranges, and grades optimized for particular formulation environments are likely to command greater attention as formulators seek more predictable functionality. Alongside this, application support will become more valuable, as customers look for assistance in integrating materials into complex products while maintaining compliance and consistency.
This trend creates opportunities for suppliers that can pair product specialization with technical credibility. It also opens space for new product launches and targeted portfolio expansions that address unmet formulation needs. The risk is that overinvestment in broad volume capacity without corresponding differentiation may lead to weaker positioning if buyers shift toward grades that provide clearer functional or compliance advantages.
Risk Considerations
Several uncertainties could alter the trajectory outlined above. Continued volatility in ethylene oxide-related feedstocks could disrupt cost planning and squeeze margins for producers with limited hedging flexibility. Regulatory developments could intensify or shift in unexpected ways, altering the compliance burden for certain grades or applications. Substitution pressure may grow in select segments if alternatives can match performance at lower regulatory or environmental cost. Finally, regional capacity expansion may not unfold uniformly, creating temporary imbalances between supply location and demand concentration.
These risks do not negate the growth outlook, but they underscore the importance of scenario planning. Companies that prepare for multiple regulatory, cost, and supply pathways will be better equipped to respond without disrupting product development or procurement continuity.
Strategic Actions for Decision-Makers
The PEG market's evolution offers distinct implications depending on a company's role in the value chain. The following actions are designed to align strategy with the most consequential trends.
For Manufacturers and Producers
- Prioritize grade differentiation and reactive functionality in product development. Expanding specialized offerings can create defensible positioning in formulation-intensive markets where performance and documentation matter more than volume alone.
- Strengthen compliance readiness and quality documentation. Investing in recognized production controls and transparent quality communication reduces barriers to entry in pharmaceutical and personal care applications, where qualification is a critical gate.
- Evaluate regional capacity opportunities against demand concentration and regulatory context. Targeted production investments can improve supply reliability and customer proximity, especially where buyers are increasingly favoring localized or near-localized supply.
- Balance cost leadership with resilience. In a market exposed to feedstock volatility and qualification-related switching costs, margin strategies should account for both price competitiveness and the value of dependable, compliant supply.
For Investors
- Focus on companies with clear alignment between portfolio, compliance capability, and end-market demand. The most durable value creation is likely to come from suppliers that can operate credibly in regulated segments while maintaining flexible production and technical support.
- Assess exposure to feedstock volatility and regional capacity shifts. Investment theses should incorporate how companies manage input cost variability and whether their supply footprints are aligned with emerging regional demand patterns.
- Watch for targeted capacity expansions and portfolio launches that signal positioning in higher-value segments. Moves into GMP-aligned production or reactive specialty grades can indicate where competitive advantage is being built, but they should be evaluated alongside customer qualification pathways and regional demand durability.
For Procurement and Sourcing Leaders
- Diversify qualified sources with an eye toward compliance and geographic reliability, not just unit cost. Reducing dependency on a narrow supplier base can mitigate disruption risk while improving responsiveness to regulatory and formulation changes.
- Engage suppliers early on grade selection and documentation requirements. Proactive alignment on specifications, quality systems, and regional availability can shorten qualification timelines and reduce reformulation risk.
- Build procurement scenarios that account for volatility in feedstock-linked costs. Flexible contracting, multi-grade options, and regional sourcing alternatives can help stabilize supply while preserving cost discipline.
The strategic significance of these actions lies in their ability to connect market dynamics with operational decisions. PEG is not simply a material purchase or a production output; it is a functional input whose value increasingly depends on grade suitability, compliance assurance, and supply reliability. Organizations that treat these attributes as strategic variables will be better positioned to capture growth and manage risk as the market matures.
Polypropylene Glycol Market
For a more detailed view of segmentation dynamics, regional supply patterns, and company-level positioning, the full research report provides additional depth and customized guidance. Readers seeking to translate these trends into specific procurement plans, investment theses, or product strategy decisions may benefit from the granular data and scenario breakdowns available in the complete analysis.
For detailed analysis of this topic, please visit the official page: Polyethylene Glycol (PEG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


