



Sterile Medical Packaging Market: Why 7.65% CAGR Reshapes Strategy Through 2032

Strategic Shifts in the Sterile Medical Packaging Market: Navigating Growth, Regulation, and Material Evolution
The sterile medical packaging market is approaching a defining period of structural transformation. Valued at approximately $501 million in 2025, the sector is projected to expand to $834 million by 2032, reflecting a compound annual growth rate of 7.65 percent. This trajectory is not merely a function of volume growth; it signals a deeper recalibration of how healthcare products are protected, delivered, and compliant with evolving regulatory and environmental mandates. Over the historical window from 2020 through 2025, the market demonstrated steady resilience, with revenue climbing from $350 million to its current level despite periodic supply chain volatility and shifting procurement patterns. The forward-looking period from 2026 to 2032 will test players' ability to align technological capability, regulatory readiness, and sustainable material strategies.
For executives, strategists, and investors, the implication is clear: sterile packaging is no longer a commoditized containment layer. It has become a critical enabler of product integrity, regulatory compliance, and brand positioning. The industry's expansion is unevenly distributed across material types, applications, and regions, but the underlying forces shaping these segments share common denominators. Understanding those drivers—and the competitive responses they are triggering—provides a roadmap for capital allocation, product development, and supply chain decisions.
Market Snapshot and Core Challenges
The market's baseline reflects a mature yet still expanding ecosystem. Revenue growth from 2020 to 2025 moved from $350 million to $501 million, a path marked by incremental acceleration rather than explosive jumps. The forecast period anticipates continued upward movement, with figures progressing from $550 million in 2026 to $834 million in 2032. The 7.65 percent CAGR sits in a range that suggests durable demand anchored in healthcare volume growth, but also indicates that market share dynamics will increasingly reward players who can navigate regulatory complexity, material constraints, and differentiation pressures. Market concentration remains modest, with the top three firms accounting for roughly 24.6 percent of revenue and the top five representing 28.3 percent. This fragmentation leaves room for both consolidation and targeted disruption.
Several structural challenges are reshaping how companies approach product design, sourcing, and go-to-market strategy. First, the regulatory environment is tightening across multiple jurisdictions simultaneously, raising the compliance floor and increasing the cost of market entry. Second, material cost pressures are compressing margins in categories that rely heavily on conventional resins and films, pushing manufacturers to reconsider substrate choices and lightweighting strategies. Third, the sustainability agenda is moving from aspirational messaging to enforceable requirements, with recyclability mandates, recycled content thresholds, and extended producer responsibility frameworks altering the economics of packaging design. Each of these forces interacts with the others, creating a landscape where technical performance, compliance, and environmental profile must be balanced rather than treated as separate workstreams.
Key Drivers Shaping Market Direction
Technological Innovation and Material Breakthroughs
Advancements in barrier performance, lightweighting, and form-factor flexibility are redefining what sterile packaging can achieve. Thermoformed trays with improved barrier properties are reducing weight while maintaining sterility assurance, an approach that directly addresses both material cost and transportation efficiency. Flexible pouch architectures, header bags, and lid systems continue to gain relevance for medical device and pharmaceutical applications where space, handling, and aseptic presentation matter. At the same time, glass and plastic primary packaging options are being refined to meet stringent cleanliness and compatibility requirements for injectable and implantable products. Innovation is increasingly oriented around dual objectives: preserve sterility and usability while reducing material intensity and improving end-of-life pathways.
Recent product introductions illustrate this direction. Lightweight thermoformed tray designs with enhanced barrier characteristics have been launched to serve sterile medical device applications, signaling a shift toward higher performance per unit of material. In parallel, sustainable glass packaging solutions for medical and nutraceutical use have been showcased at industry platforms, highlighting the role of glass as a reusable and recyclable substrate in contexts where clarity, protection, and formulation compatibility are paramount. These developments suggest that differentiation will increasingly stem from engineering efficiency and substrate selection rather than from packaging as a static barrier alone.
Regulatory and Policy Environment
Regulatory shifts are among the most consequential drivers of near-term strategy. In the United States, updated recognition of ISO 11607-1 for packaging of terminally sterilized medical devices is moving toward a compliance deadline that requires full adherence by December 2026. This standard influences testing protocols, material qualification, and validation practices across the device packaging lifecycle. Simultaneously, the U.S. Quality Management System Regulation, which aligns with ISO 13485:2016, requires full compliance by February 2026 for sterile medical packaging manufacturers. The convergence of these requirements raises the bar for documentation, process control, and supply chain traceability.
On the other side of the Atlantic, the EU Packaging and Packaging Waste Regulation has entered into force with a mandate that all packaging be recyclable by 2030, while recycled content requirements begin in 2026 and eco-modulated extended producer responsibility fees apply to producers. These provisions change the cost calculus for material choices and incentivize designs that perform well in recycling streams. In the United States, a growing patchwork of state-level packaging EPR programs across several states ties producer fees to recyclability and recycled content, adding a regional compliance layer for firms that serve national or multi-regional markets. Together, these regulatory currents are turning sustainability from a brand narrative into an operating requirement with measurable cost implications.
Demand-Side Evolution
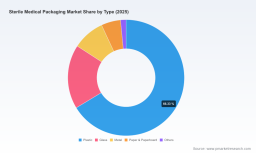
Demand patterns are being reshaped by the broader trajectory of healthcare delivery and product complexity. Pharmaceutical and biological applications remain the largest demand pool, followed by surgical and medical instruments, with in vitro diagnostic products, medical implants, and other categories contributing additional volume. The common thread across these segments is a rising expectation that packaging must support aseptic handling, reduce contamination risk, and integrate smoothly with automated processing and sterilization workflows. As care settings expand beyond traditional hospital environments and device miniaturization continues, packaging is expected to be lighter, more adaptable, and more compatible with varied sterilization modalities.
Procurement behavior is also changing. Buyers are increasingly attentive to supply reliability, regulatory documentation, and environmental performance in addition to unit cost. This creates an opening for suppliers that can present validated, compliant, and materially efficient solutions with clear end-of-life profiles. It also places pressure on manufacturers to demonstrate consistent quality across batches and geographies, particularly where materials and components cross borders. The result is a demand environment that rewards transparency, technical support, and demonstrated compliance as much as it rewards price competitiveness.
Aseptic Packaging Market
Supply Chain and Cost Structure Dynamics
Cost structures are under pressure from multiple directions. Resin and film inputs remain a central variable for plastic-based sterile packaging, with producer price indices for plastics packaging film and sheet manufacturing indicating continued cost intensity. Volatility in feedstock pricing, energy costs, and logistics can quickly alter margin assumptions, especially for high-volume flexible and thermoformed products. At the same time, tighter regulatory requirements increase the cost of validation, testing, and documentation, while recycled content mandates can reshape the available supply of qualified substrates.
PW Consulting
These dynamics are prompting companies to revisit material mix, product geometry, and sourcing strategies. Lightweighting, consolidation of SKUs, and improved yield in conversion processes are becoming levers for margin protection. Suppliers that can offer stable input pipelines, qualified alternative materials, and efficient conversion technologies are gaining negotiating leverage. The broader lesson is that cost competitiveness in sterile packaging is less about chasing the lowest input price and more about engineering resilience into material selection, process design, and supplier relationships.
Competitive Landscape and Leading Strategies
The competitive field is diverse and moderately fragmented, with players occupying distinct positions based on material expertise, application focus, and regional reach. Several companies illustrate how strategy diverges across the market.
Amcor is positioned around thermoformed trays and flexible sterile medical packaging with an emphasis on responsible healthcare solutions, tying performance to sustainability-oriented positioning. DuPont de Nemours brings recognized material science to sterile pouches, header bags, and lids for medical device packaging, leveraging Tyvek-based substrates as a differentiated barrier platform. West Pharmaceutical Services focuses on injectable pharmaceutical packaging components and delivery systems for sterile applications, aligning packaging with dosage form and administration requirements. Sonoco Products Company draws on paper-based and composite solutions for rigid and flexible sterile medical packaging, offering a route to fiber-inclusive designs. Gerresheimer AG operates in glass and plastic primary packaging for sterile pharmaceuticals and medical devices, a segment where clarity, compatibility, and recyclability carry strategic weight. BillerudKorsnäs AB supplies medical-grade paper and paperboard for sterile packaging applications, reinforcing the role of fiber-based substrates in segments where structural integrity and recyclability can be engineered together. Placon Corporation specializes in thermoformed medical trays and sterile packaging solutions, with an emphasis on device-oriented applications. Nelipak Healthcare Packaging addresses high-volume healthcare applications with flexible and rigid sterile packaging, while Steripack Ltd and Constantia Flexibles round out the landscape with custom sterile solutions and flexible pharmaceutical and medical packaging, respectively.
These positions reveal several strategic themes. One is material expertise as a moat: companies that command recognized substrates, validated conversion processes, and specialized barrier properties can command premium positioning and longer qualification cycles. Another is application alignment: firms that connect packaging form factors to specific device, pharmaceutical, or diagnostic workflows are better equipped to provide value-added engineering support and regulatory documentation. A third is sustainability integration: with regulatory and buyer expectations moving toward recyclability and recycled content, players that can offer compliant, recyclable, and lower-material-intensity designs are building a differentiation edge that goes beyond price.
The market structure suggests room for both consolidation and continued fragmentation. Larger, diversified players may pursue bolt-on acquisitions to broaden material capabilities or geographic coverage, while niche specialists may deepen their focus on high-value applications, custom formats, or regional compliance expertise. New entry is possible where technology, qualification speed, or sustainability credentials offer a clear advantage, but the regulatory and validation burden in sterile packaging tends to favor incumbents with established documentation systems and customer relationships. The net effect is a landscape where growth will be captured by companies that can combine material performance, compliance readiness, and efficient cost structures rather than by scale alone.
Looking Ahead: Three Trends to Watch
Regulatory-Driven Material Redesign
Over the next three to five years, the most consequential trend will be the redesign of sterile packaging around recyclability, recycled content, and regional compliance requirements. As EU mandates tighten and U.S. state-level extended producer responsibility programs expand, packaging architectures that perform well in recycling streams and reduce reliance on hard-to-recycle layers will gain preference. This does not mean a uniform shift to a single substrate; rather, it points to a more segmented material strategy in which plastic, glass, metal, paper and paperboard, and composite options are selected based on application needs and end-of-life feasibility. Companies that build modular design capabilities and maintain a qualified portfolio of substrates will be better positioned to adapt to divergent regional rules without sacrificing sterility or usability. The commercial opportunity lies in offering compliant designs that also reduce total material use and improve handling efficiency, creating value for both the manufacturer and the customer.
Engineering-Efficiency as a Margin Defense
A second trend is the growing importance of engineering efficiency as a safeguard against input cost volatility and compliance-related overhead. Lightweighting, improved barrier performance per unit of material, and optimized thermoformed or flexible formats can lower transport costs, reduce resin consumption, and support sustainability targets simultaneously. Product launches that emphasize enhanced barrier properties in lighter formats point in this direction. The businesses likely to benefit are those that can translate material science into repeatable conversion processes, maintain tight quality control, and provide customers with validated, application-specific designs. For investors, the signal is to look beyond headline volume growth and assess which companies are building durable cost resilience through engineering rather than relying on price pass-through alone.
Compliance Infrastructure as a Competitive Barrier
A third trend is the elevation of compliance infrastructure into a strategic asset. With the updated ISO 11607-1 recognition, the Quality Management System Regulation alignment, and multiple recycling and recycled content mandates, the documentation, validation, and process control requirements are becoming more demanding and more interconnected. Suppliers that can provide clear qualification records, stable quality systems, and transparent traceability will reduce risk for device and pharmaceutical customers navigating their own compliance obligations. Over time, this can translate into longer customer relationships, fewer re-qualification cycles, and stronger positioning in regulated segments. The risk is that firms without robust quality systems may face rising rejection costs, project delays, and erosion of trust, especially where multi-region compliance is required.
Plastic Medical Packaging Market
Actionable Insights for Decision-Makers
For Manufacturers and Suppliers
- Audit material portfolios against upcoming recyclability and recycled content requirements, prioritizing designs that maintain sterility and performance while improving end-of-life outcomes.
- Invest in lightweighting and barrier optimization to reduce material intensity and logistics costs, treating engineering efficiency as a core margin lever rather than a secondary improvement.
- Strengthen quality management and validation documentation to align with updated standards and QMS expectations, reducing re-qualification friction and supporting faster customer onboarding.
- Diversify substrate options and conversion capabilities to buffer against resin and film cost volatility, using flexible or paper-inclusive designs where application requirements permit.
For Investors and Capital Allocators
- Focus on companies that demonstrate a credible combination of material expertise, compliance readiness, and cost-resilient engineering, since these attributes are increasingly decisive in a tightening regulatory environment.
- Evaluate exposure to regional regulatory divergence, especially where EPR frameworks and recycling mandates can alter cost structures and demand preferences across markets.
- Track product launches and trade activity that signal shifts toward sustainable glass solutions, lightweight thermoformed formats, and higher-performance flexible architectures, as these often presage broader portfolio direction.
- Consider the fragmentation of the market as both a risk and an opportunity, weighing consolidation potential against the durability of niche advantages in specialized applications or substrates.
For Procurement and Supply Chain Leaders
- Prioritize suppliers that can provide validated, compliant packaging with clear sustainability attributes, since these reduce downstream qualification burden and align with internal ESG and compliance goals.
- Assess total cost of ownership rather than unit price alone, factoring in lightweighting benefits, logistics efficiency, compliance documentation, and the stability of the supplier's quality system.
- Build visibility into material sourcing and regulatory timelines, particularly where state-level EPR programs and international recyclability mandates may affect availability, cost, and specification changes.
- Request application-specific engineering support and barrier performance data to ensure packaging choices match sterilization modality, handling requirements, and device or pharmaceutical characteristics.
The sterile medical packaging market is moving into a phase where growth will be shaped as much by regulatory alignment, material efficiency, and compliance infrastructure as by volume expansion. The companies and investors that can read these signals clearly, adapt product and sourcing strategies accordingly, and build durable qualification and quality systems will be best positioned to capture the next wave of value creation. For decision-makers seeking deeper segmentation data, region-specific regulatory mapping, and tailored strategic recommendations, a comprehensive market research report can provide the granular detail and scenario analysis needed to translate these high-level trends into precise business actions.
For detailed analysis of this topic, please visit the official page: Sterile Medical Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


