



Disposable Gloves Market 2026: Why 8.7% CAGR and Nitrile Demand Reshape Strategy

Navigating the Disposable Gloves Market: Strategic Trends and Commercial Opportunities Through 2032
The global disposable gloves market has transitioned from a crisis-driven supply story into a structurally expanding category defined by material innovation, regulatory realignment, and persistent capacity dynamics. Valued at approximately $31.7 billion in 2025, the market is projected to reach $56.8 billion by 2032, expanding at a compound annual growth rate of 8.7 percent over the forecast period. This trajectory reflects an industry that has absorbed the shock of pandemic-era demand spikes, recalibrated production footprints, and now operates within a more normalized but still highly competitive environment. For executives, strategists, and investors, the opportunity lies not in chasing volume alone but in understanding where material differentiation, compliance readiness, and regional supply chain positioning create durable advantages.
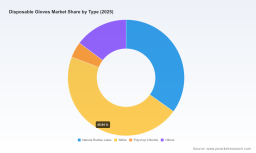
The market's growth is broad-based, yet uneven across segments. Healthcare continues to anchor demand, reflecting sustained emphasis on infection control, clinical procurement standards, and occupational safety. Industrial and food service applications contribute incremental but structurally important volume, particularly as regulatory scrutiny and consumer expectations elevate baseline protection requirements. Material preferences are shifting as well, with nitrile capturing a larger share of procurement decisions due to its balance of chemical resistance, puncture durability, and latex-allergy avoidance. At the same time, the industry remains moderately concentrated, with the top three players accounting for roughly 40 percent of revenue and the top five approaching 55 percent. This concentration suggests that scale, distribution access, and compliance infrastructure still matter, but it also leaves meaningful room for specialized manufacturers and regional suppliers to compete on performance, sustainability, or localized service.
Market Snapshot and Core Challenges
The disposable gloves industry is now navigating a phase where growth is no longer derived from emergency stockpiling but from underlying expansion in healthcare capacity, industrial safety standards, and food handling compliance. Between 2020 and 2025, the market advanced from roughly $20.9 billion to $31.7 billion, a period that included both pandemic-induced demand surges and subsequent normalization. The forecast period through 2032 points to continued expansion, but the character of that expansion is changing. The market is increasingly shaped by capacity additions, material substitution, and the cost implications of compliance and labor across manufacturing regions.
Three challenges stand out as strategic inflection points. First, the industry is operating in an environment of capacity overhang. Global glove production capacity is expected to exceed 500 billion pieces annually within the next two years, while demand is estimated around 400 billion pieces. This imbalance creates pricing pressure, particularly for standardized commodity gloves, and rewards manufacturers that can differentiate through quality, certification, or specialized material performance rather than volume alone. Second, regulatory and trade dynamics continue to reshape sourcing strategies. Modifications to withhold release orders, FDA-aligned facility requirements, and growing scrutiny of labor and compliance practices in export-oriented markets have introduced new layers of risk and cost into global procurement. Third, the cost structure gap between low-labor-cost export hubs and domestic producers remains a persistent tension. Foreign manufacturers can offer disposable gloves at average prices as low as $0.02 per glove, while U.S. producers face significantly higher wages and operational costs. This divergence does not simply create a price differential; it forces buyers and manufacturers alike to weigh total cost of ownership, supply continuity, and compliance assurance rather than unit price in isolation.
For decision-makers, the practical implication is that the market is bifurcating. Commodity-grade volume competes heavily on price and logistics, while differentiated products—whether defined by chemical resistance, accelerator-free formulations, biodegradability, or regional compliance readiness—command more resilient positioning. The challenge is to determine where a given organization can credibly compete and what capabilities are required to sustain that position.
Key Drivers of Market Change
Several forces are converging to shape the next phase of growth. These drivers are not independent; they interact across technology, regulation, demand behavior, and supply economics, creating a market in which advantage increasingly comes from integrating multiple dimensions rather than optimizing a single variable.
Technological Innovation and Material Performance
Material innovation is moving from incremental improvement to functional differentiation. Nitrile remains the dominant material focus, but within that category, manufacturers are introducing formulations that address long-standing pain points such as chemical exposure, dermatological sensitivity, and environmental footprint. Recent product launches illustrate this shift. One major hygiene and protection company introduced a disposable glove line offering up to 15 minutes of resistance to acetone and aggressive chemicals, directly targeting laboratory, industrial, and clinical use cases where chemical compatibility has traditionally required heavier or more expensive protective options. Another initiative launched accelerator-free nitrile gloves designed to reduce chemical exposure risks for healthcare workers, reflecting a growing emphasis on wearer safety beyond basic barrier protection.
These developments matter because they change the value proposition of disposable gloves from simple contamination control to task-specific performance. In procurement terms, they create room for premiumization in segments where failure costs are high, whether in surgical environments, chemical handling, or food processing hygiene. They also raise the bar for competitors, since performance claims increasingly need to be supported by testing, certification, and consistent manufacturing quality.
Medical Disposable Gloves Market
Policy, Regulatory, and Compliance Realignment
Regulatory and compliance dynamics are becoming a strategic variable rather than a background condition. In the United States, the disposable gloves category intersects with FDA-registered facility expectations, medical device regulations, and trade enforcement actions that can alter import availability overnight. The modification of a withhold release order on certain Malaysian glove producers, for example, demonstrated how compliance status can shift market access for specific suppliers while leaving broader sourcing strategies intact. At the same time, domestic producers have emphasized that their FDA-registered facilities employ local workforces with higher labor costs, framing compliance and supply chain predictability as part of the value they provide.
Beyond the United States, traceability and sustainability disclosure are gaining traction. One rubber and materials traceability company expanded its industrial platform to cover global latex and nitrile disposable gloves, advancing transparency in circular materials and supply chains. This type of initiative signals that buyers may increasingly expect visibility into raw material origins, processing practices, and end-of-life attributes, especially in procurement environments where ESG commitments are tied to supplier selection. For manufacturers, compliance and traceability are becoming part of the product offering, not just operational hygiene.
Demand-Side Shifts in Healthcare, Industrial, and Food Service
Demand behavior is evolving on multiple fronts. In healthcare, the pandemic accelerated a structural awareness of PPE adequacy, stockpile discipline, and infection prevention, but the post-crisis reality is more nuanced. Hospitals and care providers are now balancing cost containment with resilience, which favors suppliers that can offer reliable availability, consistent quality, and documentation supporting clinical and regulatory requirements. In industrial settings, safety standards and chemical handling requirements continue to drive demand for gloves that perform beyond basic barrier protection. In food service, hygiene expectations and regulatory oversight maintain a baseline of recurring demand, though price sensitivity is often more pronounced.
A broader demand-side trend is the normalization of procurement decision-making around total value. Buyers are increasingly weighing factors such as chemical resistance, allergy management, comfort and tactility for repetitive tasks, and sustainability attributes alongside unit cost. This does not eliminate price competition, but it expands the criteria by which suppliers can differentiate. For manufacturers, the implication is that product portfolios need to be aligned with real end-use scenarios rather than generic volume positioning.
Supply Chain Economics and Capacity Realignment
Supply chain economics remain central to the market's trajectory. The projection that global capacity will outpace demand in the near term underscores an environment where excess supply can pressure margins, particularly for undifferentiated products. At the same time, regional production strategies are being reconsidered in light of trade policy, logistics risk, and the desire for closer alignment between manufacturing footprint and end markets. Some manufacturers are expanding domestic or near-customer production to reduce exposure to tariff, detention, or compliance uncertainty, while others continue to rely on scale advantages in lower-cost regions.
Cost structures are therefore not just a pricing issue but a strategic design choice. Companies that can manage the tension between scale efficiency and regulatory readiness, or between low unit cost and performance differentiation, are better positioned to protect margins when commodity pressure intensifies. The market is rewarding those who can articulate why their cost structure is appropriate for the segment they serve.
PW Consulting Health Care Research Center
Competitive Landscape and Leading Strategies
The competitive field includes large non-latex producers, established multinational protection companies, regional Malaysian manufacturers with global export reach, and distributors that anchor healthcare procurement. The strategic positioning of these players reveals distinct paths to advantage, and the recent activity across the industry highlights how those paths are being reinforced.
One of the most visible strategic moves is scale leadership in non-latex gloves. A Shandong-based manufacturer reported revenue growth of 4.23 percent to RMB 9.93 billion in its 2025 annual results and expanded annualized production capacity to 103 billion non-latex disposable glove pieces, reinforcing its position as the world's largest non-latex glove manufacturer. This type of scale positioning is valuable because it supports cost efficiency, supply continuity, and the ability to serve large global buyers with consistent volume. However, scale alone is increasingly insufficient if procurement criteria shift toward specialized performance or traceability. The strategic question for scale leaders is how to preserve cost advantages while adding credibility in premium or compliance-sensitive segments.
Disposable Medical Gloves Market
In contrast, some competitors are building advantage through product specialization and certification. A U.S.-based manufacturer operating a large FDA-registered facility supplies powder-free nitrile and biodegradable polyurethane disposable gloves for medical, laboratory, industrial, food handling, and janitorial use. Its positioning emphasizes regulated medical gloves and domestic production infrastructure, which can be appealing to buyers prioritizing compliance assurance, supply predictability, and workforce-related messaging. The contrast with lower-cost import alternatives illustrates how domestic producers attempt to compete on reliability and regulatory readiness rather than pure unit price.
Multinational protection companies are leaning into performance innovation and sustainability recognition. One global leader launched a disposable glove with enhanced chemical resistance and received a business sustainability award for product innovation in the disposable gloves category. This dual focus—functional performance plus external validation of sustainability—reflects a strategy aimed at professional buyers who need demonstrable capabilities and increasingly need to justify procurement choices against environmental and safety criteria. Another major manufacturer exhibited its range of nitrile, latex, and biodegradable disposable gloves at a regional medical trade show, signaling continued emphasis on product breadth and compliance documentation as commercial tools.
Malaysian manufacturers continue to play a central role in the global supply network. Several publicly listed companies maintain broad portfolios across nitrile, latex, and biodegradable gloves, with strong documentation practices and export-oriented operations. Their strategic challenge is navigating the combination of capacity expansion, trade compliance variability, and price competition while preserving quality reputation. The presence of multiple large exporters in the same region also means that buyers have alternatives, which increases the importance of service, specification alignment, and consistent fulfillment.
Distributors and healthcare-focused suppliers add another layer to the landscape. Large U.S. distributors provide medical disposable gloves to healthcare institutions and position themselves as procurement partners rather than pure manufacturers. Their value lies in aggregation, logistics, clinical sourcing expertise, and the ability to coordinate supply across multiple product lines. In a market where availability and documentation can be as important as the glove itself, distribution strength can translate into sticky customer relationships.
Taken together, the landscape is evolving through a mix of consolidation pressure and segmentation opportunity. Scale players compete on volume and cost; specialized manufacturers compete on performance, compliance, or sustainability; distributors compete on service and sourcing integration. New entrants and smaller producers can still find room by targeting specific applications, regions, or material preferences, especially where larger players are less motivated to customize. The broader trend is toward clearer strategic identity: companies that try to be everything to everyone are more exposed to commodity pressure, while those with a defined value proposition are better positioned to defend margin and customer loyalty.
Forward Outlook: Trends Shaping the Next 3–5 Years
Looking ahead, several trends are likely to define the market's direction and create distinct commercial opportunities.
One major trend is the continued shift from generic protection to application-specific glove performance. As buyers in healthcare, industrial, and laboratory settings become more sophisticated about chemical resistance, allergen reduction, and wearer comfort, demand for specialized formulations should remain resilient. This creates opportunity for manufacturers that can validate performance claims, align product lines with real workflow requirements, and communicate value in procurement language rather than generic specification sheets. The risk is that performance claims raise expectations and invite scrutiny, so testing, quality control, and documentation become critical assets.
A second trend is the growing importance of sustainability and traceability as procurement criteria. Even if price remains decisive in many segments, sustainability attributes and supply chain transparency are increasingly used to narrow supplier shortlists or support internal ESG commitments. Companies that can provide credible information about material sourcing, manufacturing practices, and end-of-life options may gain preference in categories where buyers must demonstrate progress to stakeholders. The uncertainty here is the pace and consistency of buyer demand across regions and sectors; sustainability premium willingness is not uniform, and green claims will face increasing scrutiny.
A third trend is the ongoing rebalancing of capacity and trade flows. With global production capacity projected to exceed demand in the near term, the market will likely experience periods of intensified price competition, especially in standardized gloves. At the same time, trade policy adjustments, compliance enforcement, and regional supply preferences may create episodic disruptions that benefit suppliers with flexible footprints or strong documentation readiness. The commercial opportunity lies in anticipating where availability risk or compliance risk will matter most to buyers and positioning supply accordingly. The risk is that overcapacity could compress returns for undifferentiated products and make expansion decisions more hazardous unless they are tied to clear demand signals or differentiated positioning.
Implications for Decision-Makers
The market's evolution suggests different priorities depending on a company's role in the value chain.
For manufacturers, the strategic imperative is to clarify where differentiation is credible and economically sustainable. If the goal is to compete on volume, scale, and cost efficiency must be paired with disciplined capacity planning to avoid sinking into undifferentiated oversupply. If the goal is to compete on performance or compliance, product development, testing infrastructure, certification readiness, and documentation quality become the primary investment areas. Manufacturers should also assess whether their portfolios map clearly to end-use scenarios, because procurement teams increasingly select gloves based on task requirements rather than generic category purchases. In practice, the most resilient strategies often combine one strong axis of advantage with sufficient operational discipline to protect it.
For investors, the opportunity is to distinguish between cyclical volume plays and structurally advantaged positions. Capacity expansion can look attractive in a growing market, but the current overhang suggests that returns will depend heavily on segment selection, pricing power, and cost control. Companies with strong compliance positioning, specialized product lines, or durable distribution relationships may offer more predictable exposure than those reliant on commodity-volume assumptions. Investors should also monitor trade and regulatory developments, since market access can shift quickly for specific suppliers or regions, altering competitive dynamics without changing underlying demand.
For procurement leaders and supply chain decision-makers, the priority is to move beyond unit-cost comparisons and evaluate total cost of ownership under realistic risk scenarios. That includes considering availability resilience, compliance documentation, chemical or allergen requirements, and the potential consequences of supply disruption in critical applications. Diversification across suppliers, materials, or regions can reduce exposure to single-point failures, while specification alignment can reduce waste and improve wearer compliance in practice. The most effective procurement strategies treat glove sourcing as a risk-managed input rather than a purely transactional purchase.
For organizations that need a deeper, more granular view of segment dynamics, regional variations, and company-level positioning, a comprehensive research report can provide the level of detail required to translate these strategic themes into operational decisions. Granular data on material splits, application demand patterns, and competitive moves can help clarify where to commit resources, how to structure sourcing, and which indicators to track as the market continues to evolve.
Closing Perspective
The disposable gloves market is no longer defined solely by emergency demand or commodity volume. It is increasingly shaped by material innovation, compliance consciousness, capacity economics, and procurement sophistication. Growth through 2032 is expected to remain robust, but the rewards will accrue to organizations that can align product capabilities, supply chain resilience, and segment focus with the realities of how buyers evaluate value today. For executives and investors, the key is to treat the market as a competitive landscape with distinct strategic niches rather than a single homogeneous opportunity. Those who do are better positioned to capture durable advantage as the industry matures.
For detailed analysis of this topic, please visit the official page: Disposable Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


