



Binders for Lithium Ion Batteries: Why the 15.8% CAGR Changes Everything

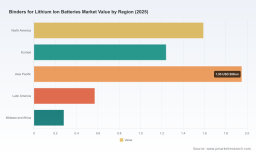
Strategic Trends and Commercial Opportunities in the Lithium Ion Battery Binders Market
The lithium-ion battery binders market has evolved from a supporting materials segment into a critical enabler of next-generation energy storage performance. As electrode architectures grow more demanding and manufacturing processes shift toward sustainability and localization, binder formulations now influence battery cycle life, production economics, and regulatory compliance. Over the historical period from 2020 to 2025, the market expanded steadily, reaching an estimated global revenue of USD 5.63 billion in 2025. Forward projections indicate continued momentum through the 2026-2032 forecast horizon, with the market expected to reach USD 15.72 billion by 2032. This trajectory reflects a compound annual growth rate of 15.8 percent, signaling that demand for specialized binder solutions is accelerating rather than plateauing.
Such expansion is not merely a byproduct of broader battery production growth. It reflects a structural shift in how binders are engineered, sourced, and validated. The market concentration remains relatively fragmented at the top, with the top three participants accounting for approximately 29.4 percent of revenue and the top five reaching 36.2 percent. This distribution suggests room for both specialized challengers and integrated suppliers, while also indicating that scale advantages in formulation consistency and supply reliability are becoming increasingly decisive in securing long-term contracts.
Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market
Structural Challenges and Inflection Points
Despite the favorable growth backdrop, the industry is navigating several interconnected challenges that will shape competitive outcomes over the coming years. Raw material volatility stands out as a persistent pressure point. PVDF binder feedstock pricing has exhibited fluctuations in the 15-25 percent range, directly affecting cathode binder production costs. At the same time, CMC and SBR feedstock inputs, tied to cellulose and styrene pricing, have driven material cost increases of 10-20 percent in 2025. These swings are not isolated margin issues; they force formulators to rethink co-binder ratios, adjust supply strategies, and invest in formulation flexibility to maintain performance without overreliance on any single input stream.
A second inflection point lies in the regulatory and environmental transition away from solvent-based electrode processing. Water-based binder processes are being actively promoted under environmental mandates, with the potential to reduce NMP usage by up to 90 percent in electrode manufacturing. This shift is not simply a compliance exercise. It changes drying profiles, slurry rheology requirements, and equipment specifications, which means binder suppliers must deliver formulations that perform reliably in water-based systems without sacrificing adhesion, conductivity, or cycle stability. Companies that can support manufacturers through this transition are gaining structural relevance beyond traditional product specifications.
Foundry Binder Market
A third challenge is the tightening of qualification standards for automotive and high-reliability applications. New ISO certifications for lithium-ion binder formulations have become required for EV OEM qualification, and 2025 updates mandate enhanced electrolyte compatibility testing. These requirements raise the barrier to entry for new suppliers and reward incumbents with established testing infrastructure, long-term validation data, and close engagement with cell makers during the development cycle. The practical effect is that binder selection is increasingly tied to risk management and certification readiness, not just price or basic performance metrics.
Key Drivers Reshaping the Market
Technology Innovation and Formulation Breakthroughs
The pace of binder innovation is closely tied to changes in anode and cathode design. For graphite-based anodes, SBR and CMC combinations continue to serve as the performance baseline, but the emergence of higher-silicon anodes is pushing formulators toward PAA and advanced co-binder architectures. Silicon-rich designs promise higher capacity, yet they introduce volume expansion challenges that require binders with stronger mechanical resilience and better interfacial stability. On the cathode side, binder selection increasingly intersects with cathode chemistry and cell architecture. PVDF remains widely used for its electrochemical stability and adhesive strength, but modified formulations are being optimized for longevity, energy density, and tolerance to high-voltage operation. The broader trend is toward tailored binder portfolios, where a single product line is no longer sufficient across multiple cell chemistries and manufacturing routes.
Policy, Regulation, and Supply Chain Nationalization
Policy dynamics are reinforcing the push toward localized and more sustainable binder supply chains. Government-backed supply chain initiatives have supported domestic PVDF and SBR binder production expansions, including substantial capacity additions in North America. These efforts reflect a broader strategic priority: reducing dependence on concentrated foreign supply for critical battery materials and improving resilience against logistics disruptions. At the same time, regulatory mandates favoring water-based processes are reshaping procurement priorities. Manufacturers are increasingly evaluating binders not only on technical performance, but also on how well they enable lower-solvent processing, reduce environmental footprint, and align with plant-level sustainability targets. The outcome is a dual incentive structure: cost and reliability remain important, but environmental process compatibility is becoming a procurement gate.
Demand-Side Shifts Across Applications
Demand is shifting in ways that reward binders designed for different performance and durability profiles. Electric vehicles remain the largest application driver, reflecting their scale, performance requirements, and the need for long calendar and cycle life. Energy storage systems represent a second major growth path, with applications that often prioritize cost efficiency, safety, and extended service life under stationary cycling conditions. Consumer electronics continue to demand binder solutions that balance thin-electrode processing, space constraints, and consistency at high volume. Industrial and marine devices, while smaller in current market share, create specialized requirements around temperature tolerance, mechanical robustness, and safety margins. As demand disperses across these segments, binder suppliers are increasingly evaluated on application-specific fit rather than generic capability.
Cost, Scale, and Manufacturing Localization
Cost structure and manufacturing geography are interacting in ways that influence both supplier strategy and buyer behavior. Expanding local production capacity reduces exposure to freight costs, import delays, and regional supply shocks, but it also requires disciplined scale-up and consistent quality control. Water-based SBR and CMC-compatible grades, for example, are being scaled to meet broader demand from graphite and silicon anodes while maintaining cycle stability and enhanced capacity performance. For buyers, localized supply can improve lead-time predictability and technical support responsiveness. For suppliers, the challenge is to balance capital deployment against uncertain demand timing while preserving formulation integrity across multiple production sites.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of established polymer specialists, chemical majors, and regional-focused material suppliers. Japanese firms continue to hold strong positions in advanced binder technologies, with several companies emphasizing water-based anode binders, cathode-grade PVDF, and application-specific formulations aimed at tensile strength, cycle performance, and electrochemical stability. These companies often benefit from long development histories, close relationships with battery manufacturers, and the ability to offer formulation guidance beyond the product itself. At the same time, European and North American players are expanding capacity and broadening portfolios to serve cathode and anode requirements across multiple binder chemistries, including suspension and emulsion types, water-based SBR/CMC systems, and functional PVDF grades.
Differentiation Through Formulation Depth and Application Fit
Leaders are increasingly differentiating on formulation depth rather than volume alone. In cathode binder markets, differentiation often centers on adhesive strength, electrolyte resistance, and compatibility with high-energy or high-voltage designs. In anode markets, the emphasis shifts to slurry handling, adhesion under water-based processing, cycle stability with silicon-containing formulations, and the ability to support higher capacity without sacrificing electrode integrity. Suppliers that can present validated performance across these variables create stronger switching costs for buyers, because changing binders often requires requalification, slurry re-optimization, and cell-level testing. This dynamic favors companies that combine product breadth with application-specific engineering support and reliable qualification data.
Capacity Expansion and Localization as Strategic Moves
Recent activity shows that capacity and geographic positioning are becoming central strategic levers. In March 2025, one major supplier expanded U.S. manufacturing for water-based anode binders in Pennsylvania and Tennessee, targeting global lithium-ion battery demand with SBR and CMC-compatible grades. Around the same time, another firm began preparations for a new battery binder production line in Texas, expected to become operational in 2026 for localized supply. These moves are not merely capacity additions; they signal a deliberate alignment with regional demand, OEM localization expectations, and supply chain resilience goals. Local presence can improve technical engagement with cell manufacturers, reduce logistics risk, and support faster response to formulation tweaks required during pilot and ramp phases.
Market Structure Evolution and the Role of Specialized Entrants
The market is likely to continue evolving along two parallel tracks. On one hand, larger suppliers will seek to consolidate advantage through portfolio breadth, multi-region manufacturing, and qualification readiness across major application areas. On the other hand, specialized producers will remain relevant where niche formulations, localized feedstock advantage, or deep experience in a particular binder type create defensible positions. In practice, this creates a landscape where buyers may source standard grades from scale suppliers while relying on specialists for specific high-performance or application-tailored needs. The presence of companies focused on CMC, SBR, PAA for high-silicon anodes, and functionalized PVDF illustrates how segmentation is reinforcing itself. Over time, the most resilient players will be those that can move fluidly between commodity-scale supply and specialized formulation value.
Future Trends and Commercial Implications
Trend 1: Water-Based Processing as the Default Design Basis
The shift toward water-based binder processes is expected to deepen over the next three to five years. As environmental mandates and manufacturing sustainability goals gain traction, electrode production is likely to lean further into systems that reduce solvent dependence and the associated handling and recovery burden. The commercial implication is clear: binder portfolios built primarily around solvent-based compatibility may face growing marginalization in new production lines. Suppliers that have already adapted formulations for water-based slurry stability, drying behavior, and adhesion performance will be better positioned to participate in next-generation cell manufacturing. For buyers, this trend increases the importance of assessing supplier readiness for water-based qualification, not just current price-performance ratios.
Trend 2: Higher-Silicon and Chemically Diverse Anodes Driving Binder Complexity
Anode formulation is moving toward higher-silicon content and more diverse material blends, which places greater stress on binder performance. Binders will need to handle expansion, maintain contact integrity, and support stable cycling without compromising electrode processing. This trend creates an opportunity for suppliers offering advanced co-binder systems, PAA-based formulations, and engineered ratios that balance capacity with mechanical durability. It also raises the stakes for formulation transparency and testing support, because anode behavior is highly dependent on the interaction between active material, conductive additives, and binder architecture. Companies that can help customers optimize these interactions will capture value beyond the resin itself.
Trend 3: Qualification, Certification, and Supplier Reliability as Competitive Moats
As EV OEM qualification standards tighten and ISO-aligned testing requirements become more demanding, certification readiness will increasingly function as a competitive moat. The trend is toward more rigorous electrolyte compatibility testing, consistency verification, and documentation that supports multi-year validation cycles. This favors suppliers with established quality systems, predictable batch-to-batch performance, and the ability to support long qualification timelines. It also raises the importance of regional supply continuity, because qualification programs often prefer or require stable access to the same material source over extended periods. The practical commercial outcome is that supplier selection will place greater weight on reliability, documentation, and applied engineering support, especially in automotive and energy storage projects where downstream cost of failure is high.
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of market evolution. Raw material volatility may persist, particularly if feedstock pricing for PVDF, styrene, or cellulose-related inputs remains sensitive to macroeconomic and supply disruptions. A second risk is the possibility of uneven adoption of water-based processes, where some manufacturing lines or regions transition more slowly due to equipment constraints or formulation challenges. A third uncertainty lies in the speed and coordination of qualification cycles across automotive OEMs and cell makers, which can delay demand realization even when technical readiness exists. Finally, shifts in cathode and anode chemistry roadmaps could change the relative importance of specific binder types, making portfolio flexibility essential for suppliers and careful tracking essential for buyers.
Strategic Actions for Decision Makers
For Battery and Materials Manufacturers
Evaluate binder strategy as a system-level choice rather than a discrete procurement item. Map current and planned electrode chemistries against binder requirements, especially where water-based processing, silicon blending, or higher-energy cathode designs are involved. Prioritize suppliers that can demonstrate consistent performance across multiple production sites and provide formulation guidance during slurry optimization and cell qualification. Build dual-source or regional-supply options where qualification timelines and production continuity make it feasible, and align internal testing protocols with emerging certification expectations so that supplier changes do not create unnecessary delays.
For Investors and Strategic Planners
Focus on differentiation that translates into switching costs and recurring demand. In this market, sustainable advantage often comes from formulation depth, validation infrastructure, and regional manufacturing presence rather than brand alone. Track capacity expansions that align with localized demand and assess whether new entrants have the technical support capability to participate in qualification-heavy segments. Monitor feedstock sensitivity and formulation flexibility as indicators of resilience, and pay attention to how quickly suppliers can adapt to water-based processing requirements and higher-silicon anode trends. Portfolio exposure should favor companies that can serve both scale applications and specialized needs without sacrificing consistency.
For Procurement and Supply Chain Leaders
Treat binder sourcing as a risk and performance decision that should be coordinated with cell design roadmaps. Assess supplier readiness for water-based processing, electrolyte compatibility testing, and regional supply continuity, especially where OEM qualification and localization expectations are becoming more stringent. Use multi-year qualification and testing data as part of supplier evaluation, and ensure that cost negotiations do not obscure the potential downstream impact of inconsistent material performance. Where possible, align sourcing decisions with planned shifts in anode and cathode chemistry so that binder transitions are proactive rather than reactive.
The lithium-ion battery binders market is moving into a phase where technical complexity, regulatory direction, and supply chain geography jointly determine competitive outcomes. Growth is robust, but the real commercial value lies in understanding how formulation needs, processing shifts, and qualification requirements will reshape demand across EV, energy storage, consumer electronics, and specialized applications. Decision makers who track these dynamics closely will be better positioned to select suppliers, time capacity investments, and build resilient material strategies. For teams that need more granular segmentation data, regional demand patterns, and company-level benchmarking to support internal planning, the full research report provides a deeper evidence base and tailored analytical pathways.
For detailed analysis of this topic, please visit the official page: Binders for Lithium Ion Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


