



Steam Turbine Market: Asia Pacific’s Growth Drivers and the 2.8% CAGR Trajectory to 2032

The Steam Turbine Market at an Inflection Point: Strategy, Scale, and the Next Decade of Power Generation
The global steam turbine market is entering a phase of measured but decisive evolution. Valued at approximately 26.2 billion USD in 2025, the market has grown steadily from 22.82 billion USD in 2020, reflecting an average trajectory of 2.8% compound annual growth through 2032. While the headline numbers point to gradual expansion rather than explosive disruption, the underlying dynamics tell a more strategic story. Revenue concentration remains notable, with the top three firms capturing 48% of the market and the top five holding 50%, signaling that scale, technology access, and long-cycle project execution still reward incumbency. Yet the operational context is shifting fast: policy frameworks are tightening efficiency thresholds, data center demand is reshaping project pipelines, and material costs are pressuring margins across the value chain. For executives, investors, and procurement teams, the central question is no longer whether the market will grow, but where the growth will concentrate and how to position for it.
Market Snapshot: Steady Growth, Concentrated Structure, and a Changing Demand Base
Over the 2020 to 2025 period, the market expanded from the low 20-billion range to the mid-20s, with forward estimates reaching 31.79 billion USD by 2032. The compound annual growth rate of 2.8% captures a market that is expanding in line with infrastructure cycles rather than speculative demand. This baseline matters because it frames the strategic logic of the industry: steam turbines remain embedded in long-lived power assets, where efficiency, reliability, and compliance determine asset economics over decades.
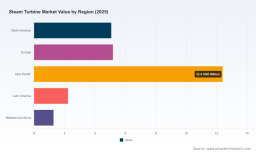
Regionally, the market reflects a global but uneven footprint. Asia Pacific accounts for the largest share of revenue, followed by Europe and North America, with Latin America and the Middle East and Africa forming smaller but strategically important segments tied to utility expansion and industrial cogeneration. By application, power generation dominates the demand base, with oil and gas and other industrial uses representing smaller but commercially relevant niches. By type, both impulse and reaction turbines continue to serve distinct operating envelopes, with selection driven by pressure regimes, thermal profiles, and plant architecture rather than a single universal design.
What matters for strategy is not the spreadsheet of splits but the direction of travel. Demand is increasingly shaped by large-scale power projects that couple high-efficiency turbines with grid reliability mandates and, in several regions, by new load centers that require dedicated generation capacity. At the same time, the market’s concentration suggests that competitive wins are often won through differentiated technology packages, service relationships, and the ability to move quickly on project bookings in a capital-intensive environment.
Key Challenges and Inflection Points
Three challenges define the current turn in the market. First, efficiency and emissions regulations are rewriting the economics of existing assets. Updated performance standards for stationary combustion turbines now impose efficiency subcategorization thresholds, with large low-utilization units facing design efficiency expectations around 38%. For operators and OEMs, this creates a compliance calculus that affects turbine selection, cycle design, and retrofit strategies.
Second, the material and cost environment is becoming more volatile. Trade dynamics have elevated prices for nickel and chromium-based alloys that are central to turbine component performance. In a market where uptime and thermal resilience are valued, input cost pressure can compress margins and alter the attractiveness of certain design choices, particularly for long-lead components and high-stress rotor and blade assemblies.
Third, demand is bifurcating. Traditional thermal and cogeneration applications continue to matter, but a new demand vector is emerging from power-intensive digital infrastructure. AI data center power demand is accelerating combined-cycle projects that incorporate steam turbines, with several projects targeting online operation around 2028. This creates a fast-moving opportunity set, but also raises execution risk around timeline compression, site readiness, and the coordination of turbine supply with broader generation and grid integration plans.
Key Drivers Reshaping the Steam Turbine Market
Technology Innovation and the Efficiency Mandate
Efficiency remains the central technical battleground. Steam turbine value is increasingly derived from design refinements that extract more work from the same thermal input, reduce losses in moisture and staging, and improve part-load performance for plants that cycle more frequently. The push is not only about peak efficiency but about flexibility: operators want turbines that can respond to variable load profiles, integrate with different heat sources, and maintain reliability under changing operating regimes.
Recent commercial activity underscores this direction. Siemens Energy has booked significant steam turbine orders that contributed to a record backlog of 138 billion EUR, indicating strong demand for large-scale turbine-generator sets in complex power projects. The company’s selection to supply steam turbine generator sets for a 1 GW AI data center power project illustrates how turbine technology is being embedded into new demand centers where reliability and scale matter. Equally telling is the binding contract signed for a condensing steam turbine destined for an advanced reactor power plant, signaling that turbine applications are expanding beyond conventional thermal cycles into next-generation nuclear infrastructure.
These developments matter because they show how innovation is being validated through orders, not just laboratory benchmarks. For manufacturers, the strategic prize is to align efficiency gains with real project economics: fuel savings, emissions compliance, maintenance intervals, and the ability to operate across a wider load range. For buyers, the question is whether a turbine package can support both today’s operational needs and tomorrow’s regulatory and demand scenarios.
Policy and Regulatory Pressure as a Market Organizer
Policy is no longer a background condition; it is shaping project pipelines and asset decisions. The U.S. Department of Energy allocated 475 million USD in mid-2025 to enhance steam turbine efficiency in clean energy infrastructure, a signal that public funding is being directed toward performance improvements that can bridge conventional and low-carbon generation pathways. This kind of targeted support can accelerate adoption of higher-efficiency designs, especially where operators seek to extend asset life or improve economics before a wider transition.
On the compliance side, updated standards for coal-fired steam generating units require conversion to natural gas or carbon capture retrofit across a 2030 to 2039 window. Combined with efficiency thresholds for stationary combustion turbines, these rules create a structured timeline of decision points. Some plants will retrofit, some will repower, and some will be replaced entirely. For the steam turbine sector, this means demand will be redistributed across retrofit packages, new combined-cycle builds, and specialized configurations tied to evolving fuel and emissions pathways.
The practical implication is that policy is acting as an organizer of demand. Projects are being sequenced around compliance deadlines, and turbine selection is increasingly tied to the chosen compliance route. This favors suppliers that can offer flexible, documentation-ready solutions and that can support operators through the engineering and approval processes that accompany regulatory change.
Demand-Side Shifts: Data Centers, Grid Reliability, and New Load Centers
The most visible demand-side disruption is coming from power-intensive digital infrastructure. AI data center power demand is accelerating combined-cycle projects that incorporate steam turbines, with several initiatives targeting online operation around 2028. For turbine suppliers, this represents a shift from traditional utility-led procurement to a more diversified set of developers and offtakers that may prioritize speed, reliability, and dedicated supply for critical facilities.
This trend is not simply about adding load. It is about how that load is served. Data center power projects often require firm capacity, predictable availability, and tight integration with balance-of-plant systems. Steam turbines in combined-cycle configurations can offer the efficiency and scale needed to serve large continuous loads, while also supporting grid reliability when deployed in regions where new generation must come online quickly. The strategic opportunity lies in the convergence of industrial-scale turbine capability with fast-track project execution and service readiness.
A second demand shift is the continued relevance of industrial cogeneration and oil and gas applications. While smaller in revenue terms than power generation, these uses depend on turbines that can operate efficiently in tailored thermal environments and support process heat as well as electricity. Demand here is less about headline growth and more about reliability, lifecycle support, and the ability to adapt to site-specific constraints.
Supply Chain and Cost Structure: Materials, Lead Times, and Margin Discipline
Cost structure is becoming a strategic variable rather than a static input. Tariff-driven increases in nickel and chromium-based alloy prices are affecting components that are both performance-critical and long-lead. For manufacturers, this creates a balancing act between design integrity, sourcing strategies, and pricing discipline. For buyers, it can translate into more variable procurement costs and longer planning horizons as supply chains adjust.
The response is likely to differentiate winners. Suppliers that secure resilient sourcing, standardize high-value components where possible, and integrate service and lifecycle support can protect margins and reduce exposure to spot volatility. Buyers that engage early on specification, long-lead item planning, and service agreements can reduce execution risk and avoid late-stage cost surprises. In this environment, the steam turbine market behaves less like a commodity transaction and more like a structured engineering partnership, where risk allocation and planning horizon matter as much as unit pricing.
PW Consulting
Competitive Landscape and Leading Strategies
Incumbents with Scale, Technology, and Backlog Advantage
The market is led by large, globally integrated OEMs with strong positions in utility and industrial steam turbines. Siemens Energy brings a broad portfolio spanning conventional, combined-cycle, and nuclear applications, with an emphasis on efficiency and sector integration. Its recent order activity, including the record backlog and assignments tied to large data center and advanced reactor projects, highlights a strategy centered on winning complex, high-value projects where turbine performance is closely tied to overall plant economics.
GE Vernova remains a dominant force in installed capacity, with a long track record in steam turbine families for power plant solutions and advanced combined-cycle reheat designs. Its scale in global installed base creates a durable service and upgrade opportunity, while continued product development in high-efficiency configurations supports new project competitiveness. For the market, GE’s position illustrates how installed-base breadth can complement new-equipment leadership through lifecycle revenue and retrofit potential.
Mitsubishi Heavy Industries is notable for high-efficiency steam turbines in gas turbine combined-cycle plants, including components with hydrogen co-firing capabilities. This positions the firm at the intersection of efficiency and fuel flexibility, an increasingly relevant pairing as operators evaluate lower-carbon pathways without sacrificing thermal performance. The strategic value is in offering turbines that can operate across evolving fuel mixes while maintaining plant output and reliability.
Regional Players and Specialized Strengths
Alongside the global incumbents, several regional and specialized players hold meaningful positions. Dongfang Electric and Shanghai Electric are leading Chinese suppliers of large-scale turbines for power generation and utility-scale combined-cycle systems, with strong domestic demand and growing export activity. Harbin Electric similarly manufactures steam turbines with substantial domestic and export capability, reinforcing the importance of China’s manufacturing base in the global supply picture.
Doosan Enerbility has built a profile around combined-cycle and data center power projects, including recent North American orders, showing how a mid-tier global player can win by aligning turbine supply with fast-growing demand segments and executing on international project pipelines. Bharat Heavy Electricals Limited continues to serve Indian power generation and cogeneration applications, where domestic utility demand and cogeneration needs support a steady commercial base. Toshiba Energy Systems & Solutions and Ansaldo Energia add further depth in combined-cycle, cogeneration, and industrial power applications, reflecting the value of specialized engineering capabilities and regional project relationships.
Strategic Positioning and Differentiation
Across these firms, differentiation is emerging along several axes. Technology leadership in efficiency and cycle design remains foundational, but it is increasingly paired with fuel flexibility, service integration, and the ability to support complex compliance requirements. Backlog strength and project execution capacity are becoming competitive assets, especially where demand is concentrated in large, long-cycle projects that reward organizational reliability.
Another axis is application breadth. Players that can move across conventional thermal, combined-cycle, cogeneration, and emerging nuclear or advanced reactor applications are better positioned to capture demand that shifts as policies and load centers evolve. This breadth is not merely a portfolio feature; it is a hedge against demand volatility and a way to maintain utilization across different project types and geographies.
Service and lifecycle capability also matter. In a market where installed assets operate for decades, the ability to provide upgrades, maintenance, and performance restoration can stabilize revenue and deepen customer relationships. The competitive logic is straightforward: the turbine sale is often the entry point, but the long-term value is shaped by how well the supplier supports availability, efficiency retention, and compliance over the asset life.
Worldwide Steam Turbine for Power Station Market
Market Structure Trends: Integration, Differentiation, and New Entry Points
The market’s concentration suggests a tendency toward consolidation of advantage among scaled players, but it does not imply stagnation. Instead, the structure appears to be evolving through differentiation rather than pure consolidation. Global incumbents compete on technology, installed base, and complex project delivery, while regional players compete on cost, domestic relationships, and export execution. At the same time, new demand centers such as data center generation and advanced nuclear create entry points for specialized partnerships and project-driven wins, even if the core manufacturing barrier remains high.
This means the landscape is likely to remain layered. Leaders will continue to defend their positions through efficiency, scale, and service, while challengers and specialists will seek niches where project timeliness, regional proximity, or application-specific engineering provides an edge. For buyers, this layered structure creates options but also requires careful evaluation of technology fit, delivery risk, and long-term support.
Forward Outlook: Three Trends to Watch Over the Next 3 to 5 Years
Trend 1: Efficiency as the Default Purchase Criterion
Efficiency is likely to become an even more explicit purchase criterion as compliance windows tighten and fuel and emissions costs remain relevant. Projects will increasingly be evaluated on how turbine selection supports both immediate economics and future regulatory readiness. This favors designs that offer strong part-load performance, integration with higher-efficiency cycles, and clear documentation for compliance and permitting processes.
The commercial opportunity is in packages that link turbine performance to plant-level outcomes: reduced fuel intensity, lower exposure to emissions-related retrofit costs, and improved flexibility for cycling or dedicated load service. The risk is that efficiency gains can be undermined if material costs or lead times disrupt execution, or if operators underinvest in balance-of-plant and service planning that protects performance over time.
Trend 2: Demand Reallocation Toward Large Combined-Cycle and Dedicated Generation
The next few years are likely to see continued reallocation of demand toward large combined-cycle projects and dedicated generation for new load centers. AI data center power demand is already accelerating combined-cycle projects that incorporate steam turbines, and this pipeline is expected to shape order flow as projects move toward commissioning around 2028 and beyond. At the same time, retrofit and repower activity tied to coal-to-gas conversion and emissions compliance will redistribute demand across different project types.
For suppliers, the opportunity lies in aligning turbine offerings with the pacing of these projects and in demonstrating the ability to deliver under compressed timelines without compromising reliability. For developers and operators, the opportunity is in securing firm capacity with efficient, scalable generation assets that can support continuous loads and contribute to grid stability. The uncertainty is execution: timeline compression can stress supply chains, site readiness, and integration planning, especially when multiple large projects compete for the same materials and engineering resources.
Trend 3: Fuel Flexibility and Lifecycle Value as Competitive Differentiators
As operators evaluate lower-carbon pathways, fuel flexibility and lifecycle support will likely become more prominent differentiators. Hydrogen co-firing readiness, compatibility with changing fuel mixes, and upgrade paths that preserve efficiency and availability will matter for assets expected to operate through transition periods. Equally important will be service models that help operators manage performance, compliance, and maintenance across the asset life.
The strategic opportunity is in offering turbines and support structures that reduce the risk of stranded assets and extend useful life under evolving operating conditions. The risk is that fuel-flexibility claims must be matched by operational reality and that service promises must be delivered consistently, especially in markets where skilled labor and parts availability are constrained.
Actionable Guidance for Decision Makers
For Manufacturers and Suppliers
Position around efficiency, fuel flexibility, and delivery credibility. The market rewards technology that can be demonstrated in real projects, not only in specifications. Prioritize long-lead planning, resilient sourcing for critical alloys, and service integration that protects margins against input cost volatility. Where possible, build project-ready packages that simplify compliance documentation and reduce engineering friction for operators facing regulatory deadlines. Differentiate through application breadth where it can be supported by genuine engineering depth, especially in combined-cycle, cogeneration, and emerging nuclear-related applications.
For Investors
Evaluate exposure by project pipeline quality, backlog durability, and the ability to serve high-growth demand vectors without overconcentrating on any single cycle. The market’s 2.8% growth trajectory is steady, but the returns are likely to be uneven across players depending on their execution, technology positioning, and service mix. Watch for signs of margin resilience in the face of alloy cost pressure, and assess whether firms have credible pathways to capture data center-linked generation and retrofit-driven demand without compromising delivery reliability. Concentration in the market means scale matters, but differentiation in efficiency, fuel flexibility, and lifecycle support can determine who captures the higher-value segments of demand.
For Procurement and Operators
Treat turbine selection as a multi-decade decision shaped by compliance timelines, load profiles, and service realities. Engage early on specifications, long-lead items, and balance-of-plant coordination to reduce execution risk, especially for large combined-cycle or dedicated generation projects with ambitious commissioning targets. Evaluate suppliers not only on unit economics but on documentation support, upgrade paths, and the ability to sustain performance through regulatory transitions. In a market where material costs and lead times can shift, early planning and clear risk allocation are often as valuable as negotiating price.
Closing Perspective
The steam turbine market is not defined by rapid disruption but by a set of converging pressures that reward disciplined strategy. Efficiency, compliance, new demand centers, and cost discipline are reshaping where growth concentrates and how value is captured. The firms that navigate this environment well will be those that combine technical credibility with project execution, fuel flexibility with lifecycle support, and global scale with the ability to serve emerging demand channels. For executives and investors, the practical task is to map these trends to specific pipelines, asset strategies, and sourcing decisions before the next wave of project awards and compliance deadlines settles the market’s direction.
For a detailed breakdown of market size by region, type, and application, along with company-level profiles, recent order and contract developments, and regulatory and material cost dynamics, the full research report provides the segmented data and customized recommendations needed to support planning at the project and portfolio level.
Gas Turbine Market
For detailed analysis of this topic, please visit the official page: Steam Turbine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


