



Engine-Driven Welders Market: How 4.91% CAGR Shapes the 2032 Outlook

Strategic Trends and Commercial Opportunities in the Engine-Driven Welders Market
Market Landscape and Core Challenges
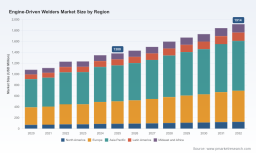
The global market for engine-driven welders has demonstrated steady expansion over the past five years, with total revenue climbing from approximately USD 1.08 billion in 2020 to a projected USD 1.38 billion in 2025. Growth is expected to continue along a 4.91 percent CAGR through 2032, pushing the market toward roughly USD 1.91 billion by the end of the forecast period. This trajectory reflects a mature but resilient equipment category that sits at the intersection of construction, energy infrastructure, and industrial maintenance. Rather than experiencing volatile boom-and-bust cycles, the segment has grown in a measured fashion, supported by replacement demand, expanding project pipelines, and the ongoing need for mobile power and welding capability in remote or off-grid environments.
The current landscape is defined by a concentration of demand among a handful of large players. The top three manufacturers account for roughly 68.5 percent of revenue, while the top five hold about 82.2 percent. Such concentration indicates that scale advantages in distribution, service networks, and engine sourcing remain decisive. At the same time, the market is not monolithic: demand patterns differ significantly by region, fuel type, and end-use application, creating pockets of opportunity that are less visible in headline figures. For decision makers, understanding where growth is actually coming from—and where friction is building—is more valuable than relying on aggregate market size alone.
Key Challenges and Inflection Points
Three interconnected challenges are shaping the near-term direction of the engine-driven welders market. First, the product category is caught between the need for rugged, high-output equipment and tightening emissions expectations. Many models rely on small internal combustion engines that must meet increasingly strict regulatory standards, particularly in North American and European markets. Compliance requirements affect engine selection, aftertreatment systems, and ultimately total cost of ownership, forcing manufacturers to balance performance, footprint, and certification burdens.
PW Consulting Automotive & Machinery Research Center
Second, input cost volatility remains a persistent pressure point. Engine-driven welders integrate gasoline, diesel, or LPG engines alongside alternators, control systems, and heavy-duty structural components. Fluctuations in raw material and component pricing can compress margins or ripple through end-user pricing, especially when manufacturers cannot pass costs through quickly enough. Since these machines are often purchased for demanding field conditions, buyers are sensitive to both upfront price and long-term reliability, making cost management a strategic rather than purely tactical issue.
Third, the market is facing a subtle but important shift in how jobsite labor is valued. Equipment that combines welding and auxiliary power generation can reduce the number of separate units and personnel required on site, lowering overall operational complexity. This labor-saving logic is increasingly attractive in environments where skilled trades are scarce or where project schedules are compressed. However, it also raises the bar for what buyers expect from a single machine: they want multi-functionality without sacrificing duty cycle, fuel efficiency, or serviceability. Manufacturers that fail to deliver integrated, dependable solutions risk losing share to alternatives that better match evolving field economics.
Key Drivers of Market Change
Technology Innovation and Performance Gains
Performance improvement remains one of the most direct catalysts for demand. Recent product introductions show a clear push toward higher welding output, better duty cycle characteristics, and more compact mechanical footprints. For example, ESAB’s introduction of the Ruffian EMP 270G engine-driven welder/generator highlighted a 270-amp welding output at 100 percent duty cycle, paired with 11 kW of generator power and a 23.5-HP Kohler Command Pro engine. The unit is assembled in Texas and positioned for harsh construction environments, with a smaller footprint designed to fit service trucks. Similarly, The Lincoln Electric Company’s launch of the Frontier 500X emphasized advanced arc performance and technology aimed at challenging construction and industrial settings.
These launches point to a broader engineering theme: buyers increasingly value machines that can sustain output under continuous use while remaining portable enough for mobile crews. Improved arc performance, better voltage stability, and more efficient engine-generator integration reduce downtime and expand the range of applications a single unit can handle. For manufacturers, the opportunity lies not just in adding features, but in optimizing the entire system so that welding quality, generator reliability, and fuel consumption work together in the field.
Policy and Regulatory Environment
Regulatory pressure on engine emissions continues to influence product design and market access. Engine-driven welder platforms that rely on diesel, gasoline, or LPG must navigate compliance requirements that differ across jurisdictions and customer segments. In the United States, certain engine-driven welder models are subject to EPA engine standards, which shapes engine sourcing decisions and can affect time-to-market for new configurations. This does not eliminate growth, but it does raise the importance of proactive compliance planning. Manufacturers that integrate emissions considerations early—rather than treating them as a retrofit problem—can reduce redesign risk and maintain smoother product rollout schedules.
Regulation also indirectly affects buyer behavior. Contractors and fleet managers increasingly factor compliance into procurement decisions because non-conforming equipment can create operational risk on regulated sites. As a result, certification and documented compliance are becoming part of the commercial value proposition, especially in public works, utilities, and oil and gas-adjacent projects where audit trails and environmental requirements carry real weight.
Demand-Side Shifts in Construction, Pipeline, and Mining
Demand is being shaped by how end users organize work on site. Construction, pipeline, mining, and broader infrastructure activities remain central to consumption, but the competitive edge is shifting toward equipment that can reduce mobilization costs and simplify field logistics. In remote or temporary work zones, the ability to carry both welding capability and auxiliary power in one unit can lower the burden on support equipment and crew coordination. This is especially relevant where fuel availability, transport weight, and service access are constraints.
A related demand-side change is the growing preference for application-tuned configurations rather than generic multi-purpose machines. Pipeline work, for instance, may prioritize stable arc conditions and continuous operation, while construction crews may value quick deployment, compact storage, and rugged serviceability. Mining environments can impose additional demands for durability and dust-related durability. Buyers are increasingly looking for evidence that a machine has been engineered for their specific operating conditions, which rewards manufacturers that can align product claims with real-world use cases.
Supply Chain and Cost Structure Evolution
Cost structures in this market are sensitive to engine availability, electrical component pricing, and the broader logistics of building heavy equipment. Because engine-driven welders depend on engines, alternators, and control systems, suppliers must manage exposure to component cost swings and lead-time variability. In practice, this means that successful players often secure dependable engine sourcing and maintain buffer strategies for critical subsystems. The commercial impact is significant: even a well-designed machine can struggle if production planning cannot keep pace with demand or if margin erosion forces price increases that slow customer adoption.
At the same time, the economics of ownership are tilting the discussion toward total cost rather than sticker price. Fuel consumption, maintenance intervals, and downtime all influence whether a machine is profitable over its service life. This encourages buying decisions that favor durability and service network coverage, particularly in regions where equipment downtime can stall an entire project sequence. For manufacturers, this environment rewards consistent quality and predictable support more than short-term promotional pricing.
Competitive Landscape and Leading Strategies
Core Players and Strategic Positioning
The competitive set spans established welding specialists, diversified equipment suppliers, and regional manufacturers with distinct operational strengths. The Lincoln Electric Company remains a prominent U.S. manufacturer of engine-driven welders and generators, with product families such as the Ranger, Frontier, and Vantage lines commonly associated with Kohler and Kubota engines. Miller Electric Mfg. LLC is another strong U.S. presence, offering engine-driven welder platforms including the Bobcat and Trailblazer series as well as all-in-one EnPak models, frequently paired with Kohler engines. ESAB Corporation continues to compete with welder-generator platforms such as the Ruffian EMP 270G series, assembled in Texas and aimed at construction and oil/gas demand. Hobart Brothers Company also participates as a supplier and manufacturer of engine-driven welders, including Champion series models, reinforcing the importance of strong brand recognition in the North American market.
Beyond these leaders, several additional players contribute to a diverse supply base. Tomahawk Power LLC produces portable engine-driven welders and generators, including series models built around 15-HP engines, appealing to users who prioritize mobility and straightforward field operation. Multiquip Inc. supplies engine-driven welders and generators for construction and industrial applications, while Denyo Co. Ltd. from Japan emphasizes compact units with a focus on fuel efficiency and overseas TIG welding shipments. MOSA S.p.A. in Italy markets engine-driven welders and generators under the CANAWELD brand for professional and industrial use, and Shindaiwa Co. Ltd. offers portable and rugged units for field and agricultural applications. In the broader export and industrial space, Cruxweld Industrial Equipment Ltd in China manufactures engine-driven welders and generators for industrial welding and power generation, and Welding Industries of Australia supplies and manufactures for domestic and export markets.
Differentiation and Competitive Advantages
Differentiation in this market tends to cluster around three dimensions: engine and power integration, application-specific engineering, and service ecosystem strength. Product examples show that pairing proven engines with welding and generator outputs that match field demands can create a credible performance narrative. The recent ESAB and Lincoln Electric introductions illustrate a pattern where manufacturers highlight duty cycle, output stability, and environmental suitability together rather than treating them as separate selling points.
Another differentiator is build-and-source strategy. Units assembled in specific locations for regional demand can help manufacturers align with local compliance expectations, service expectations, and customer preferences. Along similar lines, brands that maintain strong recognition among contractors and fleet buyers benefit from lower sales friction and repeat demand in replacement cycles. In a concentrated market, reputation and reliability often matter as much as technical specifications because procurement decisions are frequently made by teams that prioritize uptime and predictable support.
Market Structure Evolution
The competitive structure appears to be moving along two parallel paths: consolidation among scaled players and continued niche activity around specialized use cases. High concentration at the top suggests that large manufacturers have advantages in engine partnerships, distribution reach, and brand equity. That said, the presence of multiple regional and application-focused suppliers indicates that smaller or more specialized players can still compete by serving specific customer segments, fuel preferences, or export markets.
New entrants and smaller producers are likely to find the most traction where they can respond faster to local requirements or offer configurations that larger brands do not prioritize. Conversely, incumbents are likely to continue strengthening their positions through product line depth, service coverage, and adherence to compliance-driven engineering. The result may be a market where the leaders protect broad demand while specialized manufacturers capture targeted niches, creating a layered competitive environment rather than a simple winner-takes-all outcome.
Worldwide TIG Welder Market
Forward-Looking Trends and Commercial Opportunities
Integration of Welding and Power as a Standard Expectation
Over the next three to five years, the combination of welding output and auxiliary generation is likely to become less of a bonus feature and more of a baseline expectation in many field applications. Buyers in construction, pipeline, and industrial maintenance are increasingly motivated by equipment that reduces equipment count and simplifies crew deployment. Commercial opportunity lies in designing machines that make this integration seamless, with stable power delivery, intuitive controls, and configurations that match actual jobsite usage. Manufacturers that can demonstrate dependable multi-function performance will be better positioned to capture replacement cycles and fleet standardization decisions.
Fuel-Type and Compliance-Driven Product Segmentation
Fuel choice and emissions compliance will continue to shape demand segmentation. Diesel, gasoline, and LPG options each carry different advantages in terms of fuel availability, runtime economics, and regional acceptance. As regulatory expectations evolve, product portfolios may become more clearly segmented by market and application, with some platforms optimized for strict compliance environments and others positioned where portability or fuel logistics matter more. For suppliers, the strategic opportunity is to plan engine and emissions strategies proactively, so that product families can serve multiple regulatory contexts without excessive rework.
Regional Demand Maturation and Export Dynamics
Demand growth will not be uniform across regions. Some markets will be driven by ongoing infrastructure and energy-related activity, while others will depend more on equipment replacement and fleet modernization. Export-oriented manufacturers may find chances to expand where local production capacity is limited or where regional service models are still developing. The commercial implication is that market expansion will increasingly depend on aligning product offerings with regional operating conditions, support networks, and fuel preferences, rather than assuming that a single global configuration fits all markets.
Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Regulatory changes may accelerate or restructure engine compliance requirements in ways that affect product timing and cost. Input cost volatility can compress margins and slow adoption if pricing becomes less predictable. In addition, competition from alternative power solutions or hybrid equipment concepts could pressure the role of traditional engine-driven platforms in certain applications. Economic slowdowns in construction or industrial activity may also affect procurement cycles, especially for discretionary fleet upgrades. Manufacturers and buyers alike should monitor these factors as part of capacity planning and investment decisions.
Actionable Recommendations for Decision Makers
For Manufacturers
Invest in integrated product engineering that treats welding performance, generator output, and engine compliance as a combined system rather than separate components. Prioritize engine partnerships and sourcing resilience to reduce exposure to component cost swings and lead-time disruption. Build product narratives around real field conditions—duty cycle, footprint, serviceability, and fuel efficiency—so that buyer decisions are supported by practical operating value rather than specification sheets alone. Where possible, differentiate through application-tuned variants that match the needs of construction, pipeline, mining, and infrastructure users.
For Investors
Evaluate companies based on their ability to manage compliance-driven engineering, maintain dependable engine and component sourcing, and sustain service network strength. In a concentrated market, scale advantages matter, but niche positioning can still create attractive returns where a company serves a specific fuel type, application, or regional export channel. Pay attention to product launch cadence and whether new introductions reflect genuine field requirements, since sustained relevance in this category depends on aligning engineering with customer operating economics.
Welding Equipment Market
For Procurement and End-User Buyers
Evaluate total cost of ownership with a focus on downtime, fuel efficiency, service access, and compliance status rather than purchase price alone. Consider whether a single welder-generator platform can reduce equipment mobilization and simplify field staffing for the applications you run most often. Request configuration details that reflect actual jobsite conditions, including intended duty cycle, engine type, and service support coverage, so that purchasing decisions align with operational risk and maintenance planning.
For decision makers who need a more detailed view of segmentation splits, regional demand patterns, and company-level positioning, the full research report provides deeper context beyond the strategic overview presented here. A more granular reading of the market can help translate these trends into procurement timing, product investment choices, and competitive planning with greater precision.
For detailed analysis of this topic, please visit the official page: Engine-Driven Welders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


