



IR Lens Market 2026: Why 7.52% CAGR and Thermal Imaging Growth Redefine the $315M Outlook

Strategic Shifts in the Infrared Lens Market: Navigating Growth, Constraints, and Competitive Evolution
Market Landscape and Core Challenges
The infrared lens market has entered a phase of sustained expansion, driven by broadening application horizons and evolving technical requirements across industrial, defense, and commercial sectors. Current market sizing places the sector at approximately $192.35 million in 2025, with a projected trajectory reaching $315.68 million by 2032. This expansion reflects a compound annual growth rate of 7.52 percent, signaling steady demand acceleration rather than speculative scaling. The historical progression from 2020 through 2025 demonstrates consistent year-over-year increases, with recent momentum indicating that structural demand drivers are gaining traction rather than relying on temporary cyclical upturns.
Despite the positive trajectory, the industry operates within a highly concentrated environment. The top three players collectively account for 41.2 percent of total market share, while the leading five firms capture 58.5 percent. This concentration shapes pricing dynamics, supply chain negotiation leverage, and the ability to absorb regulatory or material disruptions. It also means that market entry barriers remain substantial for new participants lacking established relationships, certified manufacturing capabilities, or access to specialized substrate materials.
Three critical challenges currently define the market's inflection point. First, raw material constraints have introduced volatility into production planning and cost structures. Germanium supply chain disruptions have extended lead times and altered pricing dynamics for infrared optics, creating uncertainty for manufacturers who rely on consistent substrate availability. Second, geopolitical export controls over critical materials such as gallium and germanium have introduced compliance complexity and sourcing risks, particularly for defense and industrial applications that require uninterrupted supply chains. Third, the tension between performance requirements and cost efficiency continues to pressure manufacturers. High-performance thermal imaging and continuous zoom optics demand precise engineering and specialized materials, yet end-use markets increasingly expect scalable pricing and reliable delivery schedules.
These challenges are not isolated obstacles. They interact to shape procurement strategies, influence regional sourcing preferences, and drive innovation toward alternative materials and manufacturing approaches. Companies that treat these pressures as strategic variables rather than operational inconveniences are positioning themselves to capture disproportionate value as the market matures.
Key Growth Drivers and Structural Shifts
Technological Innovation and Material Diversification
Material science advancement represents one of the most consequential drivers reshaping the infrared lens landscape. Traditional germanium and silicon substrates continue to anchor high-performance applications, but the push for sustainable alternatives and cost-effective manufacturing is accelerating. Recent developments highlight this shift, including the creation of repairable polymer-based infrared lenses that utilize sulfur and organic co-monomers as a sustainable germanium alternative for thermal imaging. Such innovations address two simultaneous pressures: the need to reduce dependence on constrained specialty materials and the desire to lower manufacturing costs without sacrificing optical performance in specific wavelength ranges.
Worldwide Microbolometer Infrared Detector Market
Alongside material diversification, catalog expansions and product line extensions reflect deepening technical capabilities across the spectrum. The release of updated infrared optics catalogs featuring new short-wave infrared and medium-wave infrared zoom lenses demonstrates how manufacturers are broadening their offerings to meet demand for continuous zoom functionality, extended spectral coverage, and modular design flexibility. These advancements allow system integrators to configure solutions for defense, security, and industrial use cases without committing to entirely custom development cycles, reducing time-to-deployment and expanding addressable application portfolios.
The strategic implication is clear. Innovation in infrared optics is no longer limited to incremental improvements in lens curvature or coating technology. It now encompasses material substitution, repairability, modular assembly design, and spectral range expansion. Organizations that invest in these dimensions can differentiate themselves across both premium performance segments and high-volume commercial applications.
Policy and Regulatory Pressures Reshaping Supply Chains
Regulatory and geopolitical developments have become fundamental drivers of market behavior, influencing where production occurs, which materials are sourced, and how compliance is managed. Chinese export controls on gallium and germanium have introduced tangible risks for infrared lens production in defense and industrial applications. These controls compel manufacturers to evaluate supply chain resilience, diversify sourcing strategies, and in some cases accelerate development of alternative material pathways.
In parallel, compliance requirements such as National Defense Authorization Act-aligned domestic sourcing for certain United States defense programs have elevated the importance of supply chain security. Infrared lens procurement is increasingly evaluated not only on performance and cost but also on origin traceability, domestic manufacturing capability, and alignment with program security requirements. This dynamic has prompted the establishment of domestic production capacity for alternative materials, including chalcogenide glass production in the United States, aimed at mitigating foreign export control exposure.
These regulatory shifts create both constraints and opportunities. Companies with established domestic or allied-nation manufacturing footprints can leverage compliance as a competitive advantage in defense and security tenders. At the same time, organizations dependent on single-region sourcing face elevated risk and may need to restructure supplier relationships or invest in localized capacity. The broader effect is a market in which supply chain sovereignty is becoming a strategic asset as significant as optical engineering expertise.
Demand-Side Evolution Across Applications
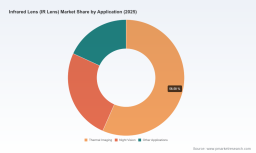
Demand growth is being propelled by expanding application footprints rather than a single dominant sector. Thermal imaging continues to represent the largest application segment, underpinned by requirements in defense, surveillance, industrial monitoring, and uncrewed systems. Night vision applications maintain substantial demand, reflecting ongoing needs in military, security, and specialized industrial contexts. Beyond these core categories, additional applications are contributing incremental growth as infrared imaging finds new roles in automated inspection, environmental sensing, and advanced driver-assistance systems.
A notable demand-side development is the emphasis on high-volume production readiness and supply continuity. Camera module announcements focused on high-volume manufacturing and uninterrupted supply illustrate how end customers are prioritizing availability and scalability alongside optical performance. This trend is particularly visible in automotive, security, and uncrewed platform markets, where deployment programs depend on predictable production pipelines and component consistency. Manufacturers that can deliver ready-to-integrate modules, maintain stable lead times, and support scaling requirements are gaining preference in tenders and commercial contracts.
The evolving demand profile alsoencourages convergence between component suppliers and system integrators. As end applications become more complex, customers seek partners capable of delivering lens assemblies, coatings, and integration support within a coordinated development framework. This shift rewards vertically integrated manufacturers and those able to provide application-specific engineering services rather than purely catalog-based transactions.
Supply Chain Configuration and Cost Structure Optimization
Cost structure dynamics are being reshaped by manufacturing strategy as much as by material prices. Vertical integration in infrared lens production reduces overall labor and material costs by consolidating raw material handling, substrate processing, and assembly within controlled internal operations. This approach provides several advantages: improved quality consistency, faster iteration on custom designs, stronger protection of proprietary processes, and reduced exposure to intermediary supplier disruptions.
At the same time, vertical integration requires capital commitment and operational scale, making it more accessible to established manufacturers. Smaller or specialty-focused firms often compete by narrowing their application focus, offering highly customized solutions, or concentrating on niche material capabilities that differentiate them from broader-line competitors. The market therefore exhibits a dual structure: vertically integrated players compete on volume, reliability, and cost optimization, while specialized manufacturers compete on customization, rapid engineering support, and application expertise.
For decision makers, the supply chain question is not whether to pursue integration but how to balance control, flexibility, and cost. As material constraints and compliance requirements persist, manufacturers that can demonstrate supply resilience, predictable lead times, and transparent sourcing will increasingly be favored in both defense and commercial procurement decisions.
Competitive Landscape and Strategic Positioning
Established Leaders and Differentiation Levers
The competitive field includes a diverse set of manufacturers spanning defense-oriented integrators, precision optics specialists, material-focused producers, and catalog-to-custom suppliers. Several patterns define how leading companies position themselves. Vertically integrated manufacturers of custom infrared lenses and assemblies for defense, surveillance, and thermal imaging have built advantage through end-to-end control of substrate selection, lens design, and assembly, while also developing germanium alternative solutions and medium-wave and long-wave infrared capabilities. This positioning allows them to serve programs requiring tailored optical performance and supply continuity.
Precision optics manufacturers producing uncooled infrared lenses for automotive, surveillance, and security applications leverage mature manufacturing processes and established customer relationships in high-volume sectors. Their differentiation often centers on consistency, production scalability, and the ability to embed infrared optics into broader system designs. Producers of high-performance long-wave infrared lenses using proprietary germanium and chalcogenide glasses occupy a specialized material leadership position, supplying both raw materials and assemblies for automotive, medical, and security applications. Their value proposition combines material innovation with application-specific lens design.
Specialists in precision infrared optics, including continuous zoom lenses for medium-wave, short-wave, and long-wave infrared across defense, security, and industrial use, differentiate through zoom capability, spectral range breadth, and catalog-driven flexibility. Manufacturers of precision infrared lenses and components for thermal imaging and industrial applications, as well as producers of uncooled infrared lenses for military and civilian thermal imaging systems, often compete by combining competitive cost structures with expanding technical capabilities in specific regional or application niches.
Large defense and aerospace suppliers contribute scale, program experience, and electro-optical/infrared subsystem integration capabilities spanning missile seekers, infrared search and track, and space applications. OEM providers of custom medium-wave and long-wave infrared lens assemblies and continuous zoom lenses for thermal imaging in defense, automotive, and uncrewed systems combine application breadth with custom engineering capacity. Catalog and stock suppliers of infrared lenses including germanium, zinc selenide, and sapphire for thermal imaging and laser applications serve rapid-prototype and lower-volume needs, while custom assembly manufacturers using multiple substrate types support defense, spectroscopy, and laser applications through material flexibility and engineering responsiveness.
Market Evolution: Consolidation, Specialization, and New Entrants
The market is evolving along multiple trajectories simultaneously. Concentration among leading players suggests ongoing consolidation potential, particularly where scale, compliance readiness, and vertical integration create advantages in large defense and industrial programs. At the same time, specialization remains viable for firms that can command premium positioning through material expertise, application focus, or rapid custom engineering. New entrants are most likely to succeed by addressing a clearly defined gap, such as alternative material lenses, domestic supply chain compliance, or specific zoom and spectral range requirements that larger suppliers do not prioritize.
Recent product and capability developments illustrate how competition is intensifying across multiple fronts. A university-backed development of a repairable polymer-based infrared lens using sulfur and organic co-monomers signals emerging interest in sustainable germanium alternatives for thermal imaging. A major optics supplier's 2026 catalog release featuring new short-wave and medium-wave zoom lenses reflects the push to expand ready-to-deploy optical options across spectral bands. An OEM camera module announcement focused on long-wave infrared, high-volume production, and supply continuity underscores the growing importance of manufacturing readiness alongside optical performance.
Together, these developments show that competition is no longer defined solely by who offers the highest resolution or broadest coating portfolio. It increasingly revolves around material resilience, supply continuity, spectral and zoom flexibility, compliance alignment, and the ability to move from design to volume production efficiently.
Forward Outlook: Trends Shaping the Next Three to Five Years
Several trends are likely to define market direction through the remainder of the decade. First, alternative material adoption is expected to gain momentum, particularly where germanium constraints persist or where cost and sustainability objectives favor polymer-based or chalcogenide glass approaches. This trend will not eliminate traditional substrates, but it will expand the material toolkit available to designers and create new competitive dynamics around performance, cost, and supply reliability.
Second, compliance-driven sourcing is likely to become a more explicit factor in procurement decisions, especially for defense and security applications. Domestic and allied-nation production capacity, traceability, and program-aligned compliance will increasingly function as selection criteria alongside optical specifications. Suppliers able to demonstrate secure, compliant sourcing pathways will have an advantage in restricted or high-security procurement environments.
Third, the demand for high-volume, supply-continuous assemblies and modules will continue to rise as infrared imaging expands into automotive, uncrewed systems, industrial automation, and security deployments. This trend favors manufacturers with scalable production processes, stable lead times, and the ability to support integration at volume. It also encourages closer collaboration between lens suppliers and system developers to reduce iteration cycles and ensure compatibility across program lifecycles.
These trends create commercial opportunities for organizations that can align material innovation, supply resilience, and application readiness. Companies investing in alternative materials, expanding zoom and spectral offerings, and strengthening domestic or compliant production capacity are well positioned to capture share in both premium and volume segments. At the same time, uncertainty remains. Material availability, geopolitical developments, and evolving compliance requirements can shift sourcing economics and competitive balance more quickly than product development cycles. Market participants should therefore treat flexibility, scenario planning, and supplier diversification as core capabilities rather than optional safeguards.
PW Consulting
Strategic Recommendations for Decision Makers
Manufacturers should evaluate their material and supply chain exposure with greater urgency. Where germanium dependence is significant, exploring alternative substrate pathways, strengthening vertical integration, or securing compliant domestic sources can reduce volatility and improve competitiveness in defense and industrial programs. Expanding catalog and zoom offerings while maintaining custom engineering capacity can also broaden addressable demand without sacrificing specialization. Investing in high-volume production readiness and supply continuity planning will increasingly differentiate suppliers as customers prioritize availability alongside performance.
Investors should assess companies based on their ability to manage material constraints, comply with sourcing requirements, and scale production without compromising optical quality. Vertical integration, alternative material development, and compliance-aligned manufacturing footprints represent tangible indicators of resilience. Portfolio decisions should weigh not only current revenue concentration but also exposure to export controls, raw material volatility, and the pace at which a company can transition from custom development to volume deployment. Firms that combine technical differentiation with supply chain security are likely to demonstrate more durable growth profiles.
Procurement and sourcing leaders should incorporate compliance, lead-time reliability, and material diversification into evaluation frameworks alongside optical specifications. For programs with defense, security, or industrial continuity requirements, supplier selection should account for domestic production capability, traceability, and the capacity to support scaling without disruption. Engaging suppliers early in design cycles can reduce integration risk and improve alignment between lens performance, assembly constraints, and program timelines. Building a diversified supplier base across material types and geographic footprints can also mitigate concentration risk while preserving access to specialized capabilities.
For organizations seeking granular segmentation data, regional dynamics, pricing context, and customized strategic scenarios, a complete research report provides detailed breakdowns across market segments and competitive profiles. Accessing deeper data and tailored analysis can support more precise planning in areas such as material substitution timelines, compliance-aligned sourcing strategies, and segment-specific growth opportunities.
Infrared Detector Market
For detailed analysis of this topic, please visit the official page: Infrared Lens (IR Lens) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


