



Ignition Coil Market 2026: What the 4.4% CAGR and $15.9B Trajectory Reveal About Future Demand

Ignition Coil Market: Strategic Trends and Commercial Opportunities in a Reshaping Industry
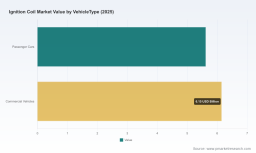
The ignition coil market is set to expand steadily through the forecast period, with the global market valued at approximately USD 11.77 billion in 2025 and projected to reach USD 15.91 billion by 2032, underpinned by a CAGR of 4.4%. This trajectory reflects a mature yet evolving category where incremental technological gains, tightening emission standards, and shifting supply chain dynamics are reshaping competitive positioning. Over the 2020–2025 historical window, the market moved from roughly USD 9.49 billion to just under USD 12 billion, indicating consistent demand growth driven by vehicle parc expansion, replacement cycles, and a gradual transition toward higher-performance coil architectures. As the market advances into the 2026–2032 horizon, growth will be less about volume alone and more about value migration toward precision-engineered solutions that meet stricter combustion and emissions requirements. This creates an inflection point for manufacturers, investors, and procurement leaders to reassess sourcing strategies, portfolio priorities, and regional exposure.
Navigating Core Challenges and Inflection Points
Three interconnected challenges are defining the current market landscape and will influence strategic choices over the next several years. First, the electrification of powertrains and the increasing use of turbocharging, direct injection, and advanced engine management systems are altering ignition demands. While traditional spark-ignition applications remain central, the functional requirements for coils are becoming more exacting in terms of thermal stability, high-voltage pulse precision, and longevity. Second, regulatory pressure is intensifying. The latest emission standards require ignition systems to contribute to emission reductions of up to 30%, pushing coil designs toward tighter timing control and more stable combustion. This is no longer a peripheral compliance issue; it is becoming a core performance parameter that affects component selection, validation cycles, and total cost of ownership. Third, supply chain fragility around critical materials is reshaping cost structures. Copper has been designated as a critical mineral, and ignition coils, which depend on high-purity copper windings, are exposed to localized supply constraints and tariff-adjusted import costs on copper articles. Together, these forces mean that competitive advantage will increasingly depend on material resilience, design efficiency, and the ability to integrate ignition components into broader electrical and emissions strategies rather than treating coils as commoditized accessories.
Key Drivers Reshaping Demand and Value Creation
Technology innovation is redefining what an ignition coil must deliver. Advanced coil-on-plug designs are gaining traction for their ability to improve combustion efficiency and support emission compliance through more precise spark delivery and reduced energy loss. In parallel, the integration of ignition components with engine management systems is becoming more sophisticated, allowing manufacturers to optimize spark timing, improve fuel efficiency, and address the operational demands of both passenger cars and commercial vehicles. This shift favors suppliers that can offer validated, high-precision solutions rather than generic replacements, especially as engines operate under more variable loads and temperatures.
Policy and regulatory environments are another powerful driver. Updated ignition system specifications, including requirements covering single-ended and other road vehicle ignition coil types, are raising the bar for consistency, durability, and emissions-related performance. At the same time, emission mandates are reshaping the value proposition of ignition components: precise timing and stable combustion are now directly tied to compliance outcomes. This creates a dual incentive for OEMs and aftermarket channels to prioritize components that not only meet baseline specifications but also support broader emissions-reduction strategies.
Demand-side behavior is evolving as well. Vehicle owners and fleet operators are increasingly sensitive to reliability, fuel economy, and service life, which influences both original equipment selection and aftermarket replacement decisions. For passenger cars, the emphasis is on performance consistency and emissions alignment; for commercial vehicles, durability under sustained duty cycles and reduced unplanned downtime are paramount. These divergent needs are nudging the market toward application-tailored solutions, where coil architectures and validation protocols are matched to specific use cases rather than treated as one-size-fits-all products.
Supply chain and cost structures are undergoing significant change. With copper flagged as a critical mineral and tariff adjustments affecting imported copper articles, the cost base for coils with copper windings and iron cores is becoming more volatile. This is prompting a focus on supply chain localization, alternative sourcing strategies, and design choices that reduce dependency on constrained inputs without compromising performance. For manufacturers, the ability to manage raw material exposure while maintaining high-purity windings and robust core construction is becoming a strategic differentiator, not just a procurement task.
Competitive Landscape: Positioning, Differentiation, and Evolution
The market displays moderate concentration, with the top three players holding roughly 48% share and the top five around 55%. This structure supports a competitive environment where scale matters, but differentiation is increasingly defined by technical capability, application coverage, and reliability credentials. Leading participants are pursuing distinct strategic positions that reflect their core strengths and target segments.
Denso Corporation continues to anchor its position as an OEM-focused supplier of high-precision ignition coils for global vehicle manufacturers, with designs aimed at improved combustion efficiency and emission compliance. This OEM-centric approach gives Denso a strong footing in programs where performance, validation, and integration with engine systems are decisive. Robert Bosch GmbH competes on a similar high-performance plane, emphasizing ignition coils integrated into vehicle electrical systems that support precise spark timing and fuel efficiency across passenger cars and commercial vehicles. Bosch’s breadth across vehicle segments positions it well to capture value from the dual demand dynamics of passenger and commercial applications.
BorgWarner Inc. brings a differentiated angle through diesel cold-start ignition coils designed for reliable engine starting and reduced emissions in heavy-duty and light-duty applications. This specialization reflects the continued importance of diesel platforms in commercial and utility segments, where cold-start reliability and emissions performance remain critical. Hitachi Ltd. contributes a powertrain-systems perspective, emphasizing durability and integration with advanced engine management, which aligns with the broader trend toward tightly coupled ignition and control architectures. Diamond Electric Mfg. Corp. supports global OEM customers with automotive ignition coils and electronic control devices, reinforcing the importance of breadth, quality consistency, and established customer relationships across major vehicle brands. Taiwan Ignition System Co., Ltd. and Niterra North America, Inc. extend the competitive field into the aftermarket, with Taiwan Ignition System delivering pencil and block coil types that meet amperage and voltage requirements under ISO 9001 and IATF 16949 certification, and Niterra offering aftermarket coils under the NGK brand with extensive VIO coverage and rigorous testing for heat, vibration, and electrical stress.
Worldwide Induction Coils Market
Aftermarket specialists are sharpening their value propositions through coverage, certification, and application-specific engineering. Standard Motor Products, Inc. and SMP Corporation emphasize full-line coverage and alignment with emission standards, supporting both OEM and aftermarket channels with engineered solutions for performance and emissions control. Nissens Automotive has been actively expanding its aftermarket presence through product launches and partnerships, including a collaboration with Standard Motor Products to add system-critical components for engine performance and emissions control to the aftermarket portfolio, and a global press event showcasing a new ignition coil range with hands-on technical sessions and racing activities to demonstrate design, testing, and manufacturing capabilities. Walker Products, Inc. focuses on ThunderSpark ignition coils engineered for precise high-voltage pulses to spark plugs, meeting OEM performance standards, while Wells Vehicle Electronics and Nissens Automotive provide broad coverage for major vehicle makes, reinforcing the aftermarket emphasis on emission compliance, engine performance, and reliable vehicle parc support.
The competitive picture is evolving along two complementary paths. One is consolidation among capable players seeking to broaden coverage, strengthen OEM and aftermarket footprints, and capture value from emissions-driven performance requirements. The other is differentiation through specialization, whether in diesel cold-start solutions, high-precision coil-on-plug architectures, or certified aftermarket coverage with rigorous testing protocols. New entrants and regional suppliers can still gain ground by focusing on underserved vehicle applications, demonstrating strong quality systems, and building resilient sourcing models that mitigate material and tariff exposure. Recent activity, such as Nissens’ product launch and partnership moves, illustrates how companies are using technical storytelling, validation transparency, and channel partnerships to elevate brand credibility and expand reach in a market where trust and performance evidence matter increasingly.
Future Outlook: Trends and Commercial Opportunities
Over the next three to five years, three trends are likely to shape where value accrues and how companies should position themselves. The first is the continued migration toward high-precision ignition architectures that support stricter emission outcomes and combustion efficiency. As emission standards push ignition systems to contribute meaningfully to reductions, coils that deliver stable, precisely timed spark events will be favored in both OEM programs and high-quality aftermarket applications. The commercial opportunity here lies in offering validated, application-matched solutions with clear performance evidence, rather than competing primarily on price in undifferentiated segments.
The second trend is supply chain realignment around critical materials and tariff sensitivity. With copper’s critical-mineral status and tariff adjustments affecting imported copper articles, companies that can demonstrate localized sourcing, inventory resilience, and design efficiency will be better placed to manage cost volatility and avoid disruption. This opens opportunities for suppliers that can combine high-purity windings with robust core construction and transparent sourcing practices, especially in regions where localization pressures are strongest. Procurement and manufacturing strategies that reduce exposure while maintaining performance will increasingly be a source of competitive advantage.
Fan Coils Market
The third trend is the widening gap between generic replacement components and engineered solutions tied to specific engine management and emissions goals. In passenger cars, demand will lean toward coils that support precise timing and fuel efficiency; in commercial vehicles, durability under demanding duty cycles will remain central. Companies that can articulate and prove these application-specific benefits—through testing, certification, and real-world validation—will capture more value than those competing solely on coverage or price. Relatedly, partnerships and channel collaborations are likely to intensify as suppliers seek to broaden reach, complement product portfolios, and strengthen aftermarket credibility. The upside is clear, but so are the risks: material cost shocks, regulatory shifts, and the potential for performance claims to be scrutinized more closely as emission expectations rise. Companies that move early to validate claims, secure supply, and align product roadmaps with emission and efficiency requirements will be better positioned to capture predictable growth.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product development with the dual demands of emission performance and supply chain resilience. This means investing in coil architectures that support precise spark timing and stable combustion, validating designs against updated ignition system specifications, and building sourcing strategies that reduce dependency on constrained copper inputs without sacrificing quality. Differentiation will come from demonstrating measurable improvements in combustion efficiency, durability, and integration with engine management systems, supported by transparent testing and certification. Portfolio decisions should reflect application-specific needs across passenger and commercial vehicles, with clear roadmaps for coil-on-plug and specialized diesel solutions where relevant.
For investors, the market offers steady growth with value migration toward technically differentiated and supply-resilient players. Evaluating opportunities should focus on companies with strong validation credentials, broad and expanding VIO or vehicle coverage, credible OEM or high-quality aftermarket positions, and evidence of proactive material and tariff risk management. Specialization in segments such as diesel cold-start reliability, high-precision coil-on-plug designs, or certified aftermarket coverage can provide defensible niches. Investors should also watch for partnership activity and channel expansion as indicators of competitive momentum, while remaining mindful of regulatory and raw-material volatility that can affect margins and timelines.
PW Consulting
For procurement and sourcing leaders, the focus should be on balancing coverage, performance, and resilience. This includes qualifying suppliers with recognized quality systems and rigorous testing for heat, vibration, and electrical stress, verifying alignment with updated ignition specifications and emission-related performance expectations, and assessing sourcing footprints for exposure to copper constraints and tariff-adjusted imports. Diversification across capable suppliers, clear acceptance criteria for performance and durability, and visibility into material sourcing can reduce disruption risk while maintaining compliance and reliability objectives. As emission standards raise the bar for ignition performance, procurement decisions should increasingly weigh total value—compliance support, service life, and integration compatibility—alongside unit cost.
For decision makers seeking deeper segmentation data, regional dynamics, and customized strategic recommendations, the full research report provides a more detailed breakdown of market sizing paths, application-specific demand patterns, and competitive moves across the forecast period. The breadth of data and the granularity of company and segment analysis can support more precise planning for product roadmaps, sourcing strategies, and investment prioritization in a market where performance, compliance, and supply resilience are converging as the defining drivers of long-term value.
For detailed analysis of this topic, please visit the official page: Ignition Coil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


