



PW Consulting Voluntary Carbon Offsets: The Real Drivers Behind 30.7% CAGR Growth

The Voluntary Carbon Offsets Market: Strategic Trends and Commercial Opportunities in a Rapidly Evolving Landscape
The voluntary carbon offsets market has entered a phase of structural transformation that demands attention from executives, strategists, and investors. After a period of volatility, the sector is expanding at a compound annual growth rate of 30.7 percent between 2026 and 2032, with revenue projected to reach approximately 13.56 billion USD by 2032. The trajectory is not merely a continuation of recent growth; it reflects a recalibration of how companies approach decarbonization beyond their own operations, how project developers structure supply, and how standards bodies and regulators attempt to harmonize credibility. The market's total size stood at roughly 2.1 billion USD in 2025, a figure that underscores both the scale of momentum and the distance still to travel before voluntary offsets become a routine component of corporate climate strategy. For decision-makers, the opportunity lies not in treating this as a commodity play but in understanding the mechanics of integrity, segmentation, and timing that will separate durable value creation from speculative exposure.
Carbon Financial Service (CFS) Market
Market Reality and Core Challenges
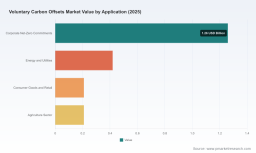
At a high level, the market's expansion is anchored by a growing recognition that emissions reduction alone is insufficient for organizations with net-zero ambitions. Corporate demand for voluntary credits has become the largest application segment, reflecting a broad commitment to neutralize residual emissions and support supply chain decarbonization. Parallel demand from energy and utilities, consumer goods and retail, and agriculture illustrates how the market is spreading across value chains with distinct risk profiles and performance requirements. The regional distribution of activity is similarly broad, with North America representing the largest share, followed by Europe, Asia Pacific, Latin America, and the Middle East and Africa, each bringing different regulatory expectations, project pipelines, and buyer maturity. Market concentration remains relatively low, with the top three and top five firms holding modest combined shares, indicating that scale advantages are still forming and that fragmentation persists across project origination, verification, and distribution.
Yet the expansion narrative is shadowed by challenges that define the current turning point. The first is the persistent tension between price signaling and perceived quality. Nature-based credits typically trade in a low single-digit dollar range per tonne, while technology-based carbon dioxide removal credits can exceed 170 dollars per tonne, creating a pricing landscape that forces buyers to make difficult trade-offs between volume, durability, and additionality. This spread is not an anomaly; it is the market's way of differentiating project types under constrained supply of high-integrity options. Companies that treat price as the only variable risk overpaying for low-confidence claims or under-investing in credits that align with their disclosure expectations.
Carbon Offset/Carbon Credit Trading Service Market
The second challenge centers on the credibility infrastructure itself. The Integrity Council for the Voluntary Carbon Market has established Core Carbon Principles as a global benchmark, and certification programs and methodologies have been assessed against these principles, with some REDD+ methodologies and broader program frameworks receiving approval. At the same time, implementing regulations are raising transparency requirements for certification schemes, and new methodologies are being introduced to address long-standing quality concerns. This is progress, but it also means that the definition of a reliable credit is being rewritten in real time. Buyers and sellers are navigating a moving target, and the cost of misalignment is rising as auditors, regulators, and stakeholders demand clearer provenance and more robust impact evidence.
The third challenge is the strategic uncertainty around how voluntary credits should be used in relation to internal decarbonization and Scope 3 emissions. Organizations are still forming their own doctrines about when an offset qualifies as a bridging tool rather than a substitute for operational change, and how much reliance on external credits is appropriate in supply chain engagement. Until these postures stabilize, demand can be lumpy and project pipelines can misprice risk, particularly for removal credits that require longer lead times and higher capital intensity. The result is a market that is simultaneously scaling and questioning its own foundations, a combination that creates both opportunity and caution.
Key Drivers Shaping the Market
Technology innovation and the maturation of carbon dioxide removal options are reshaping supply dynamics. Advances in monitoring, verification, and digital documentation are lowering the friction of project development and improving the traceability of impact, while new removal pathways are expanding the range of durable credits available. These developments matter because they influence both the cost curve and the confidence curve. Where historical supply relied heavily on avoidance and reduction projects, there is now growing emphasis on removal projects that offer longer-lived storage and stronger alignment with net-zero framing. The shift is not a replacement but a rebalancing, and it has implications for procurement planning, capital allocation, and reporting architecture. Companies that understand which technologies are moving from pilot to commercial viability can anticipate where premium pricing will persist and where competitive pressure will compress margins.
Policy and regulatory activity is reinforcing this rebalancing by setting clearer expectations for what qualifies as high-integrity and how claims should be substantiated. Recent framework adoptions and implementing regulations in major markets have begun to standardize transparency and certification requirements, while coalitions and standard-setting bodies have introduced jurisdictional approaches and corporate supply chain instruments designed to channel voluntary credit use toward credible outcomes. For example, efforts to advance jurisdictional REDD+ and the introduction of new REDD+ methodologies respond directly to concerns about baseline integrity and additionality, and the anticipation of corporate scope 3 standards signals that buyers will need to integrate credits into a more rigorous decarbonization narrative. The practical implication is that policy is no longer a peripheral risk; it is becoming a design constraint for project portfolios and procurement strategies. Organizations that embed regulatory trajectory into their scenario planning can avoid stranded claims and better align with credible benchmarks.
Demand-side behavior is changing in ways that go beyond volume growth. Consumers and corporate buyers are increasingly sensitive to the provenance of the credits they purchase, the co-benefits associated with project types, and the degree to which offsets support broader transition goals. This behavioral shift is pushing distributors and developers to differentiate on narrative and evidence rather than on volume alone. It is also encouraging more tailored engagement across sectors, where the motivations of a consumer-facing brand differ from those of an energy provider or an agricultural producer. The lesson for decision-makers is that segmentation is becoming the basis for competitive advantage: the same credit may command different justification in different contexts, and the most effective procurement strategies are those that match credit selection to organizational risk tolerance, stakeholder expectations, and disclosure architecture.
Cost structures across the supply chain are also evolving. As verification practices tighten and project developers respond to quality benchmarks, transaction costs and due diligence requirements are rising, particularly for removal and jurisdictional projects. At the same time, improved tooling and data availability are beginning to reduce the burden of screening and monitoring. The net effect is a market in which the cost of access is climbing for low-quality supply but easing for credible supply that can be documented efficiently. Companies that invest early in robust sourcing processes and clear internal criteria are likely to secure more stable relationships and better terms over time, while those that rely on ad hoc purchasing risk exposure to price volatility and reputational uncertainty.
Competitive Landscape and Leading Strategies
The competitive field includes a range of firms with distinct operating models, from consultative providers that bundle credit access with sustainability strategy services to developers and sellers that emphasize integrity and project selection. Some organizations focus on high-integrity project portfolios and transparency, while others concentrate on renewable energy, energy efficiency, or conservation forestry initiatives. A number of players operate as project sourcing and brokerage entities, offering flexibility in procurement, and others manage and certify projects globally, leveraging geographic breadth and verification relationships. This diversity reflects the market's early-stage structure, where differentiation is often built on reputation, methodology expertise, and the ability to connect buyers with projects that meet specific requirements.
Leading firms are typically positioning around one or more of the following advantages. One is trust and verification, where organizations build credibility by aligning with recognized standards and emphasizing transparency in methodology selection and impact documentation. Another is vertical specialization, where firms focus on project types or sectors that match their expertise and buyer demand, such as nature-based conservation or technology-based removal, allowing them to develop deeper technical capability and more consistent quality. A third advantage is service integration, where credits are offered alongside advisory support, measurement, and reporting assistance, helping customers navigate the complexity of using offsets responsibly. These strategic stances matter because the market is rewarding firms that reduce uncertainty for buyers, not simply those that aggregate volume. In a landscape where quality differentiation is increasingly central, the winners are likely to be those that can combine credible supply with clear guidance and reliable execution.
The market structure is evolving toward selective consolidation and parallel differentiation. On one hand, larger players are expanding their capabilities across origination, verification support, and distribution to capture scale benefits and reduce transaction friction. On the other hand, specialized entrants are targeting niches that require particular expertise, such as jurisdictional approaches, removal technology, or sector-specific procurement programs. New entrants are also emerging as standards, methodologies, and regulatory expectations create fresh requirements that incumbents may not fully address. This combination suggests a market that will continue to fragment in the short run as different needs are served by different models, but that may consolidate over time as buyers prefer fewer, more reliable relationships and as scale benefits in due diligence and data management become more pronounced. For participants, the implication is to monitor not only who grows, but where capabilities are being built and where quality assurance is most valued by buyers.
Forward Outlook: Trends and Commercial Opportunities
The first major trend over the next three to five years is a shift toward higher-integrity credits and a premium on removal and jurisdictional projects that can demonstrate durable impact and clear additionality. As corporate buyers refine their use of voluntary credits and regulators encourage greater transparency, demand is likely to tilt toward credits that withstand scrutiny, even if they carry higher costs. The commercial opportunity for companies is to build procurement strategies that treat integrity as a design parameter rather than an afterthought, securing access to credible supply early and structuring internal criteria to avoid reliance on credits that may become difficult to defend. This also creates value for developers and intermediaries that can document impact efficiently and align with evolving benchmarks, as the market is likely to reward those who can reduce uncertainty at scale.
A second trend is the integration of voluntary credits into broader supply chain decarbonization and corporate transition narratives. As scope 3 engagement matures and new corporate programs are anticipated, credits will increasingly be used as part of a coordinated approach that combines supplier engagement, internal reduction, and selective offsetting. The opportunity here lies in matching credit selection to the specific requirements of value chain partners, designing programs that support credible claims, and preparing reporting architectures that can accommodate evolving standards. Companies that treat this as a cross-functional effort, rather than a procurement transaction, are better positioned to use credits as a strategic lever rather than a compliance exercise.
The third trend is the gradual standardization of quality assessment and transparency, driven by benchmark principles, regulatory transparency requirements, and methodological innovation. While full harmonization remains a distant goal, the direction is clear: assessment will become more structured, claims will need stronger documentation, and differentiation between project types will be more explicit. The opportunity is for organizations to build internal competence in evaluating quality, to align with credible benchmarks, and to communicate choices clearly to stakeholders. The risk is that those who delay assessment capabilities may face higher transaction costs, limited access to preferred supply, or pressure to retrofit claims that no longer meet expectations. Uncertainty will persist because standards will continue to evolve and because project performance can vary, but the trajectory favors structured, evidence-based procurement over opportunistic buying.
Strategic Recommendations for Decision-Makers
For manufacturers and industrial operators with net-zero commitments, the priority is to define a clear doctrine for how voluntary credits complement internal reduction and supplier engagement. This means establishing criteria for credit type, quality thresholds, and acceptable use cases, then integrating these criteria into procurement and reporting processes. The practical benefit is reduced risk of rework, stronger alignment with stakeholder expectations, and better positioning as standards mature. A second step is to develop supplier-facing programs that use credits as part of a broader engagement model, especially where scope 3 influence is meaningful. Companies that combine credit selection with data collection and joint improvement plans can use voluntary markets to accelerate transition rather than simply offset residual emissions.
For investors and capital allocators, the strategic focus should be on identifying where value is being created through credibility, scale, and service integration rather than volume alone. Projects and platforms that can demonstrate robust documentation, align with recognized benchmarks, and reduce due diligence friction are likely to have stronger long-term economics. Equally important is attention to risk, since the market's growth depends on continued regulatory clarity and sustained buyer confidence. Diversification across project types and geographies, combined with disciplined underwriting of quality and execution, can help manage the inherent uncertainty while preserving exposure to structural demand.
For purchasers and procurement teams, the most valuable posture is disciplined sourcing supported by internal expertise. This includes building a curated supplier base, defining due diligence checklists aligned with quality benchmarks, and planning for the cost and lead time associated with higher-integrity credits, particularly removal projects. It also means preparing communication strategies that explain why certain credits are selected and how they fit into the broader decarbonization plan. The payoff is more resilient procurement, clearer stakeholder narratives, and greater flexibility as standards and availability evolve. For organizations seeking deeper segmentation data and tailored recommendations for specific sectors, geographies, and procurement models, the full research report provides a more detailed view of market structure, project trends, and strategic options.
The voluntary carbon offsets market is no longer a niche experiment. Its growth rate, expanding application base, and evolving integrity framework make it a meaningful component of climate strategy for many organizations. The businesses that will benefit most are those that treat the market as a system to be understood and managed, not as a simple marketplace for credits. By aligning procurement with credible quality signals, preparing for more structured standards, and integrating offsets into broader decarbonization and supply chain strategy, leaders can convert a complex and fast-moving sector into a durable source of strategic advantage.
PW Consulting
For detailed analysis of this topic, please visit the official page: Voluntary Carbon Offsets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


