



Laser Rangefinder Market 2026: Why 8.85% CAGR Signals Major Shifts

The Laser Rangefinder Market: Strategic Trends and Commercial Opportunities Through 2032
The laser rangefinder market has evolved from a specialized instrumentation niche into a strategically critical sector spanning defense modernization, precision engineering, and autonomous systems. Between 2020 and 2025, global revenue expanded from approximately 218.0 million USD to 328.0 million USD, reflecting a compound annual growth rate of 8.85 percent projected through 2032. By the end of the forecast period, market value is expected to surpass 580.0 million USD. This trajectory is not merely a function of incremental demand growth; it signals a structural shift in how ranging technology is embedded across platforms, industries, and operational workflows. For executives and investors evaluating exposure to this space, the period ahead will reward those who understand not just where the market is growing, but why certain segments are accelerating, how competitive positioning is reshaping, and which capabilities will separate leaders from followers.
PW Consulting
Market Landscape and Core Challenges
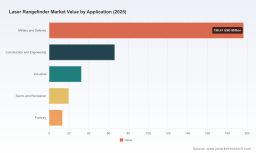
The current market structure reflects both maturity in established applications and rapid experimentation in emerging ones. Hand-held laser rangefinder products continue to represent the larger revenue share, driven by widespread adoption in surveying, forestry, sports, and field engineering. Telescope laser rangefinder solutions, while smaller in absolute terms, carry disproportionate strategic weight due to their integration into defense fire-control systems, aerospace platforms, and high-precision industrial metrology. The application mix similarly reveals a dual dynamic: military and defense remains the dominant demand driver, but construction and engineering, industrial automation, sports and recreation, and forestry collectively represent a growing base of commercial users who increasingly demand compact, eye-safe, and connected ranging solutions.
Despite the favorable top-line trajectory, the industry faces several structural challenges that will shape competition and investment returns over the next few years.
Technological Convergence and Integration Complexity
Ranging technology is no longer evaluated in isolation. Customers now expect laser rangefinder modules to interoperate seamlessly with cameras, inertial measurement units, LiDAR arrays, and edge-processing pipelines. This integration demands tighter mechanical packaging, thermal management, software-defined calibration, and robust communication protocols. Suppliers that treat ranging as a standalone component risk losing relevance to vendors offering validated subsystem solutions. The challenge for manufacturers is balancing modular flexibility with platform-specific optimization without inflating development cycles or compromising reliability.
Regulatory and Safety Pressures
Eye-safety requirements, spectral regulations, and export control frameworks continue to shape product design and market access. Eye-safe wavelengths around 1.54 µm and 1.535 µm have become standard expectations for defense, aerospace, and many commercial applications, pushing suppliers to invest in erbium-glass and related gain media. Simultaneously, regional certification regimes for construction and industrial equipment add compliance overhead. Companies that proactively design to these constraints early in the development cycle gain a meaningful time-to-market advantage, while those that treat compliance as an afterthought face rework costs and delayed deployments.
Supply Chain Sensitivity and Cost Structure Variability
The market operates with a moderately concentrated competitive structure, where the top three players account for roughly 29.6 percent of revenue and the top five reach approximately 38.2 percent. This concentration does not imply a uniform cost environment. Component availability, semiconductor bottlenecks, precision optics sourcing, and specialized assembly capabilities can create regional cost asymmetries. Suppliers reliant on single-source subassemblies face margin volatility when demand spikes or when geopolitical factors disrupt logistics. As a result, resilience in supplier networks and disciplined design-for-manufacturability have become strategic differentiators rather than back-office concerns.
Key Drivers Shaping Market Growth
The 8.85 percent compound annual growth rate through 2032 is not a generic forecast; it reflects the interaction of several reinforcing drivers. Understanding these drivers helps decision-makers separate temporary demand spikes from durable secular trends.
Defense Modernization and Multi-Domain Integration
Military and defense demand continues to anchor market growth. Modern air defense, ground vehicle fire control, naval combat systems, and unmanned aerial platforms require accurate, low-latency ranging that can operate in contested environments and under stringent size, weight, and power constraints. Recent contract activity illustrates how defense procurement is converting into sustained module and system orders. In March 2025, Lumibird secured orders from Rheinmetall Air Defense to supply VIDAR laser rangefinders for Skyranger 30 short-range air defense integration, with deliveries scheduled through 2028. A month later, the company announced a contract from Saab AB for OdiPro laser rangefinders supporting Swedish and Danish armed forces CV90 platforms. By June 2025, Lumibird had also received a contract from Saab for 57 VIDAR laser rangefinders for Danish Navy frigates, with deliveries planned across 2025 and 2026. These awards highlight a recurring pattern: defense customers are locking in multi-year supply commitments for ranging modules that will be embedded in platform lifecycles lasting well beyond the initial delivery window.
For commercial strategists, the implication is clear. Defense-driven revenue tends to be less cyclical than spot-market commercial demand, but it also demands rigorous qualification, traceability, and integration support. Companies that build repeatable qualification pathways and maintain configurable module architectures can capture platform programs without sacrificing agility.
Miniaturization and Autonomy-Ready Form Factors
A second powerful driver is the push toward ultralight, low-SWaP ranging modules suitable for drones, gimbals, robotics, and mobile autonomy. As payloads shrink and mission profiles diversify, the value of a ranging module is no longer defined solely by maximum distance; it is increasingly measured by its contribution to stabilization, obstacle detection, target tracking, and sensor fusion. LightWare LiDAR introduced the GRF-500 laser rangefinder module in March 2025, extending gimbal range to 500 meters for drone and autonomy applications. Analog Modules, Inc. followed in September 2024 with the miniaturized Model 7552A-04 laser rangefinder receiver/range processor designed for high-performance tactical applications. In December 2025, Safran Vectronix released the LRF 3019 compact laser rangefinder module targeting advanced drone tracking and multi-sensor applications. Together, these releases show a market moving toward rangefinder solutions that are not only smaller but also more purpose-built for embedded perception and tracking.
This trend expands the addressable market beyond traditional handheld and tripod-based use cases. It also raises the performance bar: modules must maintain accuracy and repeatability while operating under vibration, variable temperature, and limited power budgets. Suppliers that can deliver validated SWaP-optimized modules with clear integration documentation will find themselves positioned at the intersection of multiple growth vectors.
Commercial Productivity Demands and Field Instrumentation
Demand-side changes in construction, engineering, forestry, and industrial operations are also reshaping purchasing behavior. Field teams increasingly prioritize reflectorless measurement, faster data capture, and compatibility with digital workflows such as BIM, GIS, and automated inventory systems. Laser Technology, Inc. has long served these professional measurement segments with reflectorless laser rangefinders in its TruPulse series for surveying, forestry, construction, and government applications. Meanwhile, companies such as ERDI TECH LTD and JIOptics have expanded offerings around eye-safe 1535 nm modules and long-range instruments spanning commercial, military, and professional use cases up to 15 kilometers. The broader message is that commercial buyers are no longer comparing products on distance alone; they are evaluating total workflow value, including calibration stability, data output formats, durability, and integration with existing field software.
As commercial operators face pressure to reduce rework, accelerate surveying cycles, and improve asset visibility, ranging instruments that reduce human error and speed data handover will gain preference. This creates room for vendors that invest in user experience, ruggedization, and ecosystem compatibility alongside core ranging performance.
Supply-Side Dynamics and Regional Capability Shifts
Cost structures and manufacturing footprints are evolving as regional capability clusters mature. Established European and North American suppliers continue to strengthen high-end defense and aerospace positions, while select Asian manufacturers have expanded into both professional and consumer-oriented segments with competitive pricing and rapid product iteration. Shenzhen Laser Explore Tech. Co., Ltd. reflects this broader pattern, producing eye-safe and standard laser rangefinders, riflescopes, and night-vision solutions for hunting, golf, and outdoor applications. JIOptics, with long-range laser rangefinders up to 15 kilometers for commercial, military, and professional use, further illustrates how volume-oriented and performance-oriented lines are being developed in parallel.
The strategic implication is that the market is not bifurcating into premium versus commodity in a simple way. Instead, different customer segments are developing distinct requirement sets, and suppliers are responding with portfolio breadth. Companies that can manage multiple quality tiers, maintain separate design and production pathways, and protect intellectual property in high-value modules will be better positioned to serve both defense programs and commercial volume markets without cross-contaminating brand expectations or margin structures.
Competitive Landscape and Leading Strategies
The competitive field combines established defense and optics specialists with agile module developers and volume-focused manufacturers. No single company dominates the entire value chain, and leadership is increasingly defined by segment focus, integration depth, and program execution rather than by a single flagship product.
Differentiated Positioning Among Leading Players
JENOPTIK AG has built a profile around compact solid-state and diode-pumped laser rangefinder modules, including ELEM series options reaching up to 60 kilometers with eye-safe 1.54 µm Erbium:glass technology for military vehicle and fire-control integration as well as industrial metrology. Its emphasis on module-level design positions the company as a supplier that can be embedded into broader system architectures. Safran Electronics & Defence, through its Ultisense offerings, provides both integrated laser rangefinder modules and full systems for military and aerospace applications, reflecting a strategy that spans component and system-level value. This dual capability can reduce integration risk for platform customers who prefer single-source responsibility for critical subsystems.
LightWare LiDAR has carved out a distinctive position in ultralight microLiDAR sensors and rangefinder modules, with GRF and SF series products optimized for drone gimbals, autonomy, robotics, and industrial sensing. This focus on small, weight-sensitive platforms differentiates the company from traditional surveying and defense vendors and aligns it closely with the miniaturization and autonomy trends described earlier. Attollo Engineering similarly targets the low-SWaP segment with the WASP™-200 series, designed for defense UAVs, gimbals, and handheld systems, reinforcing how several suppliers are converging on embedded, weight-conscious ranging for mobility platforms.
On the commercial professional side, Laser Technology, Inc. continues to differentiate through reflectorless measurement capabilities for field professionals, while ERDI TECH LTD and JIOptics extend the competitive field with eye-safe module options and long-range instruments that serve mixed commercial and professional demand. Analog Modules, Inc. contributes a tactical-leaning, miniaturized receiver and range processor portfolio for moving-target and long-range applications, demonstrating that specialized signal-processing and receiver designs remain important for demanding use cases. Lumibird’s recent defense contracts and module portfolio, including OdiPro and VIDAR series products, underscore the ongoing importance of platform integration, multi-year program execution, and demonstrated performance in air defense, naval, and ground vehicle contexts.
Evolving Market Structure: Consolidation, Segmentation, and New Entrants
The competitive landscape is likely to evolve along three parallel tracks. First, selective consolidation and partnership activity may increase as platform customers seek reduced integration complexity and suppliers aim to bundle modules with sensors, processing, or software support. Second, segmentation will deepen as the requirements of defense platforms, industrial automation, and consumer-adjacent applications diverge further, making a single product architecture insufficient for capturing the full market. Third, new entrants and adjacent technology providers—particularly those coming from drone autonomy, robotics perception, and smart instrumentation—will continue to test incumbents on form factor, price, and ease of integration.
In this environment, competitive advantage is less about claiming the longest range in isolation and more about proving reliability, interoperability, and total cost of ownership within a specific platform or workflow. Companies that publish clear integration guidelines, support qualification processes, and maintain predictable supply timelines will earn preference even when their headline specifications are not the absolute maximum on the market.
Golf GPS Market
Future Outlook: Three Trends Defining the Next Three to Five Years
Embedded Ranging as a Standard Subsystem
Over the next few years, laser rangefinder modules are likely to become less visible as standalone products and more embedded as standard subsystems within larger platforms. In defense, this means deeper integration with fire control, target tracking, and multi-sensor fusion. In commercial autonomy and robotics, it means ranging becoming part of the basic perception stack rather than a specialized add-on. The commercial opportunity here lies in designing modules that anticipate integration early: standardized mechanical interfaces, robust calibration procedures, and software-friendly data outputs. Suppliers that treat integration as a product feature rather than a service add-on will capture more platform-level engagements.
Eye-Safe, Multi-Wavelength, and Application-Tuned Designs
Eye-safety and wavelength selection will continue to influence product roadmaps, but the future is not one-wavelength-fits-all. Different applications will optimize for different trade-offs among range, eye safety, atmospheric performance, detector cost, and regulatory acceptance. The strategic opportunity is to develop application-tuned variants rather than a single universal design. This includes scalable module families that share core architecture while allowing wavelength, optics, and processing choices tailored to specific operational profiles. Companies that manage this portfolio complexity efficiently will be able to serve both regulated defense contexts and commercial environments without diluting focus.
Workflow Integration and Total Value Selling
As commercial and professional buyers become more sophisticated, purchasing decisions will increasingly weigh workflow compatibility, data usability, and durability alongside raw ranging performance. This shift opens the door for value selling that emphasizes reduced measurement time, fewer repeat visits, better data handoff to digital systems, and lower training burden. The risk for suppliers that compete only on specifications is margin erosion from price-based comparisons. The opportunity for those that demonstrate measurable operational improvements is stronger pricing power and longer customer relationships. Decision-makers should expect this trend to accelerate as digital construction, precision forestry, and automated inspection become more widespread.
Risks and Uncertainties to Monitor
Several uncertainties could affect the pace and distribution of growth. Export control and procurement policy shifts may alter the timing of defense program awards or redirect demand toward local sourcing requirements. Component supply disruptions can compress margins or delay deliveries, especially for modules dependent on specialized optics, detectors, or precision assembly. Competitive entry from adjacent technology spaces may compress differentiation in certain price-sensitive segments. Finally, if macroeconomic conditions slow capital investment in construction, industrial modernization, or platform procurement, near-term demand could diverge from long-term structural trends. These risks do not negate the growth outlook, but they reinforce the importance of portfolio balance, supply resilience, and program diversification.
Laser Distance Measuring Devices Market
Strategic Actions for Decision-Makers
The market’s trajectory creates distinct implications depending on a reader’s role. The following actions are intended to translate market dynamics into practical next steps.
For Manufacturers and Component Suppliers
Prioritize modular architectures that can be configured for multiple platforms without full redesigns, and invest in qualification pathways that reduce cycle time for defense and professional customers. Align product roadmaps with application-specific requirements rather than chasing a single maximum-range headline. Strengthen documentation, calibration support, and integration guidance so that the module becomes easier to adopt within larger systems. Where volume commercial segments are targeted, separate design, quality, and production pathways from high-end defense lines to protect margin and brand positioning.
For Investors and Corporate Development Teams
Evaluate exposure not just by product category but by end-use resilience and program visibility. Defense-linked module and system positions can offer multi-year revenue visibility, but they require disciplined execution and compliance readiness. Commercial segments tied to productivity workflows, autonomy, and field instrumentation can offer faster iteration and broader addressability, but they demand strong user experience and ecosystem fit. Consider the value of suppliers that can operate across quality tiers or that hold differentiated capabilities in SWaP optimization, eye-safe wavelengths, or signal processing, as these attributes are likely to command disproportionate relevance as platforms become more integrated.
For Procurement and Platform Integration Teams
Shift evaluation criteria beyond distance and price toward total system fit. Assess eye-safety compliance, environmental ruggedness, calibration stability, data output compatibility, and supplier support for qualification and integration. Where possible, validate modules within representative workflows or platform conditions before committing to multi-unit deployments. For long-lived platforms, negotiate supply continuity and obsolescence management as part of the procurement framework, because ranging subsystems often need to remain available and supported across the platform lifecycle.
Why Deeper Intelligence Matters Now
The laser rangefinder market is large enough to matter and dynamic enough to reward targeted strategy. Aggregate growth figures point to a steadily expanding opportunity, but the real strategic value lies in understanding how demand is distributed across applications, how module requirements are changing under SWaP and safety constraints, and how competitive positioning is being reshaped by integration depth and program execution. The difference between a generic growth narrative and an actionable strategy is detail: segment-level demand trajectories, regional capability shifts, qualification requirements, and supplier capability mapping.
For executives and investors who need to move from market awareness to investment and operating decisions, a more granular view of subsegments, pricing dynamics, demand intensity by application, and company-level capability profiles can significantly reduce uncertainty. PW Consulting’s broader research on this market provides that deeper segmentation, forecast detail, and competitive benchmarking to support planning across manufacturing, investment, and procurement contexts.
The next phase of growth in laser ranging will belong to organizations that treat accuracy, integration, and workflow value as a single design problem rather than a set of separate specifications. Those who align product strategy, supply resilience, and customer support with that reality will be best positioned as the market moves from 2025 toward 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Laser Rangefinder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


