



DMC Market 2026: Why 8.1% CAGR Signals a Battery-Grade Structural Shift

Strategic Shifts and Commercial Opportunities in the Dimethyl Carbonate Market: 2025–2032
Market Landscape and Structural Challenges
The dimethyl carbonate (DMC) market has matured from a niche solvent and chemical intermediate into a strategically positioned segment driven by parallel growth in polymers, energy storage, and green chemistry. Between 2020 and 2025, the market expanded steadily from approximately 1,120 million USD to 1,676 million USD, reflecting an accelerated adoption curve across multiple end-use sectors. Projections for the 2026–2032 window point to a compound annual growth rate of 8.1%, with the market expected to reach roughly 2,896 million USD by the end of the forecast period. This trajectory is not merely a function of volume growth; it reflects a structural repositioning of DMC as a cross-sector enabler, where the same molecule serves distinct value propositions depending on the grade, application, and regional regulatory context.
Yet the market's momentum is accompanied by structural friction points that will define competitive positioning over the next several years. First, the DMC value chain remains moderately fragmented, with the top three players capturing roughly a quarter of total revenue and the top five accounting for about a third. This concentration level indicates room for consolidation, but also suggests that scale advantages are not yet fully decisive. Companies are competing across different grade segments and geographies, which complicates direct comparison and rewards players who can align production capabilities with specific customer requirements rather than those who compete solely on volume.
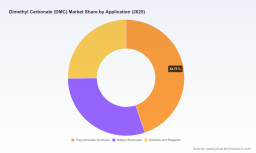
Second, the market sits at the intersection of multiple demand drivers that do not always pull in the same direction. Polycarbonate synthesis, battery electrolyte formulations, and solvents/reagents applications each impose different purity, consistency, and logistical requirements. Industrial-grade volumes tend to prioritize cost efficiency and broad availability, while battery-grade and pharmaceutical-grade DMC require tighter specifications, more rigorous quality control, and often distinct supply relationships. This divergence creates operational complexity for producers who must manage multiple product lines without allowing one segment to cannibalize investment in another.
Third, regional dynamics are reshaping the competitive map. Asia Pacific represents the largest market footprint, reflecting both manufacturing intensity and end-use demand concentration, while North America and Europe maintain significant but smaller shares. Latin America and the Middle East/Africa regions account for comparatively smaller portions of the market today, yet their relevance can shift quickly when trade policy, logistics costs, or localized production decisions change. The market's geographic distribution is not static; it responds to capacity siting decisions, import/export classifications, and the timing of downstream demand buildouts.
For executives, this landscape signals that DMC is no longer a commodity with a single pricing logic. Strategic value comes from aligning grade capabilities, regional presence, and application-specific service models with where end-demand is actually tightening or expanding.
Key Drivers Reshaping Demand and Supply
Technology Innovation and Grade Specialization
One of the most consequential developments in the DMC market is the widening gap between industrial and high-purity grades. Battery-grade DMC, in particular, has emerged as a critical input for lithium-ion electrolyte formulations, where moisture control, impurity thresholds, and batch consistency directly affect cell performance and manufacturing yield. The same molecule used as a solvent or reagent in pharmaceutical and fine-chemical synthesis also requires high-purity handling, but the specification drivers differ: battery applications emphasize electrochemical compatibility and large-scale repeatability, while pharmaceutical use cases emphasize residue limits, traceability, and regulatory documentation.
Technological progress is therefore not just about producing more DMC; it is about widening the range of grades that can be reliably delivered at scale. Transesterification and oxidative carbonylation routes continue to underpin much of the production landscape, but the operational differentiator has shifted toward purification, quality assurance, and the ability to serve tightly specified customers without sacrificing throughput. Producers that can connect process control with customer qualification processes are gaining an advantage that is not visible in headline volume figures but matters heavily in procurement decisions.
Policy and Regulatory Environment
Regulatory classification and environmental policy are increasingly shaping where and how DMC is adopted. In multiple jurisdictions, DMC is positioned as a lower-toxicity alternative to more hazardous solvents, and this framing creates a steady tailwind for substitution in coatings, cleaning formulations, and certain synthesis pathways. The U.S. EPA's continued emphasis on low-toxicity green alternatives under Clean Air Act classifications reinforces a broader narrative: DMC benefits from being part of the regulatory answer to solvent risk reduction, not just a chemical with favorable performance attributes.
Trade and customs classification decisions also influence market flow. A notable example occurred in mid-2025, when U.S. Customs and Border Protection issued a ruling involving DMC imports from Saudi Arabia. Such determinations may appear procedural, but they can alter sourcing strategies, lead to re-routing of supply, and affect the relative attractiveness of different origin points. In a market where regional availability, freight costs, and import status intersect, regulatory clarity can be as commercially important as raw material pricing.
Lithium Batter Ethylene Carbonate Market
Demand-Side Transformation in Energy Storage and Polymers
The battery sector is a central pillar of near-term DMC demand. As lithium-ion battery manufacturing scales and electrolyte formulations continue to evolve, the need for consistent battery-grade carbonate solvents has grown alongside cell production. This is not a single-technology bet; it is a broader alignment between energy storage deployment, electric mobility, and stationary storage buildouts that increases the addressable base for electrolyte-related DMC. At the same time, polycarbonate synthesis remains a substantial application area, supported by durable demand in engineering plastics and related specialty applications. The dual pull from energy storage and polymer manufacturing gives DMC a diversified demand profile that can buffer the market against downturns in any single sector.
Importantly, demand-side growth is not uniform across customers. Large battery and polymer buyers increasingly evaluate suppliers on reliability, specification consistency, and the ability to support qualification cycles. In practice, this means that commercial access to DMC is becoming more relationship- and capability-driven than price-only, especially in the higher-grade segments.
Dimethyl Terephthalate (DMT) Market
Supply Chain Volatility and Cost Structure Sensitivity
Raw material dynamics remain a persistent pressure point. Methanol pricing, in particular, has shown sharp movements that directly affect DMC production economics. In early 2026, methanol prices in China moved above 400 USD per ton, rising more than 40% from early March levels amid geopolitical tension and supply disruptions. Northeast Asia pricing also firmed, with China FOB levels reaching roughly 425 USD per metric ton and India FOB levels climbing toward 807 USD per metric ton, reflecting tighter Middle East supply conditions. These movements illustrate how quickly cost structures can shift when feedstock availability is disrupted.
For DMC producers and buyers alike, the implication is that cost management cannot rely on static assumptions. Procurement planning, inventory positioning, and contract structures need to account for volatility in methanol and related logistics inputs. On the production side, companies with flexible feedstock strategies, integrated operations, or strong regional supply relationships are better positioned to absorb shocks without compromising grade reliability.
Competitive Landscape and Leading Strategies
The DMC competitive set is shaped by a mix of established chemical manufacturers and specialty players, many with strong positions in Asia and Japan, alongside Western suppliers focused on high-purity and application-specific offerings. Several themes define how the leading companies are positioning themselves.
Japanese producers, such as UBE Corporation, Kowa Company, and Kishida Chemical, illustrate a strategy rooted in grade breadth, process maturity, and targeted capacity deployment. UBE's focus on both DMC and ethyl methyl carbonate, including battery-grade material for lithium-ion electrolytes, reflects an effort to serve the energy storage chain directly. The company's presence across multiple geographies, including U.S. and European operations, shows an intent to align production footprint with regional demand rather than rely solely on export-oriented volume. Kowa and Kishida Chemical, meanwhile, emphasize industrial, pharmaceutical, and high-purity applications, suggesting a playbook that prioritizes specification control and customer-specific grades over undifferentiated scale.
Lotte Chemical represents a different but overlapping logic: DMC is positioned both as a monomer for polycarbonates and as a specialty chemical input, with production located in Korea to serve regional industrial demand. This dual-use orientation allows the company to capture value across polymer and specialty channels, provided it can manage the operational requirements of each. In the specialty space, Tokyo Chemical Industry and Merck KGaA highlight the importance of purity and application support. Merck's pharmaceutical and chemical synthesis positioning, including battery-electrolyte grade options, underscores how high-purity DMC can be sold into multiple premium segments when supported by the right documentation and quality systems. TCI's focus on research and industrial grades with high-purity offerings shows that even smaller-scale positioning can be commercially relevant when it aligns with laboratory, pilot, and specialized production needs.
Chinese producers form a defining part of the market's growth dynamics. Shandong Shida Shenghua Chemical, Hualu Hengsheng Group, and Dongying City Longxing Chemical each operate large-scale DMC production using oxidative carbonylation and related routes, supplying industrial, battery, and pharmaceutical grades. Their strategy is largely oriented around scale, regional supply, and expanding capacity to meet growing domestic and export demand. The presence of multiple large-scale Chinese producers contributes to the region's market weight, but also intensifies competition on cost, grade availability, and supply reliability.
Recent developments illustrate how these strategic directions are being executed. In February 2026, UBE Corporation began groundbreaking and construction of a new DMC and EMC plant in Louisiana, USA, with 100,000 tons per year of DMC capacity, targeted for operation in the second half of fiscal 2026 to meet North American battery and semiconductor demand. This move is strategically significant because it ties capacity addition directly to regional end-demand growth and reduces reliance on longer logistics chains for important customer segments. Similarly, in November 2025, Jiangsu Sailboat Petrochemical announced a collaboration with Asahi Kasei for a new high-purity DMC and ethylene carbonate facility in Lianyungang, China, expanding battery-grade supply. That partnership reflects a broader pattern: high-purity and battery-grade capacity is increasingly being scaled through coordinated projects rather than isolated plant buildouts.
Looking ahead, the competitive landscape is likely to evolve along three lines. First, consolidation pressure may increase where scale, grade control, and regional reach create advantages that smaller players struggle to match. Second, differentiation will likely deepen by grade and application, with battery-grade and pharmaceutical/reagent-grade segments becoming more distinct in terms of customer requirements and margin dynamics. Third, new entrants and capacity additions in key regions may alter local supply balances, especially where demand growth is fastest and import dependence is high. The companies that win will be those that can combine technical reliability with commercial agility, not simply those with the largest nameplate capacity.
Future Trends and Commercial Implications
Trend 1: Battery-Grade DMC as a Strategic Sub-Segment
Battery-grade DMC is poised to become one of the most strategically important sub-segments of the market over the next three to five years. The combination of electrolyte formulation needs, scaling battery manufacturing, and qualification-driven purchasing creates a demand profile that rewards consistency, documentation, and supply reliability. Commercial opportunity here is not limited to volume; it extends to long-term supply alignment, technical support, and the ability to meet evolving customer specifications. The risk is that overcapacity in lower-grade segments does not automatically translate into battery-grade competitiveness, because the value drivers differ and qualification cycles can be slow.
Trend 2: Regionalization of Supply and Demand
The market is moving toward greater regional alignment between production and end-use. Capacity additions in North America and continued expansion in Asia illustrate a pattern in which producers are siting assets closer to major demand centers to reduce logistics exposure and improve service levels. This regionalization can benefit buyers through shorter lead times and more stable supply, but it also introduces new complexity: regional availability may diverge, and trade or customs classifications can influence where material is sourced. Companies that map regional demand against local capacity, import status, and logistics risk will be better positioned to manage sourcing decisions.
Trend 3: Green Solvent Substitution and Regulatory Tailwinds
DMC's positioning as a lower-toxicity solvent alternative continues to provide a structural adoption pathway in selected applications. As regulatory expectations around solvent use tighten and corporate sustainability goals influence procurement choices, DMC can benefit from substitution where performance and compliance align. The commercial opportunity lies in applications where the molecule's safety and environmental profile translates into tangible qualification advantages. The uncertainty is that substitution is application-specific and not automatic; performance trade-offs, cost, and supply consistency still determine outcomes.
Risk Considerations
Several uncertainties warrant attention. Methanol price volatility can compress margins or shift sourcing behavior quickly, particularly when geopolitical events or Middle East supply disruptions occur. Regulatory classification changes, customs rulings, and trade policy shifts can alter effective market access and redirect flows. Capacity additions may outpace demand in certain grades or regions, creating localized oversupply even as other segments remain tight. Finally, the qualification and consistency requirements of premium-grade customers mean that operational execution matters as much as strategic intent; a misstep in quality or reliability can have outsized commercial consequences in battery and pharmaceutical channels.
Actionable Recommendations for Decision-Makers
For manufacturers and producers: Prioritize grade-specific capability building over undifferentiated scale. The market's most valuable growth is increasingly tied to battery-grade and high-purity segments, where specification control, quality systems, and customer qualification support differentiate suppliers. At the same time, producers should structure feedstock and inventory strategies to withstand methanol price volatility, and evaluate regional capacity options that reduce exposure to logistics disruption and trade classification uncertainty. Where possible, align new capacity with identifiable regional demand rather than generic volume assumptions.
PW Consulting
For investors: Assess exposure by grade and application, not just by company name. The DMC market is bifurcating in terms of value drivers: industrial volumes may follow cost and availability logic, while battery-grade and pharmaceutical-grade segments reward quality, consistency, and long-term supply relationships. Investment theses should account for regional capacity additions, feedstock sensitivity, and the timing of demand buildouts in energy storage and specialty applications. Also consider the risk that capacity expansions in one segment do not translate into pricing power if premium-grade demand does not keep pace.
For procurement and sourcing teams: Treat DMC sourcing as a grade- and region-specific decision. Industrial buyers may prioritize cost stability, but battery and pharmaceutical buyers should place greater weight on specification consistency, documentation, and supplier qualification track records. Given methanol-driven cost volatility and the potential impact of customs and trade rulings, it is prudent to maintain diversified sourcing options where feasible and to monitor regulatory developments that can affect origin eligibility and import feasibility. Building longer-term alignment with suppliers that can demonstrate consistent quality may reduce disruption risk more effectively than frequent spot-market switching.
Across all roles, the strategic value of DMC intelligence lies in connecting macro growth trends with grade-level realities, regional supply dynamics, and the operational requirements of end-demand. Detailed segmentation data, competitive capacity mapping, and scenario-based cost analysis can sharpen decisions that headline market numbers alone cannot resolve. For organizations that need a closer look at grade-specific demand splits, regional dynamics, and company-level positioning, deeper research resources can help translate the broader trend picture into actionable sourcing, investment, and capacity strategies.
For detailed analysis of this topic, please visit the official page: Dimethyl Carbonate (DMC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


