



Car Care Products Market 2032: What Really Fuels the 4.5% CAGR Growth Beyond 15.4×10³ Million

The Car Care Products Market: Strategic Trends and Commercial Opportunities Through 2032
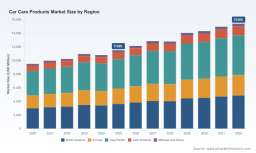
The global car care products market is navigating a period of structural transformation. With total revenue reaching approximately USD 11,500 million in 2025 and projected to expand at a compound annual growth rate of 4.5% through 2032, the sector is moving beyond cyclical demand patterns toward a more innovation-driven and regulation-shaped landscape. The market has demonstrated steady recovery from the volatility of the early decade, with revenue climbing from USD 9,500 million in 2020 to a base of USD 11,500 million in 2025. Forecasts indicate continued growth, with revenue expected to reach USD 15,400 million by 2032, though the trajectory will not be uniform. Mid-period fluctuations, such as the slight contraction projected in 2028 before accelerating again toward 2032, signal that pricing dynamics, regulatory shifts, and innovation cycles will create uneven growth pockets rather than a straight-line expansion.
For executives, strategists, and investors, the size of the market is only the starting point. The strategic question is how value is redistributed across product categories, application channels, and geographic demand centers, and which capabilities will determine market share in the next cycle. The concentration structure of the industry, with the top three players accounting for roughly 42% of revenue and the top five capturing about 55%, indicates a moderately consolidated landscape. This creates room for both competitive pressure from established multinationals and meaningful disruption from specialized entrants that can command premium positioning through performance differentiation or format innovation.
Market Landscape and Core Challenges
The car care products market operates at the intersection of consumer discretionary spending, professional detailing services, and increasingly, regulatory and trade dynamics that reshape cost structures. The sector's revenue base has grown at a moderate but persistent pace, reflecting a combination of vehicle parc expansion, renewed emphasis on vehicle appearance as a value-preservation behavior, and the gradual formalization of care routines among both retail and commercial users. However, the headline growth rate masks underlying tensions that decision-makers must address when positioning product portfolios, pricing strategies, and geographic exposure.
One of the most consequential challenges is the rising impact of trade and tariff policy on input costs and competitive positioning. Recent policy actions have adjusted import conditions for automobiles and automobile parts, with duties that extend indirectly into the broader automotive ecosystem. For car care manufacturers and formulators, these measures matter because they influence the cost of imported raw materials, packaging components, and specialized chemical inputs, as well as the competitive balance between domestically produced and imported finished goods. In a market where ingredient quality, coating performance, and formulation consistency are central to brand trust, even modest cost pressure can compress margins unless companies can pass through changes without eroding volume.
A second challenge lies in the shifting balance between do-it-yourself and do-it-for-me application channels. While both segments remain significant, the relative growth trajectories of each are being reshaped by workforce availability in professional detailing, consumer time constraints, and the growing sophistication of products that are designed to be effective with less user expertise. Companies that rely heavily on one channel face exposure if user behavior or service economics move in an unanticipated direction. The practical implication is that product design, packaging format, and go-to-market strategy must increasingly accommodate hybrid usage models rather than treating consumer and commercial applications as separate silos.
A third challenge is the premiumization paradox. Consumer and commercial buyers are demonstrating willingness to pay more for products that promise longer-lasting protection, easier application, or enhanced aesthetic results. At the same time, inflationary sensitivity and the availability of value-oriented alternatives restrict how much premiumization can be counted on as a standalone growth engine. The result is a market where superior performance must be evidenced not just through claims but through demonstrable results, repeat usage, and integration with broader care routines. Brands that can translate product superiority into clear consumer-facing or service-facing value propositions are better positioned to defend margin, while those competing primarily on price face a narrowing path to sustainable differentiation.
Key Demand Drivers and Structural Forces
Technology Innovation and Formulation Breakthroughs
Product performance is increasingly defined by advances in protective coatings, quick-application finishes, and formulations that reduce the effort required to achieve professional-grade results. The segment focused on glaze and coating products, while smaller in absolute terms than wax and cleaning categories, plays an outsized role in shaping the premium narrative of the market because it directly addresses durability, gloss retention, and surface protection. Innovation in this space is not only about chemistry; it is also about usability. Products that combine protective performance with shorter curing times, reduced sensitivity to application conditions, or compatibility with a broader range of substrates can unlock faster adoption among both retail users and commercial detailers.
Recent product launches illustrate how companies are using new formulations and catalog expansion to reinforce positioning. In early 2025, Luminous introduced a new catalog of premium car care products emphasizing advanced detailing and protection formulas, signaling a continued push toward differentiated performance claims in the higher-end segment. Later in the year, Stinger Chemicals announced plans to launch its Quantum Car Care Line at a major industry event, targeting commercial users with specialized retail products. These moves reflect a broader pattern: innovation is being deployed both to elevate the performance ceiling in premium categories and to create purpose-built offerings for professional and retail channels that demand consistency, throughput, and specialized protection characteristics.
Car Care Cosmetics for Petrol Channel Market
Policy and Regulatory Environment
Regulatory and trade policy is becoming a more prominent force in the market's cost and competitive dynamics. Adjustments to import duties on automobiles and parts have direct and indirect implications for the automotive aftermarket ecosystem, including the suppliers of care products that serve vehicle owners, service providers, and fleet operators. While car care products are not always the primary target of such measures, the broader policy environment influences the cost of inputs, the relative attractiveness of domestic versus imported manufacturing, and the strategic calculus of supply chain design.
Car Wax Market
The practical significance for market participants is that regulatory volatility is no longer a peripheral risk. Companies with flexible sourcing strategies, regional manufacturing footprints, and the ability to reformulate around input availability are better equipped to manage sudden cost shifts. At the same time, the regulatory environment can create opportunity for firms that can demonstrate compliance, consistency, and transparency as competitive advantages. In segments where trust and performance claims matter, the ability to navigate policy shifts without disrupting product availability or quality becomes part of the brand promise itself.
Demand-Side Shifts in Consumer and Commercial Behavior
Demand patterns are being reshaped by evolving attitudes toward vehicle ownership, maintenance, and appearance. Vehicles are increasingly viewed not only as transportation assets but also as personal spaces and, for many owners, as items whose condition has tangible economic and emotional value. This has supported demand for products that preserve interior surfaces, protect exterior finishes, and simplify routine maintenance. At the same time, professional detailing and commercial fleet care continue to drive demand for higher-volume, repeatable, and operationally efficient products.
The interior segment represents a meaningful portion of market value, reflecting sustained attention to surfaces, materials, and cleanliness inside the cabin. Exterior care remains the largest body-part category, consistent with the visibility and protection benefits that drive purchase decisions. In application terms, both DIY and DIFM channels contribute substantially, but their relative importance varies by region, customer segment, and product type. Companies that understand where convenience, performance, and service support matter most can tailor product formats, instruction design, and distribution to the channel in which they compete, rather than treating all demand as interchangeable.
Supply Chain and Cost Structure Dynamics
The cost environment for car care products is influenced by raw material availability, chemical input pricing, packaging costs, and logistics complexity. As with many consumer and industrial goods, the ability to manage these pressures depends on formulation flexibility, supplier diversification, and packaging efficiency. Products that rely heavily on specialized imported inputs may face greater exposure to tariff-related and logistics-related cost fluctuations, while those with more standardized ingredient profiles or regional supply options can adapt more readily.
In addition, the market's moderate concentration means that larger players often have advantages in procurement scale, distribution breadth, and brand investment capacity. Smaller or more specialized firms, however, can compete by focusing on performance niches, channel-specific needs, and faster product iteration. The strategic implication is that cost management and innovation are not separate agendas; they are increasingly intertwined. A formulation decision that reduces sensitivity to volatile inputs, or a packaging change that improves shelf efficiency and user experience, can have a direct impact on competitiveness in a market where differentiation is often subtle and repetition of purchase depends on consistent satisfaction.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a group of established manufacturers and specialists, each with a distinct positioning strategy. Turtle Wax operates as a broad-based manufacturer of washes, waxes, coatings, and detailing supplies, giving it a wide touchpoint across consumer and professional needs. Meguiar's maintains a strong identity around high-quality chemicals, polishes, waxes, and interior and exterior appearance products, with an emphasis on performance credibility in appearance care. SONAX positions itself in the premium automotive chemical segment, focusing on vehicle maintenance and detailing products that appeal to users seeking higher-end results. Stinger Chemicals develops both retail and commercial product lines for detailing and protection, giving it a dual-channel orientation that can adapt to different purchasing and usage contexts.
Beyond these specialists, larger diversified manufacturers also participate in the market. 3M contributes abrasives, cleaners, polishes, waxes, and detailing compounds, leveraging its broader materials science capabilities and distribution reach. Calumet's role as a manufacturer of specialty solvents, waxes, and petrolatums used in consumer car care formulation illustrates the importance of upstream ingredient and input suppliers in shaping what is ultimately possible at the finished-product level. Together, these companies reflect a market in which competitive advantage comes from a combination of brand trust, formulation expertise, channel relationships, and the ability to align product claims with real-world performance.
Several strategic patterns are visible among the leaders. One is segmentation discipline: companies are increasingly differentiating not just by brand but by intended user, application context, and performance promise. Another is the use of product-line expansion to capture adjacent demand without diluting core positioning. Catalog launches and specialized line introductions, such as those seen in 2025, are examples of how firms attempt to broaden relevance while maintaining a credible performance narrative. A third pattern is the growing importance of channel-specific product design. Commercial users often prioritize consistency, coverage, and operational efficiency, while retail buyers may weigh ease of use, visible results, and perceived value. Companies that design for these differences rather than offering a uniform portfolio across all channels are better placed to defend share and pricing.
PW Consulting Health Care Research Center
The market structure also suggests ongoing evolution rather than static competition. With a moderately concentrated base, there is room for consolidation among players seeking scale in procurement, distribution, or brand investment. At the same time, new entrants and niche specialists can gain traction by focusing on underserved use cases, premium protection claims, or specific regional demand patterns. The most successful players are likely to be those that can combine a clear positioning with operational flexibility, allowing them to adapt product offerings and supply strategies as demand and policy conditions shift.
Forward Outlook: Three Strategic Trends for 2026 to 2032
The next several years are likely to be defined by a combination of product performance competition, channel rebalancing, and continued sensitivity to cost and regulatory pressures. Three trends stand out as particularly relevant for commercial planning.
The first trend is the continued premiumization of protection and finish products, especially in categories associated with longer-lasting results and easier application. As users become more discerning and more aware of the link between surface care and vehicle appearance, demand for products that deliver durable gloss, resistance to environmental wear, and simplified application is expected to remain strong. The commercial opportunity lies in creating credible, repeatable performance stories that support higher price points without depending solely on marketing claims. Products that can demonstrate measurable differences in durability, ease, or finish quality are more likely to command loyalty and reduce price sensitivity over time.
The second trend is the ongoing realignment between DIY and DIFM demand, influenced by labor availability, consumer time use, and the increasing sophistication of user-friendly formulations. Even within the DIY segment, products that reduce effort and increase consistency can blur the line between consumer and professional outcomes. For commercial users, the opportunity is in products that improve throughput, reduce variability, and support service quality across multiple locations or fleets. For manufacturers and distributors, the strategic priority is to ensure that product design, instructional support, and packaging are aligned with the practical realities of how each channel actually uses the product.
The third trend is the increasing importance of supply-side resilience and regulatory adaptability. Tariff adjustments and import policy shifts can influence input costs, sourcing decisions, and competitive positioning, particularly for products that depend on specialized imported components. Companies that build redundancy into sourcing, maintain formulation flexibility, and can communicate reliability to customers will be better positioned to manage disruption. Conversely, firms that are heavily dependent on a single supply route or a narrow set of inputs may face more volatile margin performance. This creates an opportunity for players to differentiate not only through product performance but also through operational dependability and transparent compliance practices.
These trends are not without risk. Premiumization depends on sustained consumer and commercial willingness to invest in appearance care, which can weaken if macroeconomic pressure intensifies. Channel shifts may not unfold uniformly across regions, making geographic assumptions risky if treated as universal. Regulatory and trade policy can change quickly, altering cost structures and competitive dynamics in ways that are difficult to predict far in advance. The market's growth path also includes intermittent deceleration points, as reflected in the mid-period forecast pattern, which suggests that short-term momentum should not be mistaken for a guaranteed straight-line trajectory. Companies that plan for variability, rather than assuming constant acceleration, will be better prepared to allocate resources and adjust strategies as conditions evolve.
Actionable Priorities for Decision Makers
For manufacturers, the priority is to align product innovation with the performance and usability expectations that actually drive repeat purchase. This means investing in formulations and formats that deliver visible, durable results while reducing the risk of user error or inconsistent outcomes. It also means evaluating where portfolio breadth adds value and where focus sharpens competitive positioning. Companies should assess channel-specific needs carefully, since the same product may need different packaging, instructions, or performance emphasis depending on whether it is sold into retail, professional detailing, or fleet contexts.
For investors, the emphasis should be on identifying companies with credible differentiation, resilient supply strategies, and the ability to convert product superiority into measurable customer retention. Market size and growth rate provide a useful backdrop, but the more important questions are whether a company can defend margin in a moderately concentrated market, whether its innovation pipeline addresses real user pain points, and whether its cost and sourcing structure can withstand regulatory or input-price shocks. Businesses that combine strong positioning with operational flexibility are more likely to sustain advantage through uneven growth cycles.
For procurement and commercial buyers, the priority is to balance performance requirements with total cost of ownership, taking into account not only unit price but also consistency, application efficiency, and the downstream impact on service quality or customer satisfaction. In professional and fleet environments, variability in results can create hidden costs through rework, customer complaints, or inconsistent presentation. Evaluating product options against practical usage conditions, rather than against label claims alone, can help buyers select solutions that support both operational reliability and end-user perception.
Across all these perspectives, one consistent theme is that the market is becoming more demanding in terms of proof, not just promise. As product performance expectations rise and cost and regulatory pressures intensify, the ability to access detailed segment-level intelligence, competitive benchmarks, and scenario-based planning assumptions becomes increasingly valuable. Organizations that can ground strategic choices in granular data on product categories, application channels, regional demand patterns, and supplier dynamics will be better equipped to anticipate shifts and act before they become obvious to the broader market.
The car care products market is moving toward a phase in which durable differentiation will depend on the intersection of formulation quality, channel alignment, and operational resilience. Growth to 2032 is supported by steady demand and continued product innovation, but the value created will accrue disproportionately to companies that can convert broad market momentum into focused, defensible positioning. For executives and investors seeking a deeper, segment-level view of these dynamics, a more detailed research assessment can provide the kind of customized insight needed to sharpen portfolio strategy, evaluate competitive exposure, and prioritize the opportunities most relevant to a specific business context.
For detailed analysis of this topic, please visit the official page: Car Care Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


