



What's Driving Dibasic Ester Market's 6.5% CAGR Through 2032

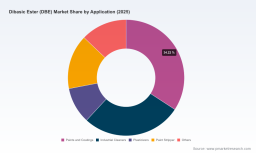
Dibasic Ester Market: Strategic Trends & Commercial Opportunities Through 2032
The dibasic ester (DBE) market has transitioned from a niche solvent portfolio to a strategically relevant segment within specialty chemicals, driven by tightening environmental regulations and evolving application requirements. Over the historical period from 2020 to 2025, the market demonstrated resilient expansion, reaching a base-year valuation of approximately 162.0 million USD in 2025. Forward projections indicate a compound annual growth rate of 6.5 percent across the 2026 to 2032 forecast horizon, with revenue scaled in millions of USD. This trajectory reflects a market that has moved past early-adoption friction and is now embedding DBE formulations into mainstream industrial, coating, and cleaning applications where performance, regulatory compliance, and sustainability must align.
The structural expansion is not uniform across all regions and end-use categories, but the overall momentum is clear. Asia Pacific continues to scale rapidly as manufacturing hubs reconfigure solvent portfolios, North America and Europe anchor demand through regulatory-driven reformulation, and emerging regions are gradually capturing share as cost-effective DBE grades become more accessible. Market concentration remains moderate, with the top three participants holding roughly 35 percent of industry revenue and the top five reaching approximately 45 percent. This fragmented-yet-concentrated structure signals room for both consolidation and differentiated positioning, depending on how companies navigate product quality, feedstock sourcing, and regional compliance requirements.
Worldwide Dibutyl Maleate (DBM) Market
Market Landscape And Core Challenges
The current DBE landscape is defined by a need to balance performance consistency with environmental compliance, while simultaneously managing feedstock volatility and regional specification fragmentation. Two to three structural challenges stand out as critical inflection points for operators and buyers alike.
First, regulatory pressure across major markets is accelerating solvent reformulation, but compliance pathways are not harmonized. Manufacturers and formulators must navigate differingVOC thresholds, hazardous air pollutant restrictions, and regional certification timelines. This creates adaptation costs and can delay product commercialization, especially for companies serving multiple jurisdictions with a single formulation strategy. Second, feedstock economics and supply chain resilience remain sensitive. Even as bio-based routes mature, parity with petrochemical equivalents fluctuates with agricultural commodity prices, fermentation scale-up timelines, and logistics constraints. Operators that rely on single-source raw materials or narrow regional procurement face margin pressure during periods of input cost instability. Third, application-specific performance expectations are rising. Paints and coatings, industrial cleaners, plasticizers, paint strippers, and other specialty uses each impose distinct solvency, evaporation, and safety profiles. Delivering consistent quality across these segments without compromising cost structure requires tighter process control and more advanced quality assurance capabilities.
Together, these challenges are reshaping how participants design production footprints, manage formulation partnerships, and prioritize product grades. They also create a clear divergence between suppliers that can offer compliant, traceable, and performance-validated solutions and those competing primarily on price in commoditized niches.
Key Drivers Shaping Market Dynamics
The expansion of the DBE market is being propelled by a combination of technological, regulatory, demand-side, and supply chain forces. Each driver reinforces the others, making DBE increasingly attractive as a multifunctional solvent and intermediate across industrial applications.
Technological innovation and process breakthroughs are expanding the value proposition of DBE beyond conventional solvent replacement. Purification advances, fractionation techniques, and custom blending capabilities have improved consistency, odor profiles, and application compatibility. This has enabled higher-performance use cases where formulators need predictable evaporation rates, low residue, and compatibility with resin systems. Companies with proprietary fractionation and blending know-how are increasingly differentiating through specification-grade products rather than generic solvent volumes.
Policy and regulatory environments are acting as a powerful catalyst. Ongoing reviews of legacy solvents and evolving emission standards are pushing formulators toward alternatives with lower VOC profiles and reduced hazardous air pollutant exposure. In parallel, broader sustainability frameworks are encouraging substitution away from chlorinated and high-VOC solvents, particularly in European markets and other regions with strict environmental enforcement. The cumulative effect is a reformulation pipeline where DBE is prioritized as a practical, performance-aligned alternative.
Demand-side behavior is also shifting. Industrial buyers are increasingly treating solvent selection as a risk-management decision rather than a purely cost-driven purchase. Procurement teams prioritize compliance documentation, biodegradability profiles, and supply reliability, especially in coatings, pharmaceutical-adjacent applications, and electronics-related cleaning processes. This change in buying logic favors suppliers that can provide transparent product attributes, consistent lot-to-lot quality, and application support.
PW Consulting
Supply chain and cost structure dynamics are evolving alongside these demand shifts. Bio-based feedstock routes have progressed toward commercial viability, with certain fermentation-derived intermediates reaching cost levels that are within a reasonable range of conventional petrochemical equivalents. This progress reduces the premium historically associated with greener solvent pathways and opens the door to broader adoption, provided that scale, production reliability, and integration with existing DBE manufacturing lines can be sustained. At the same time, partnerships between specialty fermentation players and established DBE producers are laying the groundwork for commercial-scale bio-succinate-related projects, which could further strengthen the sustainability narrative and expand the feedstock base over the next several years.
Competitive Landscape And Leading Strategies
The DBE competitive field is a mix of global specialty chemical players, regional manufacturers, and application-focused producers. Their strategic positioning varies by geography, product purity requirements, feedstock strategy, and end-use specialization, but several competitive themes are visible across the market.
Some leading participants emphasize recycled-content and biodegradable solvent solutions, positioning their DBE offerings as compliant, performance-tested options for coatings, polyurethane polyols, recycling solvents, and soil stabilization. Others differentiate through high-performance solvent grades derived from mixed acid streams and fractionation expertise, targeting coatings, resins, and industrial applications where clarity, low odor, and processing ease matter. European-based manufacturers leverage regional production and specialty distribution channels to serve industrial solvents and performance materials, while multinational portfolios maintain breadth across geographies and application categories. Certain players focus on high-purity grades for pharmaceutical, personal care, and electronics-adjacent markets, where exacting quality standards become a barrier to entry and a source of margin resilience. In Asia, large-scale production capacity and growing specification-grade capabilities are enabling regional suppliers to capture demand from paint, coating, printing ink, and dispersant applications while progressively upgrading quality for more demanding contracts.
These different strategic postures are producing a market that is both consolidating and fragmenting at the same time. Consolidation is likely where scale, feedstock integration, and regulatory compliance create advantages for larger portfolios and well-capitalized producers. Fragmentation persists where regional formulation needs, purity specifications, and application-specific service requirements reward localized expertise and narrower specialization. New entrants and capacity expansions tend to succeed when they bring a clear position—whether in bio-based content, ultra-high purity, cost-efficient large-volume production, or application-tailored blends—rather than attempting to compete across all segments without differentiation.
Recent corporate activity underscores the strategic importance of this positioning. Investments in bio-based DBE production facilities signal a long-term commitment to sustainability-linked demand and feedstock diversification. Product launches targeting low-VOC formulations for automotive applications illustrate how regulatory and performance requirements can converge into commercially viable specialty grades. These moves are not isolated announcements; they indicate how participants are aligning R&D, regulatory preparation, and application development to capture reformulation demand in specific end markets.
Forward Outlook: Trends And Commercial Opportunities
Looking ahead across the 2026 to 2032 window, several trends are likely to shape how the DBE market evolves and where commercial opportunities emerge.
One major trend is the continued acceleration of solvent reformulation as regulatory review and emission standards tighten further. This creates opportunities for suppliers that can offer compliant, application-validated DBE grades with strong documentation and technical support. Companies that proactively align product portfolios with regional compliance expectations will be better positioned to secure long-term formulation partnerships, especially in coatings and industrial cleaning segments where reformulation cycles can be lengthy and switching costs are meaningful.
A second trend is the greater commercial maturity of bio-based and fermentation-derived intermediates for DBE-related product families. As production scales and cost gaps narrow, sustainability credentials become more commercially actionable rather than purely aspirational. This opens opportunities for differentiation through lower-carbon sourcing, recycled content integration, and tailored bio-based blends. It also raises the strategic importance of feedstock contracts, fermentation partnerships, and production reliability, since buyers will increasingly evaluate not only performance but also supply continuity and traceability.
A third trend is the growing premium on specification-grade quality and application-specific service. As DBE moves deeper into demanding markets—including pharmaceutical-adjacent, electronics, and advanced coatings—the ability to deliver consistent purity, predictable behavior, and technical problem-solving becomes a competitive advantage. This favors producers that invest in quality control, custom blending, and application engineering, and it creates room for segmented pricing rather than undifferentiated commodity competition.
These trends carry commercial opportunities, but they also contain risks. Regulatory timelines can shift, and regional enforcement intensity may vary, affecting the pace of substitution. Feedstock availability and cost parity may be influenced by agricultural market dynamics, energy prices, and logistics disruptions. Capacity additions could intensify competition in certain regions or grades, particularly where differentiation is limited. Finally, application migration is not automatic; performance validation, customer testing, and formulation compatibility can slow adoption even when regulatory and sustainability incentives are strong. Participants that monitor these uncertainties and build flexible sourcing, product, and service strategies will be better prepared to capture upside while managing downside exposure.
Divinylbenzene (DVB) Market
Strategic Actions For Decision-Makers
For manufacturers, the priority is to define a clear DBE positioning that matches both market demand and internal capability. Companies should evaluate whether they can win through scale and cost efficiency, through high-purity specialty grades, through bio-based or recycled-content differentiation, or through application-specific formulation support. Investments in fractionation, blending, quality assurance, and technical service often matter as much as raw capacity, because buyers increasingly choose suppliers that reduce reformulation risk and improve process reliability. Feedstock strategy also deserves close attention, especially where bio-based routes and partnerships can strengthen long-term resilience and align with customer sustainability expectations.
For investors, the market calls for discipline in distinguishing durable advantage from short-term capacity expansion. The most attractive opportunities are likely to sit with participants that combine regulatory readiness, consistent quality, and credible sustainability pathways with a defensible application focus. Capacity announcements alone do not guarantee differentiation; the key questions are whether a company can protect margins through specification leadership, secure reliable feedstock supply, and sustain customer relationships in reformulation-intensive segments. Monitoring partnerships, product launches, and regional compliance shifts can provide early signals about where share and value creation are consolidating.
For procurement and sourcing leaders, DBE should be evaluated as part of a broader solvent strategy rather than as a simple price comparison. Factors such as compliance documentation, biodegradability and VOC characteristics, lot consistency, technical support, and supply continuity can have a material impact on formulation risk and operational reliability. Building relationships with suppliers that can support multiple regional requirements and provide transparent product information may reduce exposure to reformulation delays and quality variability. Where possible, securing longer-term supply arrangements for critical grades can help manage volatility in both feedstock costs and regional availability.
As the DBE market continues to evolve, the companies and buyers that act early on regulatory alignment, feedstock strategy, and specification-grade differentiation will be best positioned to translate market momentum into commercial advantage. For decision-makers seeking more granular segmentation data, regional demand patterns, and tailored strategic recommendations, the full research report provides a deeper view of the market structure and the operational choices that will determine competitive outcomes through 2032.
For detailed analysis of this topic, please visit the official page: Dibasic Ester (DBE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


