



District Heating and Cooling Market 2026: Beyond the 4.5% CAGR Story

The District Heating and Cooling Market: Strategic Trends and Commercial Opportunities Through 2032
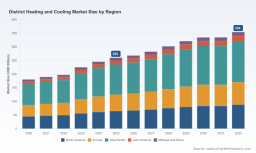
The district heating and cooling (DHC) sector has entered a phase of structural expansion, driven by urban decarbonization mandates, technological maturation, and shifting consumer expectations around energy resilience. Market valuation reached approximately USD 260 billion in 2025, reflecting a compound annual growth rate of 4.5 percent across the 2026-2032 forecast horizon. The trajectory from 2020 onward demonstrates consistent upward momentum, with recent acceleration tied to policy enforcement and capital reallocation toward low-carbon thermal infrastructure. This growth is not merely cyclical; it represents a reconfiguration of how cities and industrial clusters source, distribute, and optimize thermal energy.
At this scale, the market carries meaningful implications for capital allocation, technology roadmapping, and partnership strategy. Understanding where value is created—and where friction persists—requires looking beyond headline figures to the operational, regulatory, and competitive forces shaping deployment decisions. The following analysis examines the current market reality, the forces accelerating change, the competitive dynamics among established players, and the strategic implications for executives navigating the next five years.
Market Reality: Scale, Structure, and Core Challenges
The thermal infrastructure market has grown from roughly USD 180 billion in 2020 to the current USD 260 billion baseline, with forward projections pointing toward USD 354 billion by 2032. This expansion reflects both incremental capacity additions and a structural shift toward integrated heating and cooling networks that serve multi-consumer zones. Geographically, the market is diversified across mature and emerging deployment regions, with Asia Pacific representing the largest demand pool, followed by North America and Europe. Europe and parts of the Middle East have concentrated heavily on cooling infrastructure in high-density urban and commercial environments, while Northern European and select Asian markets have prioritized heating network modernization and renewable integration.
Three challenges define the current inflection point:
- Infrastructure capital intensity and deployment timelines. District networks require extensive piping, substations, valve assemblies, and balancing equipment. Concession-based expansions frequently span tens of kilometers and involve multi-year construction, permitting, and interconnection sequencing. Capital planning must accommodate prolonged payback periods, material procurement risk, and coordination with municipal authorities.
- Decarbonization compliance pressure. Regulatory frameworks are tightening renewable share requirements and performance measurement methodologies for both heating and cooling. Operators and equipment suppliers must demonstrate measurable emissions reductions while maintaining reliability, particularly in markets where fossil-based backup still provides peak-load stability.
- Systems integration and operational complexity. Modern networks increasingly blend multiple heat sources—industrial waste heat, data center exhaust, geothermal, biomass, and large-scale heat pumps—into unified distribution systems. This introduces control coordination challenges, flow balancing complexity, and the need for advanced monitoring and predictive maintenance to protect efficiency targets.
These challenges are not blockers; they are the organizing constraints that determine which business models scale and which stall. Companies that treat thermal infrastructure as a systems problem—spanning source generation, distribution, control hardware, and consumer-side efficiency—gain a meaningful advantage in winning concessions, securing supply contracts, and delivering performance guarantees.
PW Consulting
Key Drivers Accelerating Market Transformation
Multiple forces are converging to reshape demand patterns, investment priorities, and technology adoption curves. The following drivers explain why growth is accelerating and where competitive advantage is being formed.
Technology Innovation and System-Level Breakthroughs
Thermal networks are transitioning from single-source, linear distribution models to multi-source, digitally coordinated systems. Heat pumps, advanced substations, motorized control valves, and heat exchangers now enable finer temperature control, better load-matching, and higher renewable penetration. Waste heat recovery has emerged as a particularly valuable capability. Large data center operators and industrial facilities are increasingly viewed as thermal asset owners rather than pure electricity consumers, with excess heat routed into neighboring district networks. This shift changes the economics of thermal supply: low-marginal-cost heat becomes available where population and commercial density intersect with suitable infrastructure corridors.
Practical examples illustrate how this is unfolding. Operator activity in Espoo has demonstrated the commencement of large-scale heat pump plants utilizing excess heat from major data center operations, producing substantial district heating output and covering a significant share of local demand. Such deployments show that data-center-adjacent thermal integration is moving from feasibility studies into operating reality. At the same time, equipment manufacturers continue to refine skid-mounted substation solutions and valve assemblies that reduce on-site integration friction, helping network builders standardize components across expansions.
Policy and Regulatory Momentum
Policy has become a central determinant of deployment economics. In the European Union, binding national targets now require increasing the share of renewables in district heating and cooling, supported by revised methodologies for counting renewable cooling performance. The EU Heating and Cooling Strategy, expected in the second quarter of 2026, is positioned to accelerate decarbonization implementation and clarify compliance pathways. These policy signals matter because they influence concession award criteria, public funding eligibility, and long-term off-take certainty.
Funding mechanisms are reinforcing the regulatory direction. Calls such as LIFE-2025-CET-DHC provide support at up to 95 percent for proposals focused on efficient district heating and cooling networks that integrate renewable energy and waste heat. For project developers and equipment providers, this creates a pathway to reduce capital exposure on pilot and early-scale deployments, particularly in regions where municipal balance sheets are constrained. Meanwhile, national and municipal authorities continue to structure concessions that tie network expansion to decarbonization outcomes, as shown in recent green heating network agreements that add tens of kilometers of distribution capacity and serve tens of thousands of households through biomass and recovered energy.
Demand-Side Shifts in Urban, Industrial, and Commercial Settings
Demand is no longer driven solely by legacy residential heating contracts. Industrial clusters remain a major consumer segment, but the composition of demand is broadening. Commercial complexes, education campuses, healthcare facilities, and mixed-use urban districts are increasingly evaluated through the lens of thermal efficiency, continuity of supply, and emissions performance. Cooling demand in hot climates and densely built environments is also accelerating the case for centralized chilled water systems, particularly where peak electricity pricing and grid constraints make decentralized cooling less attractive.
Partnership structures reflect this broadening demand base. Recent expansions of district cooling systems serving education group buildings demonstrate how institutional clients are being integrated into larger sustainability programs, with completion timelines aligned to academic and operational cycles. Large-scale cooling plant inaugurations with significant refrigeration tonnage further indicate that high-capacity centralized cooling is becoming a standard asset class in regions where cooling is a dominant load. These demand-side shifts create opportunities for operators to secure long-term service relationships and for equipment suppliers to tailor control and heat exchange solutions to multi-building portfolios.
Supply Chain and Cost Structure Dynamics
The cost structure of district networks is being reshaped by material intensity, component standardization, and financing availability. Piping, substations, valves, and heat exchangers remain essential physical inputs, and large concession-driven expansions highlight how material procurement and installation logistics influence project pace. At the same time, standardization of skid-based substation packages and advanced control hardware can reduce customization cost and accelerate commissioning. Financing innovation also matters: where public grants, climate funds, and long-term concession revenue streams exist, the cost of capital becomes a decisive factor in who can pursue expansion aggressively.
A nuanced risk in the cost picture is the tension between rapid expansion and performance assurance. Faster network growth can strain quality control, balancing, and maintenance planning if supply chains are not aligned to technical specifications. Operators and manufacturers that invest in repeatable engineering processes and remote monitoring capabilities can protect margins while scaling, whereas fragmented procurement approaches may create operational inefficiencies that erode the value of expansion.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive environment combines global operators, regional specialists, and equipment manufacturers, each competing on a different axis of value creation. The structure is moderately concentrated, but the variation in business models means that direct comparison requires attention to whether a company competes as a network operator, a technology supplier, or both.
Danfoss operates from an equipment and control standpoint, providing advanced control valves, motorized control valves, ball valves, heat exchangers, and complete substation or skid solutions for district heating and cooling networks and building applications. Its differentiation lies in component-level precision and integration support, positioning it as a critical supplier for operators seeking to standardize control architectures and improve balancing across networks. For DHC projects, Danfoss-type solutions can reduce engineering complexity and improve the reliability of temperature and flow regulation across varied load conditions.
Veolia competes as an operator and developer, with a strong orientation toward fifth-generation systems that use geothermal and waste heat, and a clear decarbonization focus. Its advantage is the ability to bundle development, operation, and low-carbon sourcing into a single value proposition, which is appealing to municipalities and institutional clients that want emissions reduction outcomes without managing multiple vendor relationships. Veolia’s positioning suggests a strategy centered on asset development and long-term service contracts tied to sustainability performance.
Fortum illustrates the operator-as-system-integrator model, running heating and cooling networks while capturing waste heat from data centers and targeting carbon-neutral supply by 2030. The recent start of operations at large-scale heat pump plants that draw on data center excess heat demonstrates a strategy of turning adjacent industrial heat into a competitive supply advantage. By combining operational scale with innovative sourcing, Fortum shows how a regional operator can build differentiation through source diversification and decarbonization commitments.
ENGIE operates a broad international footprint, with hundreds of heating networks and a substantial number of cooling networks across multiple countries, alongside significant heat and cooling production capacity. Its strategy appears oriented toward scale, international replication, and strategic partnerships that extend network reach into institutional and commercial demand pools. Recent concession activity securing long-term rights for green district heating network expansion and partnership expansions for sustainable cooling delivery indicate a focus on securing multi-year growth pipelines through public-sector and institutional collaboration.
Emicool represents a regionally concentrated but strategically important cooling operator, with large-scale plant assets and an emphasis on energy-efficient cooling supply. In high-cooling-load environments, operators like Emicool compete on plant efficiency, reliability, and the ability to serve dense commercial and residential zones with centralized chilled water infrastructure. Its relevance highlights the importance of regional specialization: in markets where cooling dominates thermal demand, expertise in plant design, load management, and operational efficiency becomes the core competitive battleground.
The broader market trajectory suggests continued evolution along three lines:
- Integration and consolidation. Larger operators are likely to pursue network acquisitions, concession portfolios, and partnership expansions to secure growth corridors and diversify heat and cooling sources.
- Specialization and regional depth. Regional specialists will continue to win in high-demand cooling markets and in niche heating segments where local regulatory, climatic, or industrial conditions create durable advantages.
- Technology supplier relevance. Manufacturers of control hardware, heat exchangers, and substation skids will gain importance as networks become more complex and operators seek standardized, monitorable, and efficient component ecosystems.
New entrants are most likely to appear where data center heat recovery, geothermal integration, or grant-funded renewable network development create viable project structures. However, successful entry typically requires access to land-use coordination, financing, and operational expertise, not merely technology capability.
Future Trends and Commercial Opportunities for the Next 3-5 Years
Several trends are likely to define the medium-term market, each carrying distinct commercial implications.
Underfloor Heating Market
Trend 1: Multi-source thermal integration becomes standard. Networks will increasingly combine waste heat from industrial and data center operations, geothermal, biomass, and large-scale heat pumps within unified control frameworks. This trend creates opportunities for operators that can secure heat supply agreements, for technology providers that enable source-agnostic control and balancing, and for financiers that structure projects around diversified thermal supply contracts. A practical commercial pathway is to align heat sourcing with urban and industrial land-use planning, ensuring that new heat loads are identified before network expansions are finalized.
Trend 2: Policy-driven decarbonization expands public funding and concession availability. Continued regulatory tightening and dedicated funding instruments will support projects that demonstrate renewable share growth and measurable emissions reductions. The commercial opportunity is not only in capturing grants but in designing projects that qualify for sustained support and that can be replicated across multiple municipalities. Developers that standardize project templates—combining proven sourcing, standardized substation and valve assemblies, and measurable performance reporting—can reduce delivery risk and improve scalability.
Trend 3: Cooling infrastructure scales as a strategic asset class. In high-temperature and high-density environments, district cooling will increasingly be treated as critical infrastructure rather than an optional convenience. Large-capacity plants and campus-linked cooling expansions indicate a pipeline of demand that favors operators with strong plant efficiency, reliable chilled water distribution, and the ability to integrate with building-level efficiency programs. Suppliers that support optimized heat exchange, cold storage integration, and load forecasting can differentiate within this pipeline.
Risk considerations. Deployment timelines can slip if permitting, material availability, or interconnection sequencing become constrained. Performance claims tied to renewable share or emissions reduction may face scrutiny if measurement methodologies evolve or if supply conditions change. In addition, rapid expansion without strong operational control can create balancing issues that undermine efficiency and customer satisfaction. Commercial planning should therefore incorporate contingency thinking around permitting, component standardization, and post-commissioning maintenance capacity.
Strategic Actions for Decision-Makers
Different stakeholders face different priorities, but all benefit from a clear view of where value is created in the thermal infrastructure value chain. The following actions are most relevant in the current environment.
Heat Cost Allocator Market
For Equipment Manufacturers and Technology Providers
Prioritize standardization and integration support. Substation skids, control valves, and heat exchangers that can be deployed repeatedly across multiple networks reduce engineering friction and improve project predictability. Emphasize coordination capabilities that help operators manage multi-source inputs, variable loads, and balancing requirements. Where possible, align product roadmaps with the growing relevance of waste heat recovery and renewable integration, since those themes are shaping both concession criteria and funding eligibility.
For Investors and Developers
Focus on corridors with aligned policy incentives, identifiable waste-heat sources, and credible long-term demand. Data center-adjacent heating, geothermal-enabled networks, and institutional cooling portfolios represent areas where project structures can combine revenue visibility with decarbonization goals. Evaluate not only technical feasibility but also the availability of grants, concession stability, and the operational capability required to run complex multi-source networks. Projects that can demonstrate repeatable deployment templates will generally attract more favorable capital terms and partnership interest.
For operators and procurement teams, the priority is performance assurance and supply resilience. Select components and partners that support long-term balancing, monitoring, and maintenance rather than lowest-first-cost procurement alone. In cooling-heavy markets, prioritize plant efficiency, redundancy, and load-forecasting capability. In heating markets, emphasize source diversification and control hardware that can accommodate future renewable and waste-heat integration without major redesign.
Across all roles, the strategic value of granular market intelligence is high. Macro trends indicate direction, but concession timelines, funding eligibility details, regional cooling and heating demand patterns, and component-level deployment preferences determine execution success. Decision-makers who can map these details to their own project pipelines, procurement plans, or investment theses are better positioned to move quickly when opportunities appear.
The district heating and cooling market is expanding on the back of policy pressure, multi-source heat integration, and growing recognition of thermal networks as decarbonization infrastructure. Growth will not be uniform; it will concentrate where regulatory support, demand density, and source availability align. For executives and investors, the practical task is to identify where those conditions overlap and to build capabilities—technical, operational, and commercial—that allow participation at the right scale. For those seeking deeper segmentation detail, competitive benchmarking, and tailored strategic recommendations, the full PW Consulting research report provides the supporting data and analysis needed to translate these market signals into concrete action.
For detailed analysis of this topic, please visit the official page: District Heating and Cooling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


