



Shipping Software Market 2026: Decoding the 8.5% CAGR Path to $3.87B

The Shipping Software Market: Strategic Trends and Commercial Opportunities Through 2032
The shipping software market has entered a decisive growth phase, driven by the compounding effects of e-commerce expansion, digital fulfillment mandates, and enterprise modernization programs. Valued at approximately $2.19 billion in 2025, the market has expanded consistently over the past half-decade and is projected to accelerate toward a ~$3.87 billion valuation by 2032, reflecting a compound annual growth rate of 8.5 percent over the 2026–2032 forecast window. This trajectory is not merely a function of volume growth; it signals a structural reorientation in how shippers, logistics providers, and merchant networks orchestrate transportation execution, rate optimization, and customer-facing delivery experiences. The sector is no longer defined by simple label printing or carrier selection. It has evolved into a critical control layer that connects order management, warehouse operations, freight procurement, and post-purchase engagement into a unified operational fabric.
Despite the favorable expansion path, the market is navigating a series of inflection points that will shape competitive outcomes over the next several years. The following analysis examines the forces driving this transformation, maps the strategic positioning of leading participants, and outlines the commercial opportunities and risks that executives and investors should monitor as the landscape matures.
Market Context: Growth Trajectory and Structural Headwinds
The market's expansion over the 2020–2025 period demonstrates resilient demand across multiple buyer segments, with the 2025 valuation establishing a foundation for more aggressive growth in the forecast period. The projected acceleration toward the late 2020s and early 2030s reflects both incremental adoption and deeper enterprise penetration, as organizations move from point solutions to integrated shipping orchestration platforms. Growth is being reinforced by the ongoing shift to cloud-based architectures, which now represent the dominant deployment model, and by sustained demand from commerce-driven fulfillment environments that require rapid carrier selection, automation, and customer visibility.
However, several structural challenges are reshaping how vendors position their offerings and how buyers evaluate procurement decisions. Three dynamics merit particular attention.
Operational Cost Pressure and Infrastructure Economics
Shipping software buyers are increasingly sensitive to total cost of ownership, not only in license or subscription terms but also in the underlying infrastructure and integration costs required to operate at scale. Cloud hosting and infrastructure expenses can range from several hundred to multiple thousands of dollars per month depending on transaction volume and architecture choices, while API usage at scale introduces incremental fee structures that can accumulate quickly as call volumes rise. For enterprises processing high parcel volumes, these operational costs become material line items that influence platform selection, vendor negotiation, and architectural decisions around multi-carrier abstraction layers. The practical implication is that shipping software is no longer evaluated solely on feature breadth; buyers are scrutinizing cost predictability, usage-based pricing transparency, and the efficiency of underlying integration patterns.
Regulatory Shifts and Data Transfer Economics
Changing regulatory frameworks are beginning to influence cloud economics and data handling requirements, with implications for how shipping platforms manage cross-border data flows, carrier integrations, and customer information. Forthcoming requirements such as the EU Data Act, taking effect in early 2027, are expected to affect cloud transfer fees and pricing dynamics for data-intensive workloads. Shipping software that depends on continuous data exchange across carriers, marketplaces, and global fulfillment nodes will need to account for evolving compliance expectations and potential cost shifts tied to data movement. This creates both a compliance burden and a strategic consideration for vendors offering global multi-carrier capabilities, as regulatory alignment increasingly factors into enterprise procurement criteria.
Labor Dynamics, Incident Cost, and Operational Resilience
While shipping software is a technology category, its value proposition is tightly linked to labor efficiency and operational continuity. Workforce spending remains a dominant cost center across logistics-heavy environments, and downtime or incident response can carry significant financial consequences when fulfillment operations are disrupted. Shipping platforms are therefore expected to demonstrate not only automation depth but also reliability, rapid issue resolution, and integration stability. The market is tilting toward solutions that reduce manual intervention, streamline exception handling, and minimize operational friction during peak shipping periods. Resilience is becoming a competitive differentiator.
Core Drivers Reshaping the Shipping Software Landscape
The current growth cycle is being propelled by several interrelated forces. Understanding how these drivers interact provides a clearer view of where value is being created and where competitive advantage is likely to consolidate.
Technology Innovation and API-Centric Architecture
One of the most consequential shifts in the market is the move toward API-first shipping orchestration. Cloud-based shipping APIs now enable rate shopping, label creation, address verification, tracking, and return workflows across hundreds of carriers through standardized integration layers. This architecture reduces development overhead for merchants and platforms that need to connect multiple carriers without building bespoke integrations one by one. It also supports modular adoption, where shipping functionality can be embedded into commerce platforms, order management systems, or fulfillment workflows without requiring a monolithic replacement of existing systems.
The rise of versionless or continuously updated software models further reinforces this trend. Rather than waiting for periodic releases, buyers increasingly expect incremental feature delivery, ongoing carrier rule updates, and dynamic automation capabilities that adapt to changing shipping conditions. At the same time, advanced functionality such as branded tracking, predictive delivery estimates, and returns management is extending the value of shipping software beyond execution into customer experience and post-purchase engagement. This expansion broadens the addressable use case and increases the strategic importance of shipping platforms within the commercial technology stack.
Demand-Side Evolution in Commerce and Fulfillment
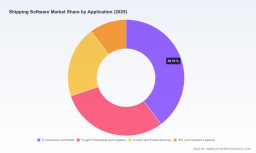
buyer behavior is reshaping requirements on multiple fronts. E-commerce and retail fulfillment continue to exert strong demand for scalable shipping automation, multi-carrier rate optimization, and seamless platform integrations with ecosystems such as Shopify, WooCommerce, and other commerce environments. At the same time, freight forwarding, logistics providers, courier and postal services, and third-party logistics operators are seeking more capable multi-carrier execution tools that can handle mixed parcel and LTL workflows, broker rating, and enterprise system integration.
A notable shift is the growing expectation that shipping software should support brand-consistent delivery experiences and flexible fulfillment choices. Shoppers increasingly expect transparent tracking, accurate delivery estimates, and easy returns, while merchants want to manage carrier selection dynamically based on cost, speed, and service levels. This pushes vendors to integrate rate optimization, delivery promise communication, and post-purchase visibility into a single workflow rather than treating them as separate concerns.
Salon Software Market
Supply Chain Complexity and Multilayer Logistics Requirements
Shipping software is also being reshaped by the increasing complexity of supply chain execution. Organizations are managing more intricate fulfillment networks, cross-region shipping obligations, and hybrid parcel/LTL operations. In this environment, the ability to consolidate carrier management, support enterprise integrations with ERP and warehouse systems, and provide multi-carrier abstraction becomes a practical necessity rather than a convenience feature.
This complexity favors platforms that can act as an intermediate control layer between enterprise systems and carrier ecosystems. For large shippers and logistics service providers, the value lies in reducing fragmentation, standardizing rate and label workflows, and enabling centralized decision-making across carrier options. As a result, the market is seeing heightened interest in solutions that combine parcel execution with broader transportation and supply chain management capabilities, as well as in connectors that link shipping software to major enterprise platforms.
Partnerships, Enterprise Integrations, and Ecosystem Expansion
A growing number of partnerships are extending shipping software reach into enterprise environments. Recent integration activity has connected multi-carrier parcel shipping capabilities with major cloud SCM and ERP ecosystems, enabling organizations to embed shipping execution within broader enterprise workflows. These collaborations are strategically important because they lower adoption friction for large buyers and accelerate deployment in environments where standalone shipping tools would otherwise require extensive customization.
PW Consulting
This ecosystem-oriented approach is also visible in product refinements that target operational specificity, such as expanded automation rules for regional address handling, broker rating enhancements, and multi-carrier support improvements. Rather than positioning shipping software as a static utility, leading vendors are investing in capabilities that adapt to changing carrier rules, regional requirements, and enterprise integration needs. The trend suggests that competitive advantage will increasingly belong to platforms that can combine API flexibility, enterprise connectivity, and ongoing operational updates within a manageable cost structure.
Competitive Dynamics and Strategic Positioning
The shipping software market is characterized by a broad set of participants spanning standalone shipping platforms, API-centric providers, enterprise supply chain vendors, and large technology companies with shipping integrations. Market concentration remains moderate, indicating that no single player dominates the entire landscape, but a cluster of established vendors holds meaningful share through product breadth, carrier relationships, and ecosystem reach.
Differentiation Among Leading Participants
Competitive positioning generally falls along a few distinct axes. Some vendors emphasize multi-carrier rate comparison, label automation, and shipment execution for SMB and mid-market commerce users. Others focus on API-first abstraction layers that let platforms and enterprises integrate shipping functionality at scale. A third group anchors its strategy in enterprise-grade supply chain and transportation management, where shipping execution is part of a broader operational suite. A fourth segment extends into post-purchase experience, using branded tracking and delivery communication as a differentiator that supports customer retention and brand consistency.
- Multi-carrier execution and automation remain foundational. Vendors in this space compete on carrier breadth, rate shopping intelligence, and the ability to handle high-volume fulfillment workflows with minimal manual intervention.
- API and platform integration capabilities are increasingly decisive for technology-forward buyers. Providers that offer clean abstraction layers, address verification, and scalable tracking support can embed themselves more easily into commerce and logistics ecosystems.
- Enterprise integration and ERP alignment create stickiness in larger accounts. Shipping solutions that connect cleanly to enterprise resource planning and warehouse systems reduce operational silos and support consolidated procurement and execution.
- Customer-facing shipping experiences are becoming a competitive lever. Branded tracking, estimated delivery communication, and returns management extend the software's role from operational utility to commercial enablement.
Evolution of the Market Structure
The market appears to be moving toward a dual pattern of consolidation and specialization. On one hand, larger enterprise vendors and well-resourced platform providers are strengthening their positions through integration depth, carrier reach, and broader supply chain alignment. On the other hand, specialized players continue to compete by targeting clearly defined buyer needs, such as e-commerce shipping automation, API-centric parcel orchestration, or post-purchase engagement tools.
New entrants and incumbent expansion both remain viable paths, but the bar is rising. Buyers increasingly expect carrier coverage, integration flexibility, automation depth, and predictable operating costs. As a result, pure point solutions must demonstrate a strong niche advantage or a clear path to integration breadth, while broader platforms must prove they can deliver shipping-specific usability and carrier-level accuracy without becoming overly complex. The competitive frontier is shifting toward solutions that can operate as a reliable intermediary across carriers, enterprise systems, and customer-facing workflows while keeping cost structures transparent.
Recent Moves and What They Signal
Recent industry activity underscores the strategic importance of product continuity, leadership focus, and ecosystem integration. Recognition of leading vendors in shipping software reflects the market's heightened attention to operational reliability and solution maturity. Leadership appointments in sending technology and shipping solutions indicate that organizations are investing in focused management attention for core shipping capabilities. Product updates that expand automation rules, regional support, and broker rating functionality show that vendors are tuning their platforms for practical operational complexity rather than merely adding surface-level features.
Partnership activity connecting multi-carrier parcel shipping with major cloud SCM environments is particularly telling. These moves lower the barrier for enterprises to adopt advanced shipping functionality within existing systems and suggest that integration readiness is becoming a competitive necessity. At the same time, feature launches around broker rating and carrier management point to a wider recognition that shipping software must support nuanced procurement decisions, not just execution. Taken together, these developments indicate a market that is maturing rapidly and rewarding vendors that can combine technical agility with operational relevance.
Forward Outlook: Three Trends to Watch Through 2032
Looking ahead, the shipping software market is likely to be shaped by a small number of high-impact trends. These developments will influence vendor strategy, buyer expectations, and the allocation of investment capital.
Real Estate Software Market
Trend 1: From Execution Tool to Orchestration Platform
Shipping software is increasingly positioned as an orchestration layer rather than a transactional utility. That means broader responsibility for rate optimization, carrier selection logic, exception handling, delivery communication, and returns workflows. Over the next three to five years, platforms that can unify these functions in a configurable, API-accessible architecture will likely capture more enterprise value. The commercial opportunity lies in selling not just shipping labels or rate comparison, but operational control, cost optimization, and customer experience consistency across channels and regions.
The risk here is complexity creep. As platforms broaden their scope, they must preserve usability, carrier accuracy, and deployment speed. Buyers may resist solutions that become too heavy or expensive relative to the value they deliver. The winners will be those that expand capability without sacrificing integration clarity or cost predictability.
Trend 2: Ecosystem Embedding and Enterprise Interoperability
Enterprise adoption will continue to favor shipping software that fits cleanly into broader technology environments. Integration with ERP, cloud SCM, order management, and warehouse systems will be a key enabler of scale, especially for organizations that want centralized governance over carrier selection and fulfillment execution. Partnerships and prebuilt connectors will likely become more important than custom integration work as buyers seek faster time-to-value and lower operational risk.
This creates opportunity for vendors that invest in ecosystem alignment and enterprise-grade reliability. It also raises the stakes for smaller providers that lack integration depth, unless they can win through niche focus, superior developer experience, or distinctive post-purchase capabilities. A practical uncertainty is the pace and consistency of enterprise platform evolution, which can affect integration roadmaps and dependency management.
Trend 3: Cost Transparency, Compliance, and Operational Resilience
As infrastructure and API usage costs become more visible in buyer evaluations, platforms that offer predictable pricing, efficient data handling, and resilient operations will gain an advantage. At the same time, regulatory developments affecting data transfer and cloud economics will require vendors and buyers to plan for evolving compliance obligations. Shipping software that handles cross-border data flows, carrier integrations, and customer information will need to demonstrate both operational efficiency and regulatory awareness.
The commercial implication is that cost structure and compliance readiness will become more differentiated factors in procurement decisions. Buyers will likely favor solutions that make usage economics easier to forecast and that reduce the burden of adapting to new regulatory requirements. The risk side includes potential shifts in cloud transfer costs, API pricing pressure at scale, and the operational impact of downtime or incident response during high-volume periods. Resilience will not be a nice-to-have; it will be part of the value equation.
Strategic Implications for Decision-Makers
The shipping software market offers meaningful opportunities, but the right course of action depends on the role an organization plays in the value chain. The following recommendations are intended to translate market dynamics into practical strategic choices.
For Shipping Software Vendors and Technology Manufacturers
Product strategy should emphasize orchestration breadth without sacrificing integration simplicity. vendors that can combine multi-carrier execution, API accessibility, enterprise interoperability, and customer-facing delivery tools will be better positioned to capture expanding demand across commerce, logistics, and enterprise segments. Equally important is cost structure discipline: usage-based economics, cloud hosting assumptions, and API fee exposure should be modeled clearly so that pricing remains competitive as transaction volumes grow.
Investment in automation depth and operational adaptability also deserves priority. Regional address handling, broker rating, carrier rule changes, and peak-season operational needs are not edge cases; they are central to reliable fulfillment at scale. Vendors that keep pace with these requirements while maintaining a clear developer and administrator experience will strengthen their competitive standing.
For Investors and Strategic Allocators
The market's 8.5 percent CAGR trajectory and expanding enterprise penetration suggest continued demand, but differentiation will matter more over time. Investors should look beyond headline growth and assess whether a company has durable advantages in carrier relationships, integration ecosystems, automation depth, or post-purchase engagement. Concentration dynamics indicate room for both scaled incumbents and specialized challengers, but long-term winners are likely to be those that can defend margins while expanding scope.
It is also prudent to monitor operating cost exposure and compliance readiness as selection criteria that may influence churn, expansion, and competitive displacement. Companies that can articulate a clear path to efficient scale, predictable cost profiles, and resilient operations will generally present stronger investment theses than those relying primarily on feature volume.
For Procurement Leaders and Enterprise Buyers
Buyers should evaluate shipping software as a strategic operational layer, not merely a transactional tool. Key evaluation criteria should include carrier coverage, integration compatibility with existing ERP or cloud SCM environments, automation capabilities for rate selection and fulfillment workflows, and the predictability of ongoing usage costs. Post-purchase functionality such as branded tracking and returns management should be assessed for their contribution to customer experience and operational efficiency, not treated as optional extras.
Given the pace of change in carrier rules, regulatory expectations, and enterprise integration patterns, buyers should also prioritize vendors with a demonstrated ability to update product capabilities and maintain interoperability over time. Selecting a platform that can grow with the organization while keeping cost and complexity under control will reduce the risk of future rework or displacement.
Conclusion
The shipping software market is entering a period in which growth, complexity, and strategic differentiation are converging. Demand is being sustained by commerce expansion, enterprise modernization, and the need for more capable multi-carrier execution and visibility tools. At the same time, buyers are becoming more discriminating about cost transparency, integration readiness, regulatory alignment, and operational resilience. For vendors, the opportunity lies in building platforms that combine API flexibility, enterprise interoperability, and customer-facing delivery value without allowing cost or complexity to erode competitiveness. For investors and buyers, the priority is to identify solutions and partners that can scale efficiently while adapting to a rapidly changing operational and regulatory environment.
Given the breadth of segmentation, regional variation, and evolving enterprise requirements across the shipping software landscape, detailed segmentation data and tailored commercial assessment can help decision-makers move from high-level trends to specific procurement, investment, and product decisions. PW Consulting's full research report provides deeper coverage of market segmentation, competitive positioning, and actionable recommendations designed to support planning across vendor, investor, and buyer perspectives.
For detailed analysis of this topic, please visit the official page: Shipping Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


