



Contact Image Sensor Market: What the 7.2% CAGR and 2032 $2.5B Trajectory Really Mean

The Contact Image Sensor Market: Navigating Structural Shifts and Strategic Growth Trajectory Through 2032
Market Landscape and Critical Inflection Points
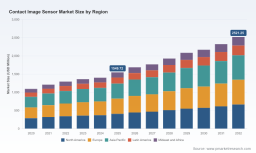
The Contact Image Sensor market has transitioned from a mature, incremental growth phase into a period of strategic redefinition. Revenue crossed the 1.5 billion USD threshold in the 2025 base year, building on a steady upward trajectory from approximately 1.09 billion USD in 2020. The expansion has been broad-based, with consistent year-over-year gains reflecting steady adoption across imaging, document handling, and industrial inspection workflows. Projected forward through 2032, the market is expected to reach roughly 2.52 billion USD, underpinned by a compound annual growth rate of 7.2 percent. This growth profile signals more than legacy replacement cycles; it indicates structural demand formation tied to digitization, automation, and quality control imperatives across multiple verticals.
Within this trajectory, the market exhibits a balanced spatial distribution across developed and emerging economies, with North America, Europe, and Asia Pacific each contributing meaningfully to aggregate demand. Type segmentation shows monochrome and color imaging maintaining substantial and relatively comparable footprints, reflecting a market where application requirements, rather than pure technology preference, dictate adoption. On the application side, scanners and copy machines continue to anchor volume, while surface inspection systems and banknote readers represent higher-value, specification-driven segments. The concentration profile remains notably consolidated, with the top three participants capturing a disproportionate share of revenue and the top five commanding an even larger portion of total market activity. This structure shapes pricing dynamics, innovation pacing, and the strategic options available to both incumbents and new entrants.
Despite the favorable growth math, the industry is passing through a set of inflection points that will determine which participants capture disproportionate value over the next several years.
1. The Shift From Commodity Imaging to High-Specification Inspection
The market is no longer driven primarily by basic document digitization. Instead, a growing portion of demand is migrating toward inspection-grade performance, where resolution, line speed, contrast handling, and dimensional repeatability matter more than unit cost alone. This shift changes the value equation for Contact Image Sensors: devices that once competed on price and availability must now demonstrate imaging fidelity, environmental robustness, and integration readiness. Suppliers that treat the sensor as a commoditized component risk being squeezed into low-margin volume streams, while those that align performance with application-specific tolerances can command stronger positioning.
2. Integration Complexity as a Competitive Moat and Barrier
As end systems become more compact and performance expectations rise, the sensor is increasingly evaluated as part of a broader optical and electrical subsystem rather than as an isolated component. Illumination design, signal processing, module form factors, and OEM integration support are becoming integral to commercial success. This creates a higher bar for market entry and rewards companies that can deliver complete, validated solutions rather than discrete sensor SKUs. At the same time, it places pressure on assembly, calibration, and support capabilities, which can erode differentiation if not managed deliberately.
3. Regulatory and Export Control Sensitivities Emerging in High-Performance Segments
Performance-driven adoption is beginning to intersect with trade and export control considerations. Equipment and sensing technologies capable of sub-micron surface repeatability or high-accuracy measurement are increasingly subject to regulatory scrutiny in select jurisdictions. While this does not constrain the entire Contact Image Sensor market, it introduces a meaningful overlay for high-specification machine vision and inspection applications. Companies operating in these segments must anticipate compliance requirements earlier in product development, rather than treating them as post-design checks.
Key Drivers Shaping Market Trajectory
The 7.2 percent growth path through 2032 is not a uniform expansion. It is being shaped by a combination of technology, regulation, demand behavior, and supply-side economics that reward participants who align their roadmaps with where value is actually forming.
Technology Innovation and Performance Leapfrogging
Innovation in Contact Image Sensors is increasingly centered on resolution, line rate, and dynamic range, particularly for inspection and machine vision use cases. The push toward higher dpi and extended scan lengths is enabling more demanding defect detection, surface characterization, and print-quality verification tasks. Recent product expansion from Teledyne DALSA illustrates this direction clearly: the extension of its AxCIS family with new 1,800 dpi and 1,500 mm models, delivering monochrome line rates up to 80 kHz with HDR capability, reflects a market moving toward faster, higher-fidelity line-scan imaging for semiconductor wafer, battery, and print inspection. This type of advancement does more than add specification points; it expands the addressable set of applications where Contact Image Sensors can compete against alternative imaging architectures.
Equally important is the growing emphasis on customization and color capability. CMOS Sensor Inc’s focus on custom-designed Contact Image Sensors supporting color imaging and diverse application needs underscores a parallel trend: differentiation is increasingly tied to tailoring sensor characteristics to specific workflows. In a consolidated market, the ability to adapt resolution, color response, and integration parameters can be the difference between being specified in a system design or being bypassed by a more flexible alternative.
Regulation, Compliance, and the Redefinition of Eligible Applications
Policy and trade controls are becoming a more visible factor in how high-performance sensing technologies are deployed and sold. Canada’s Export Control List, updated in May 2025, includes sensors and lasers in Category 6 with specific clauses for equipment capable of measuring surfaces with sub-micron repeatability or 0.5 mm accuracy. This does not halt market growth, but it does introduce a segmentation effect: some high-specification inspection applications will require additional compliance consideration, documentation, and channel discipline. For suppliers, the practical implication is that performance leadership must be paired with regulatory literacy, especially where accuracy and repeatability become selling points. For buyers, it means that sourcing strategies need to account for documentation, origin, and end-use classification more carefully than in the past.
Demand-Side Evolution: From Office Imaging to Industrial and Security Workflows
A major driver of sustained demand is the broadening of application contexts beyond traditional document handling. Scanners and copy machines remain substantial demand anchors, but surface inspection systems and banknote readers represent segments where the sensor is tied to operational integrity, security, and quality assurance. In these environments, imaging is not a convenience feature; it is a control function. That shift increases the willingness to invest in sensor performance and reliability, while also raising the cost of failure.
At the same time, large-format document and print workflows continue to create niche but strategically meaningful demand. ColorTrac’s focus on CIS-based large-format scanners for wide-format printing and document handling points to a segment where scan width, document handling, and imaging consistency matter more than aggressive cost reduction. This kind of application specialization often offers steadier margins than high-volume commodity scanning, especially where the sensor is tightly coupled to a defined system architecture.
Supply Chain and Cost Structure Realignment
Cost dynamics are being reshaped by both component-level innovation and broader supply-chain realignment. On one hand, advances in CMOS sensor ICs and illumination integration allow higher performance without necessarily increasing system complexity in a linear fashion. On the other hand, the consolidation of supply around a limited number of capable providers means that continuity, qualification, and long-term availability are becoming strategic purchasing considerations. The market’s concentration profile means that buyers cannot assume frictionless switching between suppliers; qualification cycles, firmware or interface compatibility, and support arrangements can create real sticking points.
A significant structural signal comes from Mitsubishi Electric Corporation, which issued a notice of Contact Image Sensor business transfer to affiliated Miyoshi Electronics Corporation effective April 1, 2028, with production relocation and a long-term customer supply commitment. This type of organizational move matters because it signals how incumbents are restructuring their manufacturing and support footprint to preserve continuity while repositioning operational control. For customers and partners, the key question is not whether supply will continue, but how transition timing, production relocation, and documentation will be managed without disrupting qualification or field performance.
Cmos Image Sensor For Adas Market
Competitive Landscape and Emerging Strategic Postures
The Contact Image Sensor market is defined by a small group of capable players with distinct differentiation strategies. Rather than competing solely on price, leading participants are carving out positions based on performance class, integration support, application specialization, and continuity assurance. This creates a landscape where strategic advantage is less about being the largest sensor vendor and more about being the most reliable solution partner for specific high-value application sets.
Incumbent Performance Leadership and Application Alignment
Mitsubishi Electric Corporation has built its positioning around high-performance Contact Image Sensors with original CMOS sensor ICs and illumination solutions aimed at surface inspection, copy machines, and banknote applications. The emphasis on original ICs and illumination integration indicates a strategy centered on controlling critical subsystems rather than assembling interchangeable parts. This approach aligns well with inspection and security-oriented applications where image consistency and lighting uniformity directly affect system performance. At the same time, the announced business transfer to Miyoshi Electronics Corporation reflects a long-cycle move to reorganize production and supply responsibility while preserving customer commitments. For the market, this suggests continuity in the near term, but also an evolving ownership and operational structure that participants should monitor as the 2028 transition approaches.
High-Speed Line-Scan Focus for Machine Vision
Teledyne DALSA has positioned itself around high-speed, high-resolution integrated line-scan Contact Image Sensors for machine vision inspection, with the AxCIS family targeting semiconductor wafer, battery, and print applications. The company’s recent expansion into 1,800 dpi and 1,500 mm models with 80 kHz monochrome line rates and HDR reinforces a strategy aimed at the upper end of performance requirements. This is a meaningful competitive posture because it ties product leadership directly to inspection scenarios where speed and resolution translate into throughput and defect-detection confidence. In a market where some volumes remain price-sensitive, this focus allows Teledyne DALSA to compete on specification-driven value rather than pure unit economics.
Customization and OEM-Ready Integration as Differentiators
CMOS Sensor Inc and FRAMOS GmbH represent a different but complementary set of strategic angles. CMOS Sensor Inc emphasizes custom-designed Contact Image Sensors with support for color imaging and application-specific customization, positioning flexibility as a commercial advantage where standard SKUs do not fully match system requirements. FRAMOS GmbH focuses on integration of high-quality CIS modules into compact scanning and machine vision systems, including electrical and optical specification support and OEM equipment compatibility. Together, these profiles highlight an important market reality: in a consolidated environment, many wins are decided by integration ease, specification tailoring, and the ability to reduce time-to-deployment for equipment manufacturers.
PW Consulting
Application-Locked Niche Positioning
ColorTrac’s CIS-based large-format scanners for wide-format printing and document handling demonstrate the value of application-locked specialization. In wide-format workflows, scan width, mechanical handling, and imaging consistency can be more decisive than marginal sensor cost differences. This kind of positioning can be resilient because it is tied to a defined use case with limited substitution, although it also depends on continued demand in the underlying printing and document-handling segments.
Market Structure Evolution: Consolidation, Selective Specialization, and Entry Risk
The market’s concentrated revenue distribution implies that broad-based new entry will face meaningful barriers. Qualification cycles, integration support demands, and the established relationships between sensor suppliers and equipment manufacturers all raise the bar for entry. At the same time, the landscape is not static. There is room for selective specialization, especially where a new or expanding participant can match a high-specification requirement, provide better integration support, or offer a more flexible customization model for a defined application set. The more probable structural evolution is not a wholesale reshuffling of leaders, but a continued sorting of the market into performance-driven inspection segments, integration-heavy OEM relationships, and application-specialized niches. Consolidation pressure may intensify where scale, qualification depth, and supply continuity matter most, while differentiation opportunities remain stronger where customization and application alignment are valued over pure volume.
Outlook: Three Strategic Trends for the Next Three to Five Years
Trend 1: Inspection-Grade Imaging Will Become the Core Growth Engine
Over the next several years, the most attractive growth pocket is likely to remain inspection and machine vision applications, where resolution, speed, and dynamic range translate directly into operational value. This trend favors suppliers that can deliver repeatable high-performance modules and the surrounding support needed for industrial integration. The commercial opportunity lies not only in selling sensors, but in enabling end systems that can justify higher specification investment through improved defect detection, throughput, and audit readiness.
The associated risk is performance overreach without application fit. Specifying sensors for the highest available resolution or line rate does not automatically produce better outcomes if illumination, processing, or mechanical constraints are not addressed in tandem. In inspection-driven segments, the winners are likely to be those who can align sensor capability with system-level tolerances and validation requirements.
Trend 2: Long-Cycle Supply Continuity and Organizational Restructuring Will Shape Purchasing Confidence
As production footprints and business structures evolve among major participants, supply continuity will become an increasingly prominent purchasing criterion. The Mitsubishi Electric-to-Miyoshi Electronics transfer is a clear example of how incumbents may reorganize manufacturing responsibility while attempting to preserve long-term supply commitments. For buyers, this creates both reassurance and planning complexity: continuity is intended, but transition timing, engineering support, and documentation will need active management.
Strategically, this trend increases the value of supplier stability, qualified second sources where feasible, and clear roadmap visibility. For participants on the supply side, the opportunity lies in making transitions predictable and minimizing qualification disruption. The uncertainty is that organizational changes can alter support models, response times, and regional availability even when nominal supply continues.
Trend 3: Regulation Will Act as a Segment Filter Rather Than a Market-Wide Constraint
Trade and export-control developments are likely to function as a segmentation mechanism, particularly influencing high-accuracy, sub-micron-class inspection applications. The practical effect is not a blanket slowdown, but a need for earlier compliance consideration in product definition, documentation, and channel strategy. Companies that proactively address classification and end-use considerations will encounter fewer surprises when targeting high-specification projects across multiple regions.
Worldwide 3D Image Sensor Market
The risk here is complacency. As accuracy and repeatability become stronger competitive differentiators, the same attributes can attract regulatory attention. This creates a feedback loop in which performance leadership must be matched by compliance readiness, especially for suppliers and buyers operating in cross-border equipment programs.
Actionable Implications for Decision Makers
For Equipment Manufacturers and Integrators
Treat sensor selection as a system-level decision rather than a discrete component purchase. In inspection and high-specification scanning applications, prioritize suppliers that can support illumination integration, module form factors, electrical and optical specification alignment, and OEM deployment needs. Where applications require color imaging or specialized customization, evaluate flexibility and development support early, because late-stage adaptation can erode time-to-market advantages.
Also, build continuity planning into sourcing strategy. In a concentrated market, switching costs are not just pricing-related; they include qualification, compatibility, and support dependencies. Mapping transition risk, including production relocation or business structure changes, should be part of long-term procurement planning.
For Investors and Strategic Partners
Look beyond headline market size and focus on where specification-driven value is forming. The most compelling exposure is likely in segments where imaging performance directly affects quality, security, or throughput, and where integration support is a meaningful part of the commercial proposition. In those areas, differentiation is less fragile than in commoditized scanning volumes, and competitive position can be more durable when tied to application lock-in and validation requirements.
At the same time, monitor organizational and supply-chain transitions among leading participants. Restructuring can create both opportunity and risk, depending on how smoothly production, support, and documentation are managed. The strategic question is whether a transition strengthens continuity or introduces uncertainty in qualification and service.
For Procurement and Operations Leaders
Strengthen qualification frameworks and documentation expectations, especially for higher-accuracy and inspection-oriented deployments. Where regulatory sensitivity may apply, coordinate early with internal compliance and trade-control functions so that accuracy and repeatability claims do not create unintended classification exposure. Establish clearer criteria for supplier stability, support responsiveness, and long-term availability, since these factors will increasingly determine operational resilience in a concentrated market.
Finally, avoid assuming that specification parity equals substitutability. Two sensors may appear similar on a datasheet while differing substantially in integration effort, support model, or transition risk. Procurement decisions that incorporate total deployment cost and continuity risk are better positioned than decisions based solely on unit price or headline performance.
The Contact Image Sensor market is moving into a phase where growth is increasingly tied to performance specificity, integration readiness, and supply continuity rather than broad volume expansion alone. That shift creates clearer routes to differentiation for participants who align their capabilities with the right application sets, but it also raises the stakes for buyers who must navigate consolidation, transition planning, and emerging regulatory considerations. For decision makers seeking detailed segment splits, regional revenue structures, concentration analysis, and company-level tracking through 2032, a full scope market intelligence report can provide the more granular framework needed to translate these trends into concrete sourcing, investment, and product decisions.
For detailed analysis of this topic, please visit the official page: Contact Image Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


