



Robot Tool Changers Market 2026: The Real Drivers Behind a 13.81% Growth Trajectory

The Strategic Shift in Robot Tool Changers: Navigating a High-Growth Market
Market Overview: A Sector Accelerating Under Industrial Automation Demand
The global market for robot tool changers has entered a phase of sustained expansion, driven by the broader adoption of industrial automation and the increasing need for flexible manufacturing systems. Valued at approximately 543.55 million USD in 2025, the market has demonstrated consistent growth over the past five years, rising from 284.67 million USD in 2020. This trajectory reflects a compound annual growth rate of 13.81 percent through 2032, signaling that tool changing systems are no longer peripheral components but strategic enablers of production efficiency. The market is projected to reach 1.35 billion USD by 2032, a figure that underscores the compounding effect of automation investments across multiple sectors.
This growth is not uniform across all geographies or applications. Demand is concentrated in regions with mature automation ecosystems and in industries where rapid changeover times directly impact throughput. The current market structure reflects a balance between established industrial robotics hubs and emerging manufacturing centers that are integrating robotic cells at an accelerating pace. While the numbers illustrate a clear upward path, the underlying dynamics reveal a market that is selectively rewarding players who can align product capabilities with shifting operational requirements.
Two structural shifts are reshaping the competitive baseline. First, the transition from fixed, single-purpose end-of-arm tooling toward modular, quickly interchangeable systems is becoming a default expectation rather than a premium feature. Second, the integration of tool changing mechanisms with collaborative robots and light automation cells is expanding the addressable use cases beyond traditional heavy manufacturing. These shifts are forcing suppliers to reconsider design priorities, safety alignment, and deployment speed.
Key Challenges and Inflection Points
Despite the favorable growth outlook, the market faces operational and strategic tensions that will determine which participants capture disproportionate value. Three challenges stand out as particularly consequential for decision-makers evaluating this space.
Safety Standardization as a Compliance and Design Gatekeeper
Updated global safety requirements, including ISO 10218-2:2025 for industrial robot systems and the continued relevance of ANSI/RIA R15.06-2012 Part 2 for completed machinery integration in the United States, are reshaping how tool changers are specified and deployed. These standards are not merely documentation exercises; they influence interface design, fail-safe behavior, detection of unintended contact, and system-level integration. Manufacturers that treat compliance as an afterthought risk costly redesign cycles, slower qualification processes, and reduced appeal to OEMs seeking plug-and-play compatibility. Conversely, suppliers that embed safety alignment into product architecture can shorten customer validation timelines and strengthen positioning in regulated environments such as medical device production, food processing, and automotive assembly.
Cost Pressures and Regional Supply Chain Realignment
Tool changer manufacturers are navigating a cost environment shaped by component pricing volatility and shifting trade dynamics. U.S. tariff policies, for example, are prompting localized supply chain adjustments among major manufacturers of robotic components. This restructuring affects lead times, sourcing strategies, and the economics of cross-border distribution. Companies that rely heavily on single-source components or centralized production footprints may face margin compression or delivery uncertainty. At the same time, customers are increasingly sensitive to total cost of ownership, including maintenance, downtime during changeovers, and the speed with which a new end-effector can be deployed. The market is therefore moving toward an environment where reliability and serviceability are as commercially important as the initial purchase price.
Balancing Automation Gains with Practical Deployment Complexity
A recurring tension in this market is the gap between the promise of faster changeovers and the reality of integration effort. Automatic tool changers can reduce manual intervention and improve cycle consistency, but they also introduce requirements around alignment, actuation reliability, air and electrical pass-throughs, and control coordination. For many mid-sized manufacturers, the decision is not simply whether to adopt automation but how much complexity they are prepared to absorb. This creates a split in demand: some buyers prioritize fully automatic solutions with integrated sensing and robust retention features, while others opt for manual or semi-automatic systems that are easier to retrofit and maintain. Suppliers that can reduce deployment friction, whether through modular configurations, clear compatibility roadmaps, or application-specific guidance, are better positioned to convert interest into installed base growth.
PW Consulting Automotive & Machinery Research Center
Core Drivers of Market Change
The expansion of the robot tool changer market is being propelled by a combination of technological progress, regulatory evolution, demand-side behavior, and supply chain restructuring. Understanding these drivers individually and in combination provides a clearer view of where growth is likely to concentrate.
Technological Innovation and Payload Flexibility
Product development is increasingly focused on broadening payload compatibility, improving retention reliability, and simplifying integration. Automatic systems are being designed with ISO-standard flange compatibility and modular configurations, allowing them to serve a wider range of robot platforms without extensive custom engineering. Pneumatic actuation remains a practical choice for many applications, especially where simplicity and robustness are valued, while sensing and end-effector accessories are increasingly used to support precision tasks and force-sensitive operations. The introduction of automatic tool changer lines aimed at reducing manual changeovers in machine tending automation illustrates how suppliers are targeting the practical pain points of repetitive loading and unloading. These developments matter because they lower the barrier to re-tooling and help manufacturers shift from dedicated single-product cells to more adaptable layouts.
Regulatory and Safety Environment
The regulatory backdrop is both a constraint and a catalyst. As safety requirements become more explicit and harmonized, customers are paying closer attention to certified integration paths and documented performance under failure conditions. This environment favors suppliers that can demonstrate consistent quality, traceable manufacturing practices, and alignment with recognized robot system standards. In practice, safety compliance is becoming part of the commercial argument: it reduces risk for integrators, supports faster approval in regulated industries, and can differentiate products in tenders where system reliability is a priority. The effect is most visible in sectors where uptime and repeatability are closely tied to product quality and audit readiness.
Demand-Side Behavior and Workforce Dynamics
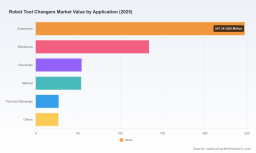
On the demand side, manufacturers are responding to chronic labor shortages, the need for faster changeovers, and the desire to redeploy assets as product mixes change. Tool changers enable robots to switch between tasks without extensive downtime, which is particularly valuable in environments where batch sizes vary or where multiple operations are consolidated into a single cell. Collaborative robot applications are also expanding the user base, since lighter and more flexible tooling solutions can be introduced in spaces where traditional industrial robots would be impractical or overly complex. This demand behavior is widening the market beyond large-scale automotive and electronics operations into chemical processing, medical manufacturing, and food and beverage production, where hygiene, precision, and quick reconfiguration are increasingly important.
Supply Chain and Cost Structure Evolution
Supply chain dynamics are influencing both product strategy and customer purchasing behavior. As manufacturers of robotic components adjust to new tariff and sourcing realities, there is growing interest in regional availability, shorter logistics paths, and locally supported service networks. For tool changer suppliers, this creates an opportunity to compete not only on product features but also on responsiveness and continuity of supply. Customers in turn are weighing the stability of their supplier relationships more heavily, especially when a tool changer is embedded in a production line where downtime has a direct financial impact. The result is a market where service coverage, spare parts availability, and local engineering support can be decisive factors in winning and retaining business.
Competitive Landscape and Strategic Positioning
The robot tool changer market is moderately concentrated, with a small group of established players accounting for a significant share of revenue. This concentration reflects the importance of product maturity, application knowledge, and long-term customer relationships in a segment where reliability and compatibility are paramount. At the same time, the landscape is evolving as suppliers differentiate around payload class, actuation method, collaborative robot compatibility, and deployment speed.
Several companies illustrate distinct strategic approaches. Stäubli has positioned its offering around automatic tool changers with defined payload capacity and modular configurations, emphasizing compatibility with industrial robots and standardized flanges. Zimmer Group provides a broader portfolio that spans automatic, manual, pneumatic, and magnetic solutions, aligning its product range with the need for manufacturing flexibility and productivity across different operating environments. SCHUNK continues to emphasize pneumatically actuated automatic tool changers with integrated retention features for air-loss scenarios, alongside quick-change systems that support faster changeovers. These design choices reflect a shared focus on robustness and practical reliability, but they also reveal different priorities in how each company addresses failure modes and integration complexity.
In the collaborative and lighter-automation segment, other players have carved out niches by focusing on ease of deployment and end-of-arm tool compatibility. SMC Corporation manufactures pneumatic tool changers and grippers suited to collaborative robots and broader automation systems, while Destaco develops cobot end-of-arm tools and manual changeovers with pass-through air and electric ports for materials handling and manufacturing tasks. Robot System Products offers a tool changer family tailored to collaborative robots with automated exchange capabilities, and SmartShift Robotics promotes a universal tool changer system designed for fast deployment and redeployment of tools on robots. ATI Industrial Automation rounds out this competitive picture by specializing in robotic tool changers, multi-axis force and torque sensing, and end-effector accessories for industrial applications, highlighting the increasing importance of sensing and precise control in higher-value use cases.
Worldwide Tool Changers Market
The strategic lesson from this landscape is that differentiation is increasingly tied to the intersection of product design and deployment experience. Companies that combine compatible mechanical interfaces with clear guidance on integration, safety alignment, and maintenance are better positioned to win across both large industrial accounts and smaller automation projects. At the same time, the market shows signs of both consolidation and fragmentation. Incumbents with broad portfolios can leverage cross-selling and entrenched relationships, while smaller or more focused players can win in specific applications by addressing changeover speed, collaborative robot fit, or rapid redeployment needs. New entrants and product-line expansions are likely to persist as long as demand continues to grow and as long as manufacturers seek tools that can be adapted quickly to changing production requirements.
Recent Developments as a Signal of Direction
Recent activity in the market reinforces the emphasis on practical changeover reduction and machine tending automation. In May 2025, SCHUNK USA promoted its CPS automatic tool changer line as a solution for manual changeovers in machine tending automation. This type of development is notable because it targets a recurring operational bottleneck rather than a purely niche application. It also signals that automatic changeover systems are being marketed not only as high-end industrial upgrades but as accessible improvements for repetitive machine tending tasks. For competitors and buyers alike, such announcements highlight where commercial attention is moving: toward reliability in routine use, reduced intervention, and solutions that can be integrated without extensive reconfiguration of existing equipment.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, three trends are likely to shape how the robot tool changer market evolves and where commercial opportunities emerge.
Trend 1: Broader Adoption of Automatic Changeover in Mid-Complexity Applications
Automatic tool changers will increasingly move beyond the largest, most heavily engineered installations and into mid-complexity environments where changeover frequency and labor constraints make manual intervention costly. As modular interfaces and standardized compatibility become more common, the effort required to specify and integrate automatic systems should decline. The commercial opportunity here lies in application-specific packages that address machine tending, light assembly, and repetitive load/unload tasks with minimal customization. The risk is that overstating automation benefits without accounting for integration readiness could lead to slower adoption in settings where maintenance capacity or control integration is limited.
Trend 2: Safety and Compliance as a Competitive Filter
Updated safety expectations will continue to act as a filter in procurement decisions, especially in regulated industries and in projects that require integration with completed machinery. Suppliers that proactively align product design with current standards and that can provide clear documentation and integration support will have an advantage in qualification speed and customer confidence. This trend creates opportunity for companies that can package compliance, reliability, and ease of integration into a coherent value proposition. The uncertainty lies in how quickly standards are adopted across regions and customer segments, since uneven uptake may create temporary fragmentation in approval requirements and system specifications.
Automatic Tool Change Spindle Market
Trend 3: Regional Supply Strategies and Service-Led Competition
As manufacturing of robotic components adjusts to tariff and sourcing pressures, regional availability and service continuity will become more important in supplier selection. Tool changer providers that can offer localized support, predictable lead times, and accessible spare parts will be better positioned to retain customers in cost-sensitive or uptime-critical environments. This trend favors businesses that treat after-sales capability as part of the core offering rather than a secondary function. The risk is that supply chain restructuring could temporarily disrupt availability or increase costs during transition periods, which may affect both suppliers and end users that depend on steady component flow.
Strategic Implications for Decision-Makers
For executives, planners, and investors evaluating this market, the most useful question is not whether growth will continue, but where the most defensible value can be created. The following considerations can help translate market dynamics into action.
For Manufacturers and System Integrators
- Prioritize compatibility and standardization in tooling selection. Systems that align with common flanges, actuation methods, and control interfaces reduce integration risk and make future reconfiguration easier.
- Treat safety alignment and documentation as part of product design rather than a final checklist. This can shorten qualification cycles, improve integrator confidence, and support expansion into regulated applications.
- Evaluate total cost of ownership beyond purchase price, including downtime during changeovers, maintenance complexity, and the speed of redeployment when production needs shift.
For Investors and Strategic Planners
- Pay attention to companies that combine product breadth with strong application support and service coverage, since these attributes tend to drive repeat business and reduce switching in a concentrated market.
- Monitor how suppliers are positioning around collaborative robots, machine tending, and quick redeployment, as these areas are expanding the user base beyond traditional heavy industrial automation.
- Assess exposure to regional supply chain shifts and component sourcing strategies, because tariff and logistics responses can influence margins, delivery reliability, and competitive positioning over time.
For Procurement and Operations Leaders
- Define requirements around changeover frequency, payload, failure-mode behavior, and integration constraints before evaluating specific products, so that selection reflects operational realities rather than feature lists alone.
- Consider how easily a tool changer can be maintained, recalibrated, and redeployed, especially if future production programs are expected to vary in scope or volume.
- Validate supplier support capabilities, including spare parts availability and engineering responsiveness, since service continuity can be as important as initial performance in production-critical environments.
Conclusion
The robot tool changer market is expanding in line with the broader shift toward flexible automation, but the real strategic story lies in how that growth is being shaped by safety requirements, deployment complexity, and supply chain adjustments. Over the next several years, value will likely accrue to suppliers and adopters who can combine mechanical reliability with practical integration, compliance readiness, and dependable support. For decision-makers, the most effective approach is to treat tool changing systems as long-term operational assets rather than interchangeable accessories, and to evaluate them against the specific changeover, payload, and integration demands of each application. Continued attention to product evolution, regulatory alignment, and regional supply dynamics will be essential for those seeking to capture the commercial opportunities embedded in this accelerating market. More granular segmentation, competitive benchmarking, and scenario analysis are available in the full market report for teams that need detail beyond the strategic overview.
For detailed analysis of this topic, please visit the official page: Robot Tool Changers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


