



Industrial Energy Management System Market: Why 8.27% CAGR 2026-2032 Changes Everything

The Industrial Energy Management System (IEMS) Market: Navigating Growth, Technology Disruption, and Strategic Imperatives
Market Landscape and Structural Challenges
The industrial energy management system (IEMS) market has entered a phase of accelerated maturation, driven by converging pressures around operational efficiency, regulatory compliance, and digital transformation. Over the past five years, the market has expanded from approximately $25.0 billion in 2020 to $35.2 billion in 2025, reflecting a compounded annual growth rate of 8.27% across the 2026-2032 forecast horizon. By the end of the forecast period, revenue is projected to approach $61.85 billion, signaling a structural shift from incremental efficiency upgrades to comprehensive, data-driven energy governance across industrial operations.
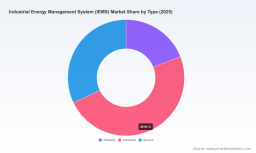
This trajectory reflects more than sustained capital expenditure; it indicates a fundamental reorientation of how industrial enterprises conceptualize energy. Historically treated as an overhead cost to be minimized through isolated equipment upgrades, energy is increasingly positioned as a managed asset with real-time visibility, predictive control, and measurable return on investment. The market’s expansion is broad-based across regions and applications, with industrial manufacturing, oil and gas, and petrochemical operations representing the largest deployment bases. Hardware continues to form the largest revenue component, reflecting the ongoing need for metering infrastructure, control systems, and integration layers, while software and service segments are growing faster as organizations seek actionable analytics and ongoing optimization support.
Despite this momentum, the market faces three structural challenges that will shape deployment patterns and vendor positioning over the next several years. First, fragmentation in system architectures and data standards continues to raise integration complexity. Industrial facilities often operate across legacy control environments, distributed utility interfaces, and heterogeneous equipment fleets. Deploying an IEMS that delivers enterprise-wide visibility without disrupting production cycles requires significant engineering effort, change management, and cross-functional alignment.
Second, the value proposition of energy management is increasingly tied to broader operational outcomes rather than energy savings alone. Decision-makers are evaluating IEMS investments against production throughput, asset reliability, emissions compliance, and resilience to volatile power markets. Systems that cannot demonstrate multi-dimensional ROI risk slower adoption, especially in capital-constrained environments or facilities with shorter investment horizons.
Third, the regulatory environment is tightening at both global and regional levels, but compliance requirements are evolving unevenly. Industrial operators must navigate a patchwork of efficiency mandates, reporting obligations, and emissions-related incentives that differ by jurisdiction and sector. While this regulatory pressure expands the addressable market, it also introduces execution risk for organizations that lack internal expertise to translate compliance mandates into operational programs.
These challenges are not barriers to growth; they are filters. They favor deployments that combine robust hardware foundations with flexible software, clear integration pathways, and services that help organizations move from data collection to measurable performance improvement.
Key Drivers Reshaping the Market
Technology Innovation and the Shift Toward Intelligent Energy Control
The most significant technological driver is the convergence of industrial automation, Internet of Things (IoT) connectivity, and advanced analytics. Modern IEMS solutions increasingly rely on high-resolution metering, edge processing, and cloud-based analytics to convert raw consumption data into operational insight. This shift enables real-time monitoring, anomaly detection, load forecasting, and optimization recommendations that were previously impractical in complex industrial environments.
Recent product and organizational moves reflect this trajectory. Emerson’s relocation to a new global headquarters in Clayton, Missouri, in February 2026 underscores a broader emphasis on industrial automation capabilities, including IEMS-linked process optimization and energy efficiency systems. The move signals not only investment in physical infrastructure but also a strategic focus on integrated automation and energy management as complementary domains. Similarly, Rockwell Automation’s energy monitoring and optimization tools within its industrial software portfolio illustrate how energy visibility is being embedded into existing automation ecosystems rather than treated as a standalone initiative.
On the software side, AI-enabled energy management is emerging as a differentiator. Tibo Energy’s €6 million funding round in May 2025 highlights growing investor interest in AI-driven energy optimization for industrial grid congestion and multi-site coordination. This funding dynamic suggests that next-generation IEMS offerings are moving beyond static dashboards toward predictive control, demand response enablement, and cost-reduction logic that can adapt to variable grid conditions and operational constraints. Start-ups and specialized software providers are increasingly competing on algorithmic sophistication, user experience, and deployment speed, pressuring larger incumbents to accelerate their own software-centric roadmaps.
Policy, Standards, and the Compliance-to-Strategy Transition
Policy and standards activity is both expanding demand and reshaping purchase criteria. The EU Energy Efficiency Directive continues to require industrial facilities to implement energy management systems with regular reporting on consumption and efficiency improvements. In parallel, the U.S. Energy Policy Act reinforces energy management practices in industrial settings, aligning efficiency objectives with broader sustainability goals. These frameworks create a compliance floor, but the most strategically advantaged operators are treating them as a starting point for deeper operational transformation.
ISO 50001 remains a widely adopted reference point for systematic energy performance improvement. Its influence extends beyond certification; it encourages organizations to establish measurement architectures, target-setting processes, and continuous improvement cycles that naturally align with IEMS deployments. At the same time, Paris Agreement implementation efforts are intensifying carbon-related taxes and incentives, particularly in manufacturing-intensive sectors. This creates a direct financial linkage between energy management and emissions outcomes, making IEMS solutions relevant not only to facility engineering teams but also to sustainability, finance, and executive leadership.
PW Consulting Chemical & Energy Research Center
Regional building and industrial codes are also contributing to demand. The California Energy Code’s 2025 updates aim to reduce industrial energy costs through mandatory efficiency measures and monitoring, illustrating how subnational policy can accelerate adoption in specific industrial clusters. Collectively, these regulatory and standards-driven dynamics are moving IEMS from optional best practice toward operational necessity in many markets.
Demand-Side Behavior and the Broadening Buyer Profile
A second major driver is the evolution of buyer expectations. Energy managers no longer evaluate IEMS purely on metering accuracy or report generation. Procurement and operations leaders increasingly prioritize interoperability with existing control systems, scalability across sites, and the ability to connect energy data with production scheduling, maintenance, and asset performance management. This broadens the stakeholder base around IEMS purchases and raises the bar for usability and integration.
In oil and gas and petrochemical operations, energy management is increasingly intertwined with process reliability and safety-critical control environments. Manufacturing buyers, meanwhile, are looking for systems that can support demand response participation, load shifting, and cost avoidance under volatile electricity pricing. As industrial organizations adopt more distributed energy resources and explore electrification of processes, the need for dynamic energy management becomes more acute. The result is a market where IEMS is evaluated not only as a compliance or efficiency tool but also as an enabler of operational flexibility.
Supply Chain and Cost Structure Dynamics
Supply chain conditions and cost structures continue to influence deployment economics. Hardware-heavy installations remain sensitive to component availability, procurement lead times, and integration labor. At the same time, the growing emphasis on software and services is shifting some spending toward recurring models, which can improve vendor revenue visibility but also increases buyer expectations for measurable outcomes over time. Organizations that can offer modular deployment pathways, standardized integration frameworks, and clear service-level commitments are better positioned to navigate these cost and supply chain realities.
For end users, the cost equation is increasingly framed around total cost of ownership and operational payback rather than upfront capital. This favors solutions that can be phased in across facilities, demonstrate early wins through focused use cases, and scale without proportional increases in project complexity.
Competitive Landscape and Strategic Positioning
Incumbents Anchoring the Market with Integrated Automation and Power Expertise
The IEMS market remains comparatively concentrated, with a limited number of large players commanding a substantial share of revenue. This concentration reflects the importance of scale, integration credibility, and longstanding relationships in industrial automation and power management.ABB continues to build on its industrial automation and power management heritage, emphasizing energy monitoring, optimization, and efficiency systems suited to manufacturing and heavy industry. Its positioning benefits from the ability to connect energy management with broader electrification and automation portfolios, which is particularly relevant for operators seeking a single vendorarrative across control, distribution, and monitoring functions.
Eaton’s focus on power management and electrical systems gives it a strong foothold in environments where energy optimization must align with electrical infrastructure and industrial power quality requirements. Emerson, through its automation and control capabilities, positions IEMS as part of a wider process optimization agenda, which can be attractive in complex manufacturing and process industries where energy outcomes are tightly linked to production parameters.
Siemens and Schneider Electric represent two of the most visible platforms plays in this space. Siemens leverages its digital industries and automation strengths to offer IoT-based energy optimization platforms that connect plant-level data with broader enterprise analytics. Schneider Electric’s EcoStruxure concept exemplifies an architecture-centric approach that combines energy management, automation, and connected services. Both companies benefit from global reach, broad industrial footprints, and the ability to package IEMS within larger digital transformation narratives.
Honeywell and General Electric also occupy important positions. Honeywell’s building and industrial automation platforms extend into energy efficiency and management for facilities, while GE’s industrial solutions and automation background supports energy management for process and manufacturing industries. Their presence reinforces the market’s emphasis on vendors that can bridge operational technology and energy performance management.
Automation Specialists and the Embedding of Energy Visibility
Rockwell Automation illustrates a strategic path that integrates energy monitoring directly into manufacturing software environments. By offering tools such as real-time energy monitoring and optimization within its factory software ecosystem, Rockwell reduces the friction of adding energy intelligence to existing production workflows. This embedded approach can shorten adoption cycles for manufacturers already standardized on its automation stack.
Building Energy Management System (BEMS) Market
Cisco’s relevance in the IEMS market may appear less obvious at first glance, but its networking and IoT capabilities underpin many industrial data infrastructures. As energy management becomes more data-intensive and distributed, reliable connectivity, edge networking, and secure data transport become critical enablers. Cisco’s positioning therefore reflects an ecosystem play: it supports energy management platforms and analytics by strengthening the underlying data fabric across industrial sites.
Specialists, Software-First Providers, and the Rise of Niche Differentiation
The market also includes a meaningful set of specialists and software-oriented entrants. EnerNOC, now operating under Enel X North America, has historically been associated with demand response and energy management services for commercial and industrial customers. Its service-oriented model highlights the continued importance of managed energy programs, particularly for organizations that prefer outsourced expertise or want to participate in grid-related revenue opportunities.
Worldwide Power Energy Management System (EMS) Market
Yokogawa, Azbil, and Mitsubishi Electric bring strong measurement, control, and automation expertise, particularly relevant in process industries where precise instrumentation and control logic are essential. Azbil’s headquarters relocation to Tokyo’s Marunouchi Park Building in November 2025 reflects a continued organizational focus on industrial automation and energy management offerings, signaling commitment to evolving its portfolio in a competitive environment.
On the software side, providers such as explitia, Tibo Energy, Prescient Technologies, and MRI Software illustrate the diversity of modern IEMS offerings. explitia’s EMS software emphasizes real-time monitoring, cost control, and process optimization in manufacturing. Tibo Energy’s AI-driven EMS targets real-time optimization and grid management for industrial sites. Prescient Technologies’ IIoT-based monitoring and analysis system is oriented toward manufacturing plants, while MRI Software’s energy platform addresses portfolio-wide consumption monitoring, optimization, and compliance. These players often compete on agility, user experience, and specialized analytics capabilities rather than on breadth of hardware portfolios.
How the Competitive Structure Is Evolving
The competitive landscape is not static. Large incumbents continue to strengthen their integration advantages and expand through product consolidation, services, and platform development. At the same time, software-first and specialist companies are gaining traction by addressing specific pain points: faster deployment, more intuitive dashboards, AI-based optimization, or superior multi-site coordination. IEM (Industrial Electric Manufacturing) adds another dimension with custom power distribution systems and energy management solutions tailored to industrial clients, reflecting demand for engineered solutions in specific application contexts.
This dynamic suggests a market that is simultaneously consolidating at the top and fragmenting in niche segments. Buyers benefit from choice, but they also face an increasingly complex evaluation process. Vendors that succeed are likely to be those that can articulate a clear value pathway: whether through deep integration with automation and electrical systems, superior analytics and optimization, strong service models, or rapid deployment in targeted verticals.
Future Outlook: Three Trends That Will Shape the Next 3–5 Years
1. From Monitoring to Autonomous Optimization
The next wave of IEMS adoption will be defined less by the ability to measure energy and more by the ability to act on it automatically. As analytics mature and industrial data environments become more connected, systems will increasingly support closed-loop optimization, predictive load management, and coordinated control across equipment and sites. For operators, this creates opportunities to reduce waste, improve scheduling, and participate more actively in demand-side flexibility. For vendors, competitive advantage will increasingly depend on the quality of algorithms, the reliability of recommendations, and the ease with which operators can trust and operationalize automated decisions.
The commercial opportunity here is substantial, but so is the execution risk. Autonomous optimization requires robust data quality, well-defined operational boundaries, and change management that aligns energy logic with production priorities. Organizations that deploy these capabilities prematurely, without sufficient process discipline or integration depth, may struggle to realize expected returns.
2. Energy Management as a Multisite, Portfolio-Level Discipline
Industrial enterprises are increasingly managing energy across multiple facilities, regions, and operating models. This is driving demand for portfolio-level visibility, standardized reporting, and centralized optimization that still respects local constraints. MRI Software’s focus on portfolio-wide monitoring and optimization reflects this broader shift. As organizations expand their use of IEMS beyond single plants, they will need architectures that can normalize data across sites, accommodate different equipment baselines, and support both strategic benchmarking and local action.
This trend opens opportunities for platforms that can scale without excessive customization. It also introduces complexity around governance, data ownership, and localization of compliance requirements. Multisite deployments will favor vendors that can balance standardization with flexibility, and that can provide services to help operators interpret enterprise-level insights in facility-specific terms.
3. Integration with Decarbonization, Electrification, and Grid Interaction
Energy management is becoming more tightly coupled with decarbonization strategy, electrification roadmaps, and grid interaction. Carbon-related policy pressure, regional efficiency mandates, and the financial implications of emissions performance are pushing industrial operators to treat energy data as a strategic input for sustainability planning. At the same time, the growing presence of distributed energy resources, storage, and electrification of industrial processes will increase the need for real-time coordination between energy consumption, on-site generation, and external grid signals.
This creates a market opportunity around IEMS solutions that can support emissions tracking, scenario analysis, and flexible load management. It also raises the stakes for integration: energy management platforms will need to interface not only with traditional industrial control systems but also with sustainability reporting workflows, electrical asset management, and increasingly dynamic power markets. The principal uncertainty is the pace and shape of policy and market evolution, which may differ significantly across regions and could influence which capabilities become essential first.
Strategic Implications for Decision-Makers
For Industrial Operators and Manufacturers
Energy management should be treated as an operational capability, not a one-time compliance project. The most effective deployments begin with a clear use-case strategy: identify where energy visibility can immediately improve cost control, production scheduling, asset reliability, or emissions reporting. Prioritize integration with existing automation and electrical systems to avoid creating parallel data silos. Where possible, adopt modular rollouts that deliver early value and build organizational confidence before scaling across sites.
Leadership alignment is critical. IEMS investments are more likely to succeed when energy, operations, maintenance, and sustainability teams share a common set of metrics and decisions. Establish a governance model that connects data collection to action, and ensure that optimization recommendations are validated against production and safety constraints.
For Investors and Strategic Partners
The market offers multiple entry points, but not all are equal in risk and reward. Large incumbents provide scale, integration breadth, and established industrial relationships, which can translate into more predictable demand in automation-heavy environments. Software-first and specialist providers may offer faster growth in niche segments, particularly where AI-driven optimization, multisite platforms, or service-based models address clear inefficiencies. When evaluating opportunities, pay close attention to differentiation in data architecture, integration capability, and the ability to convert insights into measurable operational outcomes.
It is also worth monitoring consolidation signals. As the market matures, firms that can combine hardware credibility, software sophistication, and services depth may be better positioned to capture share across the full deployment lifecycle. Conversely, players that remain overly fragmented or limited to narrow functionality may face pressure to partner, specialize further, or exit less competitive segments.
For Procurement and Technology Selection Teams
Evaluation criteria should extend beyond feature checklists. Assess how easily a solution integrates with current control and metering environments, how it handles data quality issues, and whether it supports the specific operational decisions your organization needs to make. Ask how the vendor handles multisite scaling, update cycles, and ongoing services, since these often determine long-term value more than initial deployment speed. Where possible, structure pilots around measurable operational outcomes rather than technical demonstrations alone.
Given the pace of regulatory change and the growing importance of energy optimization in industrial competitiveness, timely access to detailed market intelligence can materially improve decision quality. Segmentation trends, vendor positioning, regional regulation, and technology adoption patterns all influence which solutions are most appropriate for a given operating context. For organizations evaluating market entry, capital allocation, or vendor selection, a deeper review of segment-level data and tailored scenarios can help convert broad market momentum into a focused execution plan.
The IEMS market is moving from a period of broad growth to one of sharper strategic differentiation. The organizations that benefit most will be those that treat energy management as a core operational capability, select partners with clear integration and optimization depth, and build the internal discipline to turn data into action. As deployment models mature and software-driven optimization becomes more central, the gap between basic monitoring and genuinely managed energy performance will widen, creating both risk for laggards and opportunity for those who move with intent.
For detailed analysis of this topic, please visit the official page: Industrial Energy Management System (IEMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


