



Battery Separator Films Market: Why 6.98% CAGR Fuels the $344.8M Shift

Strategic Trends and Commercial Opportunities in the Battery Separator Films Market
Market Landscape: Navigating Scale and Structural Complexity
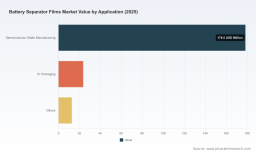
The battery separator films market is entering a phase of accelerated maturation, defined by steady revenue expansion and a hardening of competitive dynamics. Over the historical period from 2020 to 2025, industry revenue climbed from roughly $163.15 million to $215.0 million, reflecting a trajectory that survived macroeconomic volatility and supply chain disruptions. The forward outlook reinforces this momentum, with the market projected to reach $344.8 million by 2032, translating to a compound annual growth rate of 6.98 percent across the 2026 to 2032 forecast window. This growth profile signals more than incremental demand expansion; it points to a structural realignment in how energy storage components are manufactured, sourced, and integrated into global electrification strategies.
Within this expansion lies a concentration profile that remains relatively fragmented at the top. The top three players account for 24.6 percent of market revenue, while the top five capture 26.2 percent. Such figures indicate that no single manufacturer commands pricing power sufficient to dictate industry-wide terms, yet the gap between tier-one specialists and regional challengers is widening. This dynamic creates a bifurcated environment: established suppliers are investing heavily in process superiority, geographic diversification, and coating technologies, while smaller participants must either carve out highly specialized niches or risk being squeezed by capacity overhangs and cost compression.
The current market posture reflects several unavoidable inflection points. First, the push toward localized battery production, particularly in North America and select Asian corridors, is reshaping traditional sourcing models. Buyers increasingly prioritize supply assurance and regulatory alignment over lowest unit cost, forcing suppliers to make irreversible capacity commitments. Second, the technical ceiling for conventional polyolefin architectures is approaching in certain high-power and high-safety applications, prompting parallel development tracks for coated membranes, ceramic-reinforced designs, and ultra-thin structures that balance ionic conductivity with mechanical robustness. Third, raw material conditions for polyethylene and polypropylene feedstocks remain exposed to energy price swings and logistics constraints. This volatility complicates margin planning, especially for manufacturers that lack integrated resin supply or long-term hedging agreements.
For decision makers, the implication is straightforward: the separator market is no longer a commodity layer within the battery value chain. It is a strategic component where process technology, geographic positioning, and coating differentiation determine long-term contract viability and margin resilience.
Core Drivers Reshaping Demand and Supply Dynamics
Technology Innovation and Process Differentiation
Technological advancement remains the primary engine of competitive separation in this market. Wet-process and dry-process polyolefin routes each present distinct trade-offs in pore architecture, thickness control, mechanical strength, and throughput economics. Wet-process films typically offer tighter control over micropore structure and uniformity, attributes that matter for consistent electrochemical performance in lithium-ion cells. Dry-process films, in contrast, often provide higher throughput and lower processing complexity, which becomes attractive where scale and cost efficiency dominate procurement criteria.
The industry’s most active design frontier is coating technology. Ceramic-coated and polymer-coated variants improve thermal stability, wettability, and resistance to shrinkage under elevated temperatures, addressing safety concerns that intensify as cell energy densities rise. Ultra-thin coated structures are also gaining attention because they enable energy density gains without proportionate losses in puncture resistance or dimensional integrity. Recent operational developments underscore the momentum behind these directions. In July 2025, Microporous introduced a new ultra-thin coated wet-process polyethylene separator line at its Piney Flats, Tennessee facility, expanding the practical range of thin-film options in North American supply. Similarly, W-SCOPE doubled its lithium-ion separator output capacity in May 2025 through a major Chungju plant expansion, reinforcing the link between process scaling and the availability of coated and microporous membrane options for high-volume applications.
For manufacturers, the strategic takeaway is that innovation is shifting from base film production alone to integrated film-plus-coating value creation. Companies that can coordinate resin selection, pore engineering, and coating consistency on the same line gain an advantage in qualification cycles and customer lock-in.
Policy and Regulatory Pressure on Supply Chain Localization
Policy frameworks are increasingly shaping investment logic rather than simply constraining operations. The United States has emerged as a notable example of how financing and content requirements converge to redirect capacity placement. A $1.2 billion direct loan from the U.S. Department of Energy supported ENTEK’s Terre Haute, Indiana lithium-ion battery separator facility, an intervention designed to strengthen domestic EV supply chains and reduce reliance on imported components. The facility reached full-scale operations in October 2025, marking a concrete step in localized capacity deployment.
Parallel federal and regional incentives tied to Inflation Reduction Act content requirements are reinforcing the localization theme. Procurement teams in automotive and energy storage programs are evaluating component origins with greater scrutiny, and separator sourcing now intersects with broader battery content eligibility calculations. This environment rewards manufacturers that can demonstrate not only product performance but also traceability, domestic or near-shore production, and the ability to scale under regulatory timelines. Sumitomo Chemical’s restructuring of its PERVIO® separator business illustrates a different but related dimension of policy-linked optimization. By ceasing production at its Ohe Works in Japan and consolidating functions at its South Korean SSLM facility by the end of March 2026, the company signaled a move toward higher productivity and a more concentrated regional operating model, showing that regulatory and cost pressures can drive production footprints even among established players.
The commercial implication for buyers and investors is that local supply narrative is becoming a material procurement factor. Capacity located in jurisdictions that align with incentive programs and content rules can secure preferential access to anchor contracts, while foreign-supply-dependent models may face increased qualification friction.
Demand-Side Transformation in Electrification and Storage
Demand growth is no longer solely a function of passenger EV volume. Energy storage systems, commercial electrification, and advanced consumer applications are expanding the addressable base for separator films, and the composition of that demand is changing the technical requirements placed on suppliers. North American manufacturing capacity expansions accelerated in 2025 and 2026 as EV and energy storage system growth drove lithium-ion battery separator demand, reflecting a broader shift toward regionalized production for regionalized demand.
PW Consulting
This demand mix introduces new performance priorities. Higher cycle-life expectations, wider operating temperature ranges, and more demanding safety thresholds are pushing specifications beyond baseline polyolefin performance. Asahi Kasei’s October 2025 strategic agreement with Toyota Tsusho for North American supply of Hipore wet-process lithium-ion battery separators shows how tier-one manufacturers are aligning product lines with regional channel partners to meet localized demand at scale. UBE MAXELL’s planned 50 percent increase in separator base film production capacity at its Sakai Works in Japan, announced in May 2026, reflects a similar bet that sustained EV and energy storage demand will justify expanded base film output.
The operational lesson is that demand growth is increasingly segmented by application intensity. Suppliers that can match film architecture to specific use cases, whether high-power transport, stationary storage, or specialty electronics, will capture more defensible positions than those competing primarily on volume alone.
Cost Structure and Raw Material Sensitivity
Even with strong demand, cost structure remains a decisive factor in margin durability. Polyethylene and polypropylene feedstocks used in battery separator films experienced volatility in 2025 due to oil price fluctuations and supply chain factors. Because polyolefin chemistry sits close to petrochemical feedstock markets, separator producers are exposed to price movements that are only partially controllable through internal procurement tactics.
In this context, cost leadership is less about chasing commodity input prices and more about reducing conversion losses, improving line yield, extending film life in service, and differentiating with coatings that justify premium pricing. Capacity expansions also change the cost equation: as new lines come online and utilization rises, fixed-cost absorption improves, but only if demand can absorb additional volume without triggering aggressive price competition. ENTEK’s completion of its first major U.S. separator production expansion in Terre Haute, Indiana demonstrates how capacity deployment can be timed to align with regional demand growth, but the long-term profitability of such investments depends on sustained offtake and disciplined pricing.
For executives, the practical implication is that raw material sensitivity should be managed through product strategy as much as procurement strategy. Coating differentiation, qualification moats, and application-specific film design can buffer businesses from the full force of resin price swings.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive field is anchored by a set of manufacturers with distinct technological heritage, geographic reach, and product architectures. Asahi Kasei Corporation, based in Tokyo, produces Hipore wet-process polyethylene and Celgard dry-process polypropylene battery separator films for lithium-ion batteries, giving it a broad platform across processing routes. Toray Industries, also headquartered in Tokyo, manufactures Setela coated and uncoated polyethylene and polypropylene separator films for EV and energy storage applications, with an emphasis on functional coating in addition to base film. SK Innovation, in Seoul, develops ceramic-coated and non-coated polyolefin separator films with enhanced safety, aligning its product narrative with risk mitigation for lithium-ion systems.
In China, SEM CORP, based in Jiaxing, operates as a global supplier of lithium-ion battery separator films including coated and uncoated polyolefin options, combining scale with multi-format capability. W-SCOPE, headquartered in Chungju, produces microporous and coated lithium-ion battery separator membranes using polymer film technology, and its May 2025 capacity doubling illustrates how regional champions can rapidly expand output to support EV and storage demand. In the United States, ENTEK International, based in Lebanon, Oregon, manufactures wet-process polyethylene and coated lithium-ion separator films for EV and energy storage, while Microporous LLC, in Danville, Virginia, produces ionForce coated wet-process polyethylene separator films, with the July 2025 launch of its ultra-thin coated line in Piney Flats, Tennessee further extending thin-film capability.
European participation remains meaningful. Freudenberg Performance Materials, headquartered in Weinheim, Germany, supplies innovative separator materials for lithium-ion batteries and energy storage systems, bringing material science depth to the field. UBE Corporation, in Tokyo, produces battery separator base films and related polyolefin materials for lithium-ion applications, emphasizing base film supply and upstream material linkage. Ahlstrom Oyj, in Helsinki, develops separator materials including absorbent glass mat and polyolefin films, positioning around materials versatility and specialized substrate engineering.
The strategic positioning emerging from this landscape favors several differentiation paths. One is process leadership in wet-process uniformity and thinner film architectures, where qualification success can create durable customer relationships. Another is coating capability, where thermal stability, safety performance, and wetting behavior become decision criteria beyond base film thickness. A third is geography-aligned supply, where manufacturers that can serve regional content requirements and local production programs gain preferential access to anchor accounts. A fourth is vertical relevance, where base film producers that integrate with polyolefin supply or downstream coating operations reduce exposure to intermediate market inefficiencies.
Market structure appears to be evolving through selective consolidation and capacity realignment rather than uniform concentration. Sumitomo Chemical’s closure of its Ohe Works and consolidation of PERVIO® production at SSLM in South Korea reflects a productivity-focused rationalization. At the same time, the expansion cadence of companies such as W-SCOPE, ENTEK, and UBE MAXELL suggests that new capacity continues to enter where demand visibility is strongest. The result is a competitive environment in which technology and regional supply alignment matter more than sheer scale, and where new entrants must either bring a distinct coating or process advantage or target underserved regional demand with credible execution capability.
Forward Trajectory: Three Directional Shifts and the Opportunities They Create
Over the next three to five years, the separator market is likely to be shaped by three interrelated trends. The first is the widening premium for coated and safety-enhanced architectures. As cell formats evolve and energy density targets rise, buyers will increasingly select membranes that reduce risk under thermal and mechanical stress. This does not eliminate demand for uncoated base films, but it shifts the value mix toward coated variants and makes coating consistency a qualification gate. Commercial opportunity lies with producers that can standardize coating quality at scale and document performance in ways that simplify customer validation.
Lithium-Ion Battery Separator Market
The second trend is regional capacity alignment as a competitive asset. Local production is becoming tied to content eligibility, supply assurance, and logistics resilience, especially in markets where incentive programs and industrial policy reward domestic manufacturing. The opportunity here is dual-edged: established suppliers can lock in multi-year supply relationships by co-locating with customer programs, while regional entrants can build defensible positions if they achieve process reliability and cost discipline quickly enough. The risk is that capacity is brought online ahead of demand absorption, creating localized overcapacity and forcing price concessions.
The third trend is ongoing raw material and energy cost sensitivity, which will keep pressuring conversion economics. Feedstock volatility is unlikely to disappear entirely, and separator manufacturers will continue to face decisions about resin sourcing, hedging, and process efficiency. The strategic opportunity is to design products that earn price resilience through function rather than volume. Ultra-thin films, ceramic-coated variants, and application-tailored membrane designs can offset input cost pressure if they are validated for performance and safety in high-value applications. The risk, by contrast, is that undifferentiated commodity competition intensifies when multiple producers chase the same conventional film specifications.
A further nuance is that qualification cycles and customer switching costs can either accelerate or dampen these trends. In applications where validation timelines are long and failure costs are high, suppliers with established testing records and reproducible process control can maintain share even in a growing market. In more price-sensitive segments, however, rapid capacity entry and cost competition can compress margins and reward only the leanest operators. Understanding which applications fall into each category is essential for realistic forecasting and capital planning.
Strategic Actions for Decision Makers
For manufacturers, the priority is to connect process capability with qualification speed and regional relevance. Investments in coating consistency, thickness control, and line yield should be evaluated not just for cost reduction but for their ability to shorten customer validation and support premium positioning. Where capacity expansion is contemplated, alignment with end-market demand visibility and regulatory or content incentives should be treated as a core part of the investment thesis, not a peripheral consideration. Companies should also assess whether base film production, coating, or both are most defensible in their target segments, because the margin story increasingly depends on integrated capability rather than single-step output.
For investors, the market rewards disciplined capital allocation tied to application intensity and supply localization rather than headline volume growth alone. The strongest opportunities lie where technology differentiation, coating capability, and regional production alignment converge, particularly in jurisdictions where energy storage and EV programs are expanding under incentive frameworks. Due diligence should focus on utilization trajectories, feedstock exposure, qualification pipelines, and the durability of supply agreements. Equally important is the risk of overbuilt regional capacity and the possibility that raw material volatility erodes margins for producers without differentiated product mixes.
For procurement and supply chain leaders, separator sourcing should be treated as a performance-and-assurance decision rather than a commodity purchase. Evaluating suppliers on coated film consistency, thermal and mechanical performance documentation, domestic or near-shore production capability, and the ability to scale under program timelines can reduce downstream risk in cell and pack programs. Diversifying the supplier base between wet-process and dry-process options, and between coated and non-coated variants where appropriate, can also improve resilience against feedstock volatility and capacity constraints. Contract structures that link pricing to validated performance and supply assurance, rather than to spot input conditions alone, may offer more stable economics over multi-year program horizons.
Worldwide Polyolefin Battery Separator Films Market
The range of possible outcomes in this market remains wide, and the margin between success and delay often comes down to the speed and precision of strategic decisions. Detailed segment-level sizing, application-specific demand mapping, regional capacity tracking, and company-level positioning data provide the granularity needed to convert these directional trends into executable plans. Readers seeking that level of detail, including deeper segmentation and customized strategic guidance, can explore the full PW Consulting research report for the Battery Separator Films Market.
For detailed analysis of this topic, please visit the official page: Battery Separator Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


