



Industrial Enzymes Market: Why 6.4% CAGR Signals Structural Shifts

Industrial Enzymes Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot: Scale, Trajectory, and the Current Inflection Point
The global industrial enzymes market has firmly entered a phase of sustained expansion, reflecting a broader structural shift toward biological catalysis across manufacturing, processing, and treatment applications. Measured in USD Millions, the sector moved from a base above 5.3 billion in 2020 to an estimated 7.4 billion in 2025, and the forward trajectory points to continued upward momentum through 2032, when the market is projected to approach the 12 billion threshold. The implied compound annual growth rate of 6.4 percent over the forecast window signals that demand is not merely recovering from cyclical softness but accelerating along a secular growth path. This pace matters because it compresses planning horizons for capacity, R&D, and commercialization, rewarding organizations that can align product roadmaps with the timing of regulatory clearances, feedstock availability, and application adoption.
Enzyme for Pulp & Paper Market
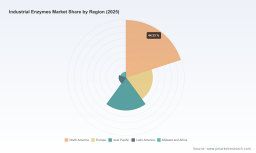
Regionally, the market is anchored by mature industrial ecosystems in North America and Europe, while Asia Pacific represents a large and structurally rising share shaped by expanding food processing, biofuels infrastructure, and animal nutrition demand. The geographic distribution underscores that enzyme demand does not travel in isolation; it follows local processing capacity, agriculture-linked feedstock flows, and consumer-driven formulation trends. In practical terms, the same enzyme capability can face very different commercialization pacing depending on where it is introduced, which makes regional regulatory calendars and sourcing strategies decisive variables in go-to-market execution.
At the current stage, the industry sits at a rare intersection of scale, innovation, and policy influence. Applications across food and beverages, biofuels, animal feed, detergents, paper and pulp, wastewater treatment, and textiles are collectively pulling demand forward, but the growth is uneven in character._value_differences_ between sectors are becoming less about raw volume and more about the economic value enzymes create in specific process steps, tolerance profiles, and purification requirements. That shift is changing how suppliers are evaluated, from broad product availability to application-specific performance, consistency, and integration support.
Three challenges are shaping the industry's next chapter. First, the market remains highly concentrated, with a small group of large players holding a dominant share of revenue and customer relationships. This concentration creates an elevated bar for new entrants and mid-sized suppliers that must differentiate on technology, niche application delivery, or cost structure rather than competing head-on on scale alone. Second, macromaterial inputs, regulatory timelines, and tariff dynamics are introducing new variability into the supply chain, affecting sourcing decisions, pricing stability, and the pace at which localized production becomes economically attractive. Third, the rate of adoption in several end-use sectors now depends less on whether enzymes exist and more on whether they can be integrated into existing process architectures without adding operational friction. In that environment, the winners are increasingly those who can make enzymes work within real-world manufacturing constraints, not just demonstrate laboratory performance.
Key Drivers: What Is Actually Moving the Market
The market is being reshaped by several reinforcing forces. Technological progress is the most visible, but the commercial impact depends on how quickly breakthroughs translate into cost-effective, scalable production and application-ready formulations. Innovation in enzyme engineering, strain development, and high-throughput screening is extending the range of reactions that enzymes can perform efficiently and the conditions under which they remain stable. This matters because industrial environments often demand activity under elevated temperature, pH variability, or challenging substrate matrices. Companies that can deliver robust biocatalysts for starch saccharification, grain processing, oil and fat processing, protein modification, or high-temperature industrial processes are gaining credibility in applications where consistency and operational simplicity determine repeat usage.
Equally important is the policy and regulatory environment. Government approvals for new enzymes continue to create openings across multiple applications, and the approval pathway itself has become a strategic variable. A new enzyme that clears regulatory scrutiny can unlock incremental demand in food processing, animal nutrition, detergents, or technical applications, but delays or divergent regional requirements can slow commercial deployment. As a result, suppliers are paying closer attention to the sequence of evaluations across jurisdictions, to labeling and compliance considerations, and to how regulatory status affects downstream customer adoption. The market is increasingly shaped not only by technical performance, but by the speed at which performance can be made commercially permissible and operationally accepted.
PW Consulting
On the demand side, consumption patterns and corporate behavior are shifting in ways that reinforce enzyme utility. Food and beverage manufacturers are under pressure to improve efficiency, manage ingredient costs, and accommodate cleaner-label or novel processing needs. Biofuels and bioindustrial applications are drawing renewed interest where renewable fuel demand and enzyme approvals intersect, creating a demand loop that rewards suppliers capable of supporting substrate conversion and process reliability. In animal feed and nutrition, enzymes are increasingly viewed as tools for optimizing digestibility and resource use, particularly where feed formulation flexibility is tied to cost control and supply resilience. These demand-side changes are not uniform, yet they share a common thread: organizations seek inputs that can reduce waste, improve yield, or enable formulation changes without sacrificing throughput.
Supply chain and cost structure dynamics are adding a further layer of strategic pressure. Enzyme production relies heavily on microbial fermentation using plant-based feedstocks, meaning that feedstock availability, fermentation economics, and process scale directly influence cost competitiveness. At the same time, cumulative tariff developments through 2025 have begun to reshape sourcing, pricing, and localization strategies across the value chain. For many industry participants, this is prompting a reassessment of where to manufacture, how to buffer input exposure, and whether regional production or localized supply agreements can reduce volatility. The practical implication is that enzymes are no longer evaluated only on performance or price per unit; they are increasingly evaluated on the resilience and predictability of the supply chain that delivers them.
Enzymes For Fuel Ethanol Market
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive field is defined by a blend of global incumbents with broad fermentation and formulation capabilities and specialized players that compete on application depth or technology specificity. Novonesis has built a strong position around enzymes and biosolutions for industrial bioprocessing, starch saccharification, grain processing, and high-performance biocatalysts for food and beverage, biofuels, and detergent applications. Its profile reflects a strategy oriented toward broad process coverage and the ability to serve multiple high-volume industrial segments with integrated biocatalytic solutions. dsm-firmenich has emphasized enzymes and solutions for processing ingredients including oils and fats, fermentation, fruit and vegetable processing, and starch saccharification, highlighting a focus on ingredient- and process-level value rather than commodity enzyme supply alone. BASF SE has positioned around high-performance industrial enzymes and solutions for grain processing, bio-ethanol production, animal nutrition, and detergents, leveraging scale, process integration, and a presence in both food-adjacent and industrial applications.
A second layer of competition comes from suppliers that differentiate through application-specific portfolios or specialized production expertise. Kerry Group emphasizes enzymes for food and beverage processing, dairy, and plant-based applications, aligning closely with formulation trends and ingredient innovation in modern food systems. AB Enzymes focuses on formulated enzyme preparations for food, feed, technical uses, pulp and paper, baking, and plant-based food processing, where product formulation and application consistency are central to customer value. Amano Enzyme has developed a specialty industrial enzyme presence around plant-based beverages, protein isolates, and non-dairy applications, an area where processing nuances and customer formulation needs can create defensible niches. Enzyme Development Corporation contributes plant-based enzyme options including papain, ficin, thistle rennet, cellulases, and hemicellulases for food, beverage, and industrial uses, illustrating the continued relevance of botanical and specialty enzyme sources alongside fermentation-based platforms. Dyadic International is notable for recombinant enzymes and biocatalysts for biofuels, pulp and paper, brewing, specialty chemicals, and high-temperature industrial processes, with a technology orientation that can extend into difficult process conditions and non-animal production routes. Advanced Enzyme Technologies serves grain processing, brewing, dairy, oil and fat, and non-food applications, reflecting a diversified portfolio model that spans both food-linked and industrial segments.
Recent developments show how competitive advantages are being built in real time. In late 2025, Lubrizol announced a $10 million investment to expand fermentation production capacity by five times at its Center of Skin Care Excellence in Gavà, Spain, signaling that fermentation capacity expansion remains a strategic lever even in more specialized biotech-leaning applications. In early 2026, Dyadic Applied BioSolutions and Inzymes ApS announced plans to commercialize recombinant non-animal bovine chymosin for cheese and dairy processing after reaching a development milestone, an example of how recombinant technology can open product opportunities that address non-animal sourcing preferences and supply-chain alternatives. In December 2025, Dyadic and Fermbox Bio expanded their collaboration on commercializing animal-free proteins and enzymes across life science, food and nutrition, and bio-industrial markets, underscoring the growing importance of partnerships that combine production platforms, application expertise, and commercialization pathways.
The structural trend across the landscape is not simply consolidation; it is selective integration paired with targeted fragmentation. Large players continue to compete on breadth, fermentation scale, application coverage, and customer integration, while smaller or focused firms compete by occupying specific application niches, offering distinct enzyme sources, or advancing recombinant and specialty biocatalyst capabilities. New entrants tend to succeed when they bring a clear technical edge or a commercially compelling route to an underserved use case rather than attempting to replicate broad incumbent portfolios. Over time, the most durable differentiation is likely to come from the combination of application reliability, regulatory readiness, and supply resilience, because customers in industrial environments increasingly want performance that is verifiable under process conditions and supply that is traceable and dependable.
Future Outlook: Three Trends Shaping the Next Three to Five Years
The first trend is the continued integration of enzyme-enabled process improvements into mainstream industrial operations. As enzyme approvals expand and fermentation-based production matures, more manufacturers are likely to treat enzymes as core process inputs rather than specialty additives. This creates commercial opportunities for suppliers that can document consistent performance, reduce process variability, and support scale-up. It also raises the stakes for companies that cannot demonstrate operational reliability, because adoption in demanding environments depends on outcomes at commercial scale, not only on technical capability.
The second trend is the growing strategic importance of application-specific and source-specific enzyme solutions. In food and beverage, plant-based and non-dairy applications, non-animal rennet alternatives, and other formulation-sensitive areas, the value proposition is increasingly tied to specificity, compatibility, and consumer-facing positioning. This is reinforcing demand for recombinant routes, specialty plant-based enzymes, and tailored formulations that address narrow but commercially valuable needs. For suppliers, the opportunity lies in building application expertise and customer integration capabilities, not just product catalogs. For buyers, the opportunity is to use such solutions to streamline formulation, reduce reliance on constrained inputs, or align product positioning with market preferences.
The third trend is supply chain localization and cost-structure redesign in response to feedstock and trade dynamics. Tariff developments and feedstock dependencies are prompting a more deliberate approach to where enzymes are manufactured, how fermentation capacity is scaled, and how customer supply commitments are structured. Over the next few years, organizations that invest early in regional capacity, feedstock resilience, or flexible sourcing models may gain pricing and service advantages when volatility intensifies. At the same time, there is a risk that excessive localization could raise unit costs if not matched by sufficient demand density or process efficiency. The strategic balance will be between resilience and competitiveness, and firms that over-index on one side may lose ground to those that can manage both.
These trends carry inherent uncertainties. Demand in biofuels and bioindustrial applications can fluctuate with policy signals and commodity economics. Regulatory clearance timelines can differ across regions, affecting the pace at which new enzyme solutions reach market. Feedstock availability, fermentation yields, and process scale can shift cost structures quickly enough to alter competitive dynamics. In addition, the concentration of the market means that a few large players can shape pricing, capacity allocation, and partnership patterns in ways that smaller companies must anticipate carefully. The overall outlook is positive, but the path is conditional on execution, regulatory timing, and supply resilience.
Strategic Moves for Decision-Makers
For manufacturers and product suppliers, the clearest imperative is to align enzyme strategy with application reliability and supply continuity. That means prioritizing capability in the processes that matter most to customers, documenting performance under realistic operating conditions, and building the fermentation or formulation infrastructure needed to support repeatable delivery. Companies should also assess where regulatory approvals, feedstock exposure, and trade dynamics intersect with their commercial plans, because timing and sourcing can determine whether a technically strong solution reaches the market with commercial momentum.
For investors, the market offers value in companies that combine differentiated technology with a credible path to commercialization in specific applications. The most informative signals are not simply revenue scale but product maturity, regulatory readiness, application validation, partnership footprint, and capacity expansion logic. Investors should pay particular attention to firms that can translate innovation into cost-effective production and that have clear positioning in high-value segments such as food processing, biofuels, animal nutrition, detergents, or specialty technical uses. Portfolio decisions are likely to be more durable when they reflect both growth potential and the operational constraints that shape industrial adoption.
For procurement and sourcing leaders, enzyme selection should be treated as a strategic input decision rather than a routine specification. That involves evaluating not only performance characteristics but also supplier resilience, regional sourcing options, lead-time stability, and the degree to which a supplier can support integration and process changes. Where feasible, multi-supplier strategies, localized supply arrangements, or partnerships that reduce exposure to single points of failure can improve continuity. Procurement teams that understand the link between feedstock economics, fermentation scale, and regulatory status will be better positioned to anticipate price behavior and manage long-term supply agreements.
Timely access to detailed market segmentation, regional dynamics, regulatory trackers, and company-level assessments can materially strengthen planning in this environment. Detailed intelligence supports more precise prioritization of applications, capacity investments, partnership opportunities, and risk mitigation measures. The industrial enzymes market is large enough and diverse enough that broad directional insight only goes so far; actionable advantage comes from knowing where demand is forming fastest, which applications are opening through approvals or formulation shifts, and how suppliers are positioning their production and commercialization strategies. Readers seeking a structured, data-backed view of these dimensions can access the full research report for deeper dives into market splits, competitive profiles, and forward scenarios tailored to specific business objectives.
For detailed analysis of this topic, please visit the official page: Industrial Enzymes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


