



Medical Swab Market: Why 6.98% CAGR to $6.17B by 2032 Changes Everything

The Medical Swab Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for medical swabs has transitioned from a crisis-driven surge to a more structured, demand-led expansion. Between 2020 and 2025, the market grew from 2.15 billion USD to 3.76 billion USD, reflecting both the lingering effects of heightened diagnostic demand and the normalization of specimen collection as a routine clinical practice. Looking ahead, the market is projected to reach 6.17 billion USD by 2032, expanding at a compound annual growth rate of 6.98 percent. This trajectory suggests that medical swabs are no longer a commoditized afterthought but a strategically relevant component in diagnostics, infection control, and point-of-care workflows.
Yet growth alone does not define strategy. The market is shaped by shifting material preferences, regulatory tightening, supply chain recalibration, and the ongoing consolidation of diagnostic ecosystems. For executives, investors, and procurement leaders, the question is no longer whether demand will continue, but where value will be created and how competitive positions will be defended.
Market Snapshot and Core Challenges
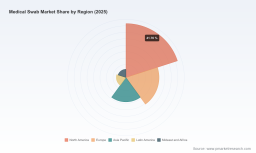
The market's expansion over the past five years has been broad-based, with North America historically accounting for the largest revenue share, followed by Europe and Asia Pacific. This geographic distribution reflects established healthcare infrastructure, higher diagnostic volumes, and stronger procurement formalized through large distributors. At the same time, the product mix has evolved. Foam-tipped and cotton-tipped swabs continue to anchor much of the revenue, while non-woven variants and specialty formats command growing attention in specific diagnostic and wound-care applications. Specimen collection remains the dominant use case, consistent with the market's deep integration into microbiology, respiratory testing, and routine clinical sampling.
Against this backdrop, three challenges stand out as strategic inflection points.
Challenge 1: Quality, Contamination Risk, and Procurement Sensitivity
Quality failures in medical consumables can have outsized consequences because swabs are often used on vulnerable populations and in time-sensitive diagnostic workflows. Regulatory notices and voluntary recalls have highlighted microbial contamination risks in alcohol prep pads and related items, reinforcing scrutiny across the broader category of sterile and semi-sterile medical consumables. For procurement teams, this increases the importance of supplier qualification, lot traceability, and documentation of manufacturing controls. For manufacturers, it raises the cost of compliance and the need for consistent quality systems that can withstand audit cycles and unexpected disruption.
Challenge 2: Regulatory Tightening Around Diagnostics and Specimen Handling
The regulatory environment is becoming more demanding, particularly where swabs intersect with in vitro diagnostics. Proposed and evolving rules on laboratory-developed tests are pushing more diagnostic workflows into formal premarket review and quality system expectations. In parallel, at-home over-the-counter COVID-19 testing frameworks continue to specify self-collection requirements that depend on approved swabs or equivalent sampling media. These changes do not merely alter compliance burdens; they reshape product design requirements, validation pathways, and the speed at which new collection systems can be deployed.
Challenge 3: Material Trade-offs and Supply Chain Exposure
Swab performance is highly dependent on tip material, shaft stiffness, absorption characteristics, and compatibility with transport media. Cotton, foam, flocked, and non-woven formats each present distinct trade-offs in cost, specimen release, and clinical suitability. This material complexity creates supply chain exposure, especially when demand spikes or when specific grades of raw material become constrained. The market has already experienced periods where sterile cotton swabs and gauze-based products faced supply tension during prior surges, and that structural sensitivity remains relevant whenever volume expectations shift quickly.
Key Demand Drivers
The market's continued expansion is not accidental. It reflects a convergence of technology, regulation, demand behavior, and supply-side restructuring that together create durable pull for better sampling tools and more reliable consumable supply.
PW Consulting Health Care Research Center
Technology Innovation in Collection and Preservation
One of the most consequential shifts is the move from simple collection tools to integrated collection-and-preservation systems. Flocked swab formats have become especially relevant because they can improve specimen release and reduce retention compared with traditional fiber mats, making them attractive for microbiology and molecular workflows. More recently, the introduction of FDA-cleared collection and transport systems designed for rapid inactivation and preservation points to a broader trend: swabs are increasingly evaluated not only by how well they collect, but by how well they stabilize specimens, reduce biohazard exposure, and support faster turnaround.
This matters commercially because it changes the basis of competition. In a commoditized price environment, tip material and pack size may dominate purchasing decisions. In a performance-driven environment, validation data, compatibility with diagnostic platforms, and specimen integrity become differentiators. Companies that can demonstrate measurable performance benefits in realistic collection scenarios are better positioned to defend pricing and build preference with laboratory and clinical customers.
Regulatory and Policy Dynamics
Policy and regulatory developments are influencing both product design and market access. Expectations around quality systems, premarket review for certain diagnostic-related products, and clearance pathways for collection systems are encouraging more documented validation and more cautious product claims. At the same time, at-home testing requirements continue to reinforce the role of reliable self-collection materials. The net effect is a market where compliance capacity is increasingly a market-entry barrier, but also a source of trust. Manufacturers with established regulatory competence can convert that competence into preference with risk-averse procurement organizations and integrated diagnostic customers.
Demand-Side Changes in Clinical and Consumer Settings
Demand for medical swabs is being shaped by two overlapping behaviors. In clinical settings, the continued emphasis on rapid diagnostics, respiratory surveillance, and specimen quality keeps sampling materials in steady demand. In consumer-facing settings, the normalization of self-collection for certain tests has expanded the relevance of swabs beyond traditional hospital and laboratory channels. The practical implication is that downstream customers are increasingly sensitive to ease of use, consistency, and clear instructions, especially when the end user is not a trained clinician. Products that reduce variability in collection technique can lower downstream rejection rates and improve overall diagnostic efficiency.
Supply Chain Recalibration and Cost Structure
Cost structures in this market are influenced by raw material availability, manufacturing geography, sterilization and packaging requirements, and logistics for sterile consumables. Companies that can balance quality, lead time, and cost position are gaining advantage, especially as procurement organizations place greater weight on resilience and continuity. There is also a growing premium on transparency: customers want to understand not just unit pricing, but the reliability of supply, documentation supporting sterility and performance, and the ability to scale without compromising control. In that environment, supply chain design becomes a strategic asset rather than a back-office function.
Competitive Landscape and Leading Strategies
The competitive field combines large diversified medical supply companies, specialist swab and collection-system manufacturers, and regional producers with strong cost positions. Market concentration is moderate, with the top three players holding roughly 35 percent of revenue and the top five closer to 47 percent. This level of concentration suggests that scale, brand trust, and channel access matter, but it also leaves room for differentiated specialists and regional challengers to compete on performance, compliance, or cost.
Several companies illustrate the strategic diversity in the market.
Puritan Medical Products has built a strong identity around medical-grade sterile and non-sterile swabs, flocked formats, and collection/transport systems. Its emphasis on U.S.-based manufacturing and FDA-cleared solutions for rapid diagnostics, including SARS-CoV-2-related workflows, reflects a strategy centered on trust, traceability, and regulated performance. The launch of a collection and transport system designed for rapid inactivation and preservation with a fast turnaround illustrates how a focused player can compete on workflow value rather than commodity volume alone.
Copan Diagnostics is widely associated with flocked swab technology for specimen collection in microbiology and diagnostics. Its market position indicates the value of deep application expertise and platform compatibility. Product validation work, such as evaluations of collection formats for enteric pathogen detection on major diagnostic systems, shows how specialists reinforce preference by aligning their sampling tools with the workflows of high-value diagnostic platforms.
BD and Medline Industries represent the broader diversified supplier model. BD provides flocked and cotton swabs across microbiology, diagnostics, and specimen collection, benefiting from scale, distribution breadth, and integration with larger medtech ecosystems. Medline supplies cotton swabs, gauze swabs, and medical disposables to hospitals and healthcare facilities, competing in part on reliability, catalog breadth, and institutional procurement relationships. In this segment, advantage often comes from being easy to specify, easy to procure, and consistent across large-volume contracts.
Dynarex Corporation and Sarstedt AG & Co. KG further illustrate the range of positioning. Dynarex focuses on sterile cotton and medical swabs for clinical, laboratory, and diagnostic use, while Sarstedt provides laboratory and medical sampling swabs, including forensic and diagnostic variants. These players highlight the continued relevance of application-specific offerings, where the value proposition is tied to the needs of particular testing environments rather than to mass-market price competition alone.
Surgical Sponge Market
On the regional side, companies such as GPC Medical Ltd, Hubei Baikang Medical Instrument, Winner Medical, Shenzhen Huachenyang Technology, and Jiangsu Huida Medical Instruments demonstrate the importance of manufacturing capacity, cost efficiency, and export-oriented supply. Several of these manufacturers emphasize compliance with international quality and regulatory standards, which is increasingly necessary for accessing regulated markets and competing beyond purely price-driven channels. Their presence also reflects a broader structural reality: the market is not dominated by a single geography of production, and sourcing strategies are often shaped by the trade-off between cost, lead time, and regulatory acceptability.
Recent market events underscore the operating environment. A voluntary nationwide recall of a large alcohol prep pad product due to potential microbial contamination, affecting more than 170 million units, reminds the industry how quickly quality issues can scale into commercial and reputational exposure. At the same time, product-level progress such as FDA-cleared rapid collection and preservation systems, and validation studies linking swab formats to diagnostic system performance, shows where differentiation is being built.
How the Landscape Is Evolving
Three patterns are shaping competitive evolution.
- Integration around workflows. Swabs are increasingly evaluated as part of a larger collection, transport, and testing workflow. Players that can align their products with diagnostic platforms, specimen stability requirements, and procurement simplification are gaining strategic leverage.
- Differentiation through compliance and evidence. In a market where recalls and regulatory scrutiny heighten risk awareness, documented quality systems, clearance status, and performance validation are becoming powerful trust signals.
- Persistent regional competition. Cost-competitive manufacturers continue to pressure commoditized segments, while regulated and application-specific segments reward specialized capability. The result is a bifurcated environment rather than a uniform race to the bottom.
Future Trends and Commercial Opportunities
Over the next three to five years, the medical swab market is likely to be shaped by a small number of durable trends. Each carries implications for product strategy, sourcing, and investment.
Trend 1: From Collection Tool to Specimen-Integrity Solution
Swabs will increasingly be judged by their contribution to specimen quality, stabilization, and workflow efficiency, not just by tip material or unit cost. This opens opportunities for products that combine superior release performance, compatibility with transport media, and reduced biohazard handling burden. For manufacturers, the opportunity lies in building clinically relevant evidence and making that evidence easy for procurement and laboratory customers to use in decision-making. For buyers, the opportunity is to reduce downstream variability and improve the reliability of diagnostic results.
Trend 2: Greater Regulatory Discipline as a Competitive Filter
As diagnostic-related expectations become more formalized, suppliers with robust quality systems and clear clearance pathways will be better positioned to retain and expand share in regulated channels. This trend favors incumbents and well-prepared specialists, while raising the bar for new entrants that lack documentation, validation capacity, or regulatory experience. Commercially, this means that compliance capability can become a moat, especially in segments where customers are risk-averse or where self-collection and point-of-care use increase the stakes around consistency and safety.
Trend 3: Resilient, Multi-Source Supply as a Procurement Priority
Demand volatility, raw material sensitivity, and the consequences of contamination events are likely to keep supply resilience near the top of procurement agendas. The resulting opportunity is for suppliers that can offer predictable lead times, transparent documentation, and credible contingency plans. For distributors and large healthcare customers, this may mean dual sourcing, stricter qualification criteria, and more emphasis on supplier responsiveness. For manufacturers, it means that operational reliability is a selling point, not merely an operational metric.
Laboratory Swabs Market
Risks and Uncertainties
Despite favorable growth dynamics, several uncertainties warrant caution. Regulatory timelines and requirements can shift, altering validation burdens and market access for certain collection products. Quality events can damage trust quickly, especially when large volumes are involved or when affected products reach vulnerable end users. In addition, raw material cost pressure and capacity constraints can compress margins in commoditized segments, while disease surveillance patterns and testing behavior can influence demand in ways that are difficult to predict far in advance. Companies that assume linear growth without preparing for these variability factors may find their positioning weaker than expected during disruption.
Implications for Decision-Makers
The strategic implications vary by role, but a few priorities cut across the market.
For Manufacturers
Focus on the basis of differentiation. If the product is essentially commoditized, cost discipline, reliable delivery, and strong supplier documentation will be essential. If the product competes on performance, invest in clinically relevant validation, workflow compatibility, and clear evidence that supports preference. In either case, quality systems and traceability are not optional; they are part of the commercial proposition. Manufacturers should also consider whether their portfolio is positioned for the shift toward integrated collection and preservation solutions, where value is created through specimen integrity and process efficiency rather than through the swab alone.
For Investors
Look beyond top-line growth. The market's expansion is encouraging, but value creation will be uneven. Companies with regulatory competence, application-specific expertise, and resilient supply chains are better placed to defend margins and capture preference in regulated segments. Equally important is the risk profile: recall exposure, raw material sensitivity, and dependence on a narrow demand channel can undermine otherwise attractive growth narratives. In this environment, diligence should place substantial weight on quality controls, validation capability, procurement relationships, and geographic or channel concentration.
For Procurement and Supply Chain Leaders
Treat swabs and related consumables as risk-managed inputs rather than interchangeable commodities. Qualification criteria should include not only price and pack configuration, but also documentation supporting sterility, lot control, compatibility with intended workflows, and the supplier's ability to respond to quality events. Where possible, structure sourcing to balance cost with resilience, and maintain visibility into alternative suppliers for critical formats. In regulated environments, procurement decisions increasingly affect downstream diagnostic reliability, so the cost of poor supplier selection can extend well beyond the purchase price.
Getting the Full Picture
This market is moving on multiple axes at once: material performance, regulatory expectations, supply resilience, and workflow integration. For organizations making sourcing, product, or investment decisions, the relevant question is less about whether the market will grow and more about where the next round of differentiation and risk will emerge. Detailed segmentation data, company-level profiles, and scenario-based projections can materially sharpen those decisions, especially when the goal is to align strategy with the specific formats, geographies, and applications most relevant to a given business. For readers seeking a deeper, data-rich view of the medical swab market, a full research report can provide the granular segmentation, competitive benchmarking, and forward-looking detail needed to turn these strategic themes into actionable plans.
For detailed analysis of this topic, please visit the official page: Medical Swab Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


