



Nanocrystalline Soft Magnetic Material Market: Why the 9.2% CAGR Redefines Growth

Strategic Trends and Commercial Opportunities in the Nanocrystalline Soft Magnetic Material Market
The global market for nanocrystalline soft magnetic materials has entered a phase of accelerated structural expansion, driven by the convergence of power electronics evolution and the electrification of energy infrastructure. Base year market valuation for 2025 reached 1.8 billion USD, building on a consistent upward trajectory from 1.15 billion USD in 2020. The compound annual growth rate of 9.2 percent across the forecast horizon through 2032 signals that demand is not merely cyclical but structurally reinforced. By the end of the decade, total market value is projected to approach 3.34 billion USD, with meaningful compounding acceleration in the latter half of the window as high-frequency distribution networks, grid-connected power conversion, and advanced motor platforms reach commercial inflection points. This growth profile places nanocrystalline soft magnetic materials at the intersection of material science performance and system-level efficiency requirements, creating a landscape where competitive advantage is increasingly determined by supply chain resilience, application-specific material engineering, and the ability to scale precision manufacturing.
Three operational realities define the current market environment. First, the performance advantages of nanocrystalline alloys in high-frequency, low-loss applications are well established, yet translating laboratory-grade permeability and core loss characteristics into cost-competitive, volume-ready components remains a persistent execution challenge. Thin ribbon production, controlled annealing, and precision core assembly require tightly integrated process control, and any variability in material consistency directly impacts end-use efficiency metrics. Second, raw material cost pressure continues to shape margin dynamics and sourcing behavior across the value chain. The specialized alloy inputs, processing reagents, and precursor materials required for nanocrystalline fabrication sit within a broader metals and minerals environment where price volatility and availability constraints influence both production planning and downstream pricing architecture. Third, the market is navigating a transition from application-specific prototyping to scaled commercial deployment. Early adoption has been strongest where performance gains justify premium material costs, but broader penetration now depends on demonstrable total cost of ownership advantages, reliable vendor qualification, and supply continuity across long program lifecycles. These conditions create a market that rewards operators who can align material innovation with manufacturing discipline and customer-facing system value.
Technical Innovation and Performance Thresholds
The most durable growth catalyst in this market remains the ongoing improvement in soft magnetic performance at increasingly demanding operating conditions. Nanocrystalline architectures continue to offer compelling combinations of high permeability, low coercivity, and reduced core loss relative to conventional alternatives, which makes them especially attractive in applications where switching frequency is rising and thermal headroom is shrinking. The practical impact of these material characteristics is visible in power conversion architectures that must handle higher power density without proportional increases in size, weight, or losses. As inverter-based systems, regulated power supplies, and high-efficiency distribution components push toward higher frequency operation, the ability of nanocrystalline cores to maintain magnetic performance while reducing eddy current and hysteresis losses becomes a direct enabler of system miniaturization and efficiency gains.
Innovation is not limited to intrinsic material properties. A meaningful portion of competitive differentiation now comes from how materials are integrated into finished magnetic components. Ribbon geometry, core winding techniques, insulation strategies, and assembly tolerances all influence real-world performance, and leading suppliers are increasingly positioning themselves as solutions partners rather than commodity material vendors. This shift matters because system designers often value predictable magnetic behavior, consistent qualification data, and design-in support as much as the base material specification. Companies that can provide application-engineering support, custom core geometries, and reliable process repeatability are better positioned to capture long-cycle design wins, particularly in sectors where re-qualification costs and program duration make switching suppliers a high-friction decision.
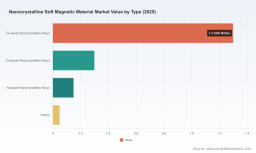
A second dimension of technical progress is the expanding range of alloy formulations and processing variants that address different cost-performance trade-offs. While iron-based nanocrystalline alloys dominate volume deployment due to their balance of performance and relative input accessibility, cobalt-based and nickel-based variants serve more specialized requirements where specific magnetic, thermal, or corrosion-related characteristics are prioritized. The strategic implication is that material selection is becoming more application-mapped rather than one-size-fits-all. Manufacturers that can match alloy chemistry, ribbon architecture, and finishing processes to defined end-use profiles are more likely to secure sustained demand in segments where performance validation cycles are long and switching costs are high.
Policy, Regulation, and the Electrification Imperative
Regulatory and policy environments are reshaping demand indirectly but powerfully by accelerating the deployment of efficient electrical infrastructure and power conversion equipment. Energy efficiency objectives across industrial, commercial, and consumer applications continue to push designers toward components that reduce losses across the operating envelope. In parallel, the broader push toward electrification in mobility, distributed energy systems, and modernized grid equipment is increasing the installed base of transformers, motors, inductors, chokes, and magnetic sensors that rely on optimized soft magnetic materials. These demand-side shifts are not uniform, but they create a durable tailwind for materials that can support higher efficiency, smaller form factors, and more reliable performance in power-handling applications.
Compliance and qualification frameworks also influence market dynamics by raising the value of proven material consistency and documented performance. In applications where safety, reliability, and long-term operational stability are central, the ability to provide traceable material data and repeatable production quality becomes a competitive asset. This dynamic advantages established suppliers with mature process control and testing infrastructure, while also creating a higher barrier for new entrants that lack demonstrated manufacturing discipline or application validation history. At the same time, policy-driven electrification and efficiency programs are expanding the potential addressable base beyond traditional industrial power electronics, creating incremental demand in areas where nanocrystalline materials were previously evaluated only for niche, performance-critical roles.
Demand-Side Shifts and Application Migration
Demand patterns are evolving as end-use sectors adopt power electronics architectures that place stricter requirements on core materials. Transformers remain a central application category because of their foundational role in voltage transformation, isolation, and power distribution across multiple industries. High-frequency transformer designs in particular benefit from low-loss magnetic cores, especially where size constraints and efficiency requirements must be balanced. Electric motors are another important demand node, especially as motor-driven systems continue to gain share in applications that prioritize energy efficiency and precise control. Inductors and chokes also contribute meaningful demand, particularly in power conditioning, filtering, and converter stages where magnetic performance directly affects signal integrity and efficiency.
Magnetic sensors represent a smaller but strategically relevant application segment. While volume is lower than in power-handling applications, sensor-grade magnetic components often require controlled magnetic response and stability, which makes advanced soft magnetic materials relevant where precision matters. The broader pattern is a gradual migration of nanocrystalline material into an expanding set of designs where its performance profile is not merely advantageous but functionally necessary. This migration is especially significant because design-in decisions in these categories often have multi-year implications for component volumes. Once a material and core architecture are embedded in a product platform, procurement tends to follow repeatable sourcing patterns unless a superior alternative is validated through a formal engineering review. As a result, early design-stage engagement and reliable sample-to-production continuity have become strategically valuable.
Supply Chain Realignment and Cost Structure Pressures
Cost structure dynamics are playing an increasingly important role in shaping competitive outcomes. Soft magnetic alloy inputs and associated processing materials continue to create cost pressure that can restrain broader market expansion if not managed carefully. This pressure is not simply a question of price levels; it also reflects the complexity of maintaining consistent material quality while managing variable input costs, logistics constraints, and supply continuity. In a market where successful components depend on reproducible magnetic performance, sourcing instability can disrupt both production schedules and customer confidence.
In response, several industry players are pursuing supply-side coordination strategies aimed at reducing exposure to critical input volatility. Strategic cooperation with upstream suppliers of key materials is emerging as one approach to securing continuity for the specialized oxide and alloy inputs used in nanocrystalline processing. These arrangements can help stabilize production planning and reduce the risk of qualification delays caused by material inconsistency or availability gaps. The commercial logic is straightforward: in segments where program timelines are long and qualification cycles are expensive, supply assurance can be as valuable as unit cost optimization. This shift also encourages vertical coordination, where processors and fabricators align more closely with primary material producers to reduce handoff friction, improve consistency, and manage total cost more effectively.
Manufacturing scale and facility capability are likewise becoming central to competitive positioning. The companies expanding physical production capacity are doing so not only to meet volume demand but also to protect lead times, support custom product variants, and improve the reliability of delivery across multiple geographies. Capacity expansion is particularly relevant where OEM and custom assembly demand is growing, because end-use customers increasingly expect suppliers to handle more of the fabrication and integration work rather than stopping at material supply. In this context, the ability to move from ribbon or material sale to finished core, ring, or assembly supply can create stronger commercial relationships and better margin structures.
Competitive Landscape and Leading Strategies
The competitive structure of this market reflects a mix of specialized primary producers, downstream processors, and regional manufacturers serving distinct customer bases. CR3 concentration of 47.5 percent and CR5 concentration of 68.2 percent indicate a market where a relatively small group of established players holds a substantial share, but where meaningful participation is still possible through differentiated positioning, regional focus, or application specialization. The leading firms tend to compete on a combination of material pedigree, process maturity, application support, and supply reliability rather than price alone. This is consistent with a market in which performance validation, repeatability, and customer engineering support are decisive in winning and retaining design wins.
Proterial stands out as a pioneer and primary producer of FINEMET® nanocrystalline soft magnetic materials and related cores for high-frequency transformers and power electronics. Its strategic positioning is anchored in long-standing material expertise and an established reference base in high-frequency power applications. The company's advantage derives from the combination of proprietary material heritage, proven core performance, and the credibility that comes from being closely associated with a recognized material platform. In practice, that kind of positioning can reduce adoption friction for engineers familiar with the material family and can help secure participation in programs where material history and qualification data carry significant weight.
Worldwide Nano Crystalline Soft Magnetic Materials Market
VACUUMSCHMELZE operates as a leading producer of VITROPERM® iron-based nanocrystalline soft magnetic ribbons and tape-wound cores optimized for low losses and high permeability. Its emphasis on low-loss performance and high permeability aligns directly with the efficiency and power density requirements that are expanding demand across transformer and power electronics applications. The company's recent move to secure high-purity rare earth oxides through a strategic alliance underscores the growing importance of input security in maintaining consistent alloy processing and product quality. This type of upstream coordination is a practical signal that leading suppliers are treating raw material assurance as part of their competitive infrastructure, not simply as a procurement function.
Metglas operates as a commercial producer of FINEMET®-based and FINEMET®-compatible nanocrystalline soft magnetic ribbons and foil for transformer and power applications. Its role in the landscape illustrates the value of material compatibility and supply scale in markets where downstream fabricators and OEMs need predictable access to compatible core materials. By offering ribbons and foils that fit established application requirements, such producers support the broader ecosystem of transformer and power component manufacturers that rely on stable input supply and recognizable material behavior.
Chinese manufacturers are increasingly relevant in this landscape, both as material producers and as specialists in cores, ribbons, and assemblies. China Amorphous Technology Co., Ltd. has established a manufacturing footprint in amorphous and nanocrystalline soft magnetic materials, cores, and ribbons for electronic components and transformers, positioning it as a participant in both material supply and component-level fabrication. Dongguan JH Amorphous Co., Ltd. has taken a different but complementary path by focusing on custom and OEM nanocrystalline and amorphous soft magnetic cores, rings, and assemblies for power electronics. Its recent milestones—mass production launch of a custom nanocrystalline magnetic ring assembly for a leading Italian electronics manufacturer following two years of testing, and a subsequent facility expansion to add capacity for nanocrystalline and amorphous soft magnetic cores—illustrate how a manufacturer can build competitiveness through application-specific engineering, long validation cycles, and capacity investment that supports repeat supply.
Several additional players reinforce the breadth of the value chain. MK Magnetics fabricates tape-wound nanocrystalline soft magnetic cores using materials from primary suppliers, highlighting the role of downstream processing and core manufacturing as a distinct competitive layer. Bomatec supplies and processes nanocrystalline soft magnetic ribbons, products, and components for magnetic applications, occupying a position that bridges material supply and component-level delivery. Londerful New Material Technology Corp. provides nanocrystalline soft magnetic materials and components targeted at export markets including Japan, Korea, and Europe, which reflects the growing internationalization of production capacity and the importance of export-focused manufacturing strategies in this market.
Looking across this landscape, several strategic patterns emerge. One is the growing importance of differentiated application support. The most defensible positions are increasingly found where suppliers can combine material capability with core fabrication, custom engineering, and reliable delivery for specific end-use segments. Another is the shift toward supply coordination and capacity investment as competitive tools. In a market where consistency and continuity matter, firms that reduce input risk and expand manufacturing capability are better positioned to retain customers and capture volume growth. A third pattern is the coexistence of consolidation pressure and fragmentation opportunity. Established leaders hold significant share, yet regional manufacturers and custom-oriented suppliers continue to grow by serving specialized demand, export markets, and OEM programs that prioritize tailored solutions over standardized commodity supply.
Soft Magnetic Materials Market
The market also appears to be evolving through selective integration rather than uniform concentration. Where application requirements are highly standardized and material performance is the main differentiator, scale and material heritage matter most. Where demand is customized, program-specific, or regionally concentrated, flexibility, engineering responsiveness, and assembly capability can be equally important. This duality suggests that competitive strategy in this market is not monolithic; it depends on which segment a company targets and how much value it captures at the material level versus the component and system-integration level.
Forward Outlook: Key Trends Shaping the Next Three to Five Years
One of the clearest forward trends is the continued expansion of nanocrystalline soft magnetic materials into higher-power-density, higher-frequency applications. As power conversion architectures evolve and efficiency expectations rise, the value proposition of low-loss, high-permeability cores becomes more widely relevant. This trend supports steady demand growth across transformers, motors, inductors, and chokes, and it also increases the importance of consistent material performance at operating conditions that push beyond legacy design envelopes. The commercial opportunity here lies not only in selling material, but in helping customers realize system-level benefits through optimized core selection, geometry, and assembly.
A second trend is the likely deepening of supply chain coordination around critical inputs and specialized processing materials. As manufacturers seek to reduce exposure to raw material cost volatility and availability risk, partnerships, alliances, and long-term sourcing arrangements are expected to become more common. This should benefit suppliers that can demonstrate reliable input security, repeatable process control, and the ability to scale without compromising material quality. It also suggests that competitive advantage may increasingly depend on how effectively a company manages the full chain from precursor materials to finished magnetic components, rather than competing solely on isolated product specifications.
PW Consulting
A third trend is the gradual broadening of regional manufacturing and export-oriented capacity. Demand growth is global, but customer expectations around lead time, customization, and local support are creating incentives for regionally positioned production and tailored export strategies. Companies building capacity for international markets, especially where design-in support and OEM collaboration are emphasized, may be able to capture share by reducing friction in the qualification and delivery process. This trend is particularly relevant for buyers who value supply resilience and want to avoid over-reliance on a single sourcing geography.
These trends carry opportunity, but they also come with meaningful risk. Raw material cost pressure remains a genuine constraint, and any prolonged cost escalation could slow adoption in price-sensitive segments or compress margins for suppliers unable to offset input costs through value-added services or efficient manufacturing. Technology substitution risk also persists, since alternative soft magnetic materials and competing core architectures continue to improve. The market is unlikely to be disrupted overnight, but incremental gains by alternative materials in specific applications could limit nanocrystalline growth in some segments unless performance differentiation remains clear. Finally, qualification cycles and long program timelines mean that demand growth can be lumpy: design wins take time to convert into volume, and supply chain or validation delays can postpone commercialization even when market interest is strong.
Strategic Recommendations for Decision Makers
For manufacturers and material suppliers, the priority should be to strengthen the link between material performance and customer-facing value. This means investing in application engineering, custom core and assembly capability, and process consistency that supports reliable qualification. The companies best positioned to grow are those that can move beyond material specification sheets and demonstrate repeatable performance in real application conditions, while also protecting supply continuity for critical inputs. Building or reinforcing upstream coordination, expanding capacity where demand is validated, and developing a clear narrative around performance-to-cost trade-offs will be especially valuable as the market matures and customers become more selective about sourcing partners.
For investors, the most important question is not whether the market is growing, but which business models are capturing durable value within that growth. There is a meaningful difference between exposure to raw material supply, ribbon production, core fabrication, and finished assembly, and the economics of each can vary significantly with scale, customer mix, and input cost management. Interest should be directed toward operators with proven qualification records, visible demand anchors in transformers, motors, power electronics, or sensor applications, and a credible strategy for handling raw material volatility. Capacity expansion announcements are informative, but they should be evaluated alongside customer validation history, supply chain resilience, and the ability to transition from pilot programs to sustained volume production.
For procurement and sourcing leaders, the strategic task is to balance performance requirements with supply risk and long-cycle program stability. Nanocrystalline materials can deliver real efficiency and size advantages, but those advantages are most achievable when sourcing relationships provide consistency, documented performance data, and dependable delivery over the life of a program. Where possible, qualification strategies should include redundancy planning, evaluation of regional sourcing options, and attention to upstream input security that may affect future price and availability. In addition, engaging suppliers early in the design process can reduce the risk of costly redesigns later and improve the likelihood of securing reliable production allocation when demand scales.
For any organization making decisions in this market, the value of current, granular intelligence is high. Regional dynamics, application-specific volume patterns, competitive moves, and raw material developments can change the practical meaning of headline growth trends quickly. A broad market number is useful orientation, but it rarely provides enough precision for sourcing strategy, investment allocation, or product roadmap decisions. More detailed breakdowns of segment demand, competitive positioning, and supply-side developments are necessary to turn directional growth into actionable plans.
Readers seeking a more detailed view of these dynamics, including deeper segmentation data, competitive benchmarking, and tailored recommendations aligned to specific business objectives, can access the full research report for expanded analysis and supporting data.
For detailed analysis of this topic, please visit the official page: Nanocrystalline Soft Magnetic Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


