



Rotary Indexer Market 2026–2032: Why 5.49% CAGR Belies Real Demand Shifts

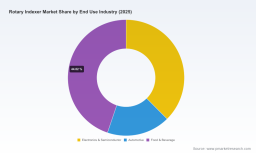
Rotary Indexer Market: Strategic Trends & Commercial Opportunities 2025–2032
The rotary indexer market has entered a decisive growth phase, transitioning from a niche automation component to a critical enabler of high-speed, precision manufacturing. Current market valuations reflect a mature yet expanding ecosystem, with revenue projections indicating a steady climb over the next seven years. The industry is characterized by a relatively fragmented competitive landscape, where no single player dominates the value chain, creating space for differentiated positioning and strategic consolidation. For executives and investors, the opportunity lies not merely in riding volume growth but in aligning product portfolios, supply chain resilience, and compliance frameworks with the shifting demands of digitally integrated factories.
At its core, the market is being reshaped by the intersection of automation economics, regulatory tightening, and the need for modular, adaptable motion control solutions. The following analysis maps the structural forces at play, the competitive dynamics defining winners and laggards, and the strategic moves that stakeholders should consider as the market matures through the late 2020s.
Market Snapshot & Core Challenges
The rotary indexer market has demonstrated consistent expansion over the past half-decade, with revenue trajectories pointing toward a multi-billion-dollar footprint by the early 2030s. Growth is underpinned by the broader industrial automation cycle, where manufacturers seek to compress cycle times, reduce labor dependency, and increase repeatability in high-mix environments. Yet the headline numbers obscure the operational friction that many market participants face.
Three challenges are particularly salient for decision-makers navigating this landscape.
1. Compliance fragmentation across regions. Rotary indexer deployments operate under a patchwork of safety and machinery standards. In North America, electrical safety and reliability expectations center on UL certification, while European installations must meet the Machinery Directive with CE marking. Chinese markets require GB/T 5226.1 certification, and Indian industrial deployments increasingly reference IS/ISO 12100 standards. This regulatory diversity raises the cost of market entry, complicates product certification pathways, and forces manufacturers to design for multiple compliance regimes rather than a single global footprint.
2. Supply chain volatility from geopolitical and trade pressures. Production schedules for rotary indexers are increasingly exposed to disruptions stemming from geopolitical tensions and trade restrictions. Component sourcing, lead time predictability, and logistics continuity have become strategic variables rather than purely operational concerns. For buyers, this translates into elevated inventory risk; for suppliers, it means rethinking sourcing strategies, regional assembly models, and buffer capacity.
3. The push for flexibility versus fixed-cycle efficiency. Traditional indexing solutions excel in high-volume, low-mix environments where cycle consistency is paramount. Yet many end-use sectors are pivoting toward higher mix variability, shorter production runs, and rapid reconfiguration. This demand shift pressures vendors to deliver indexers that can adapt without sacrificing precision, torque, or throughput—creating tension between mechanical simplicity and programmable adaptability.
Worldwide Fixed Rotary Index Tables Market
Key Demand Drivers
The market's trajectory is not incidental; it is being pulled forward by intersecting technological, regulatory, and demand-side forces that reshape how rotary indexers are specified, integrated, and valued.
PW Consulting Automotive & Machinery Research Center
Technology Innovation & Breakthroughs
The most visible shift is the integration of programmable controls, servo-driven architectures, and digital interfaces into rotary indexing platforms. Fixed-station and cam-driven designs continue to hold relevance where cycle repetition is high and predictability is the priority, but servo-driven and ring-drive variants are gaining traction in applications requiring variable division, dynamic load handling, and tighter coordination with broader PLC ecosystems. Advances in torque density, moment-load capacity, and motion control precision are expanding the addressable envelope for rotary indexers in heavier-duty and higher-accuracy contexts.
Beyond hardware, the trend toward seamless integration is redefining value. Indexers that can be configured for independent operation or embedded within larger automation cells are increasingly preferred by engineering teams that want to reduce integration friction. The emphasis is shifting from standalone component performance to system-level compatibility—signal compatibility, mounting modularity, and control interoperability.
Policy & Regulatory Environment
Regulatory frameworks are simultaneously a constraint and a catalyst. Safety mandates are pushing manufacturers toward more rigorous design validation, documentation, and certification processes. While this raises upfront engineering and compliance costs, it also creates a barrier that favors established players with mature quality systems and reduces the risk of costly field failures. In practice, compliance readiness is becoming a competitive differentiator, especially in regulated end markets where downtime, safety incidents, or audit findings carry significant financial and reputational consequences.
At the same time, regional certification requirements are encouraging localized engineering support and distribution partnerships. Vendors that can navigate multiple standards without fragmenting their product lines too thinly are better positioned to scale across jurisdictions without sacrificing margin or speed-to-market.
Demand-Side Shifts in Buyer Behavior
Procurement and engineering teams are no longer buying rotary indexers solely on cycle speed or base price. They are evaluating total cost of ownership, integration effort, serviceability, and the ability to adapt to future line reconfigurations. This is particularly true in assembly-intensive and packaging-heavy operations, where changeover frequency and line modularity directly affect operational economics.
There is also a growing preference for solutions that can support partially automated and buffer-oriented workflows, rather than forcing full-line automation where it is not yet justified. Pneumatic and hybrid configurations remain relevant in these contexts, offering a pragmatic balance between cost, simplicity, and incremental automation. The broader implication is that segmentation by product type is becoming less about mechanical taxonomy and more about matching solution profiles to specific automation maturity levels.
Supply Chain & Cost Structure Evolution
Cost dynamics are being reshaped by both component availability and the broader industrial automation supply base. Geopolitical tensions and trade restrictions are introducing uncertainty into sourcing and scheduling, prompting manufacturers to weigh single-source dependencies against multi-region resilience. This is encouraging a reevaluation of bill-of-materials strategy, regional stocking models, and the role of local assembly or finishing operations.
For end-users, the result is a more cautious procurement posture: longer lead-time planning, greater emphasis on supplier reliability, and increased willingness to pay for predictability and field support. For vendors, the imperative is to build supply chain transparency, safeguard critical component availability, and communicate lead-time expectations clearly—because reliability is increasingly as valuable as unit price in competitive bidding environments.
Competitive Landscape & Leading Strategies
The competitive field in the rotary indexer market is diverse, with players differentiated by technology focus, geographic reach, and integration capability. No single entity commands a dominant share, which means competitive advantage is increasingly derived from specialization, partnership networks, and the ability to deliver sector-specific solutions rather than from sheer scale alone.
Differentiated Positioning Among Leading Companies
Several firms illustrate the breadth of strategic approaches currently shaping the market.
- Motion Index Drives focuses on cam-driven rotary indexing tables and custom solutions for high-cycle automation, with emphasis on aerospace, automotive, and packaging applications. Its positioning leans toward engineered, application-specific designs where cycle fidelity and durability are paramount.
- Nexen Group emphasizes servo and ring-drive rotary indexers with high-torque and moment-load capacity, targeting precision industrial positioning where load handling and accuracy are central requirements.
- WEISS GmbH produces programmable and fixed-station rotary indexing tables with digital controls and integration capabilities, serving automotive, medical, and electronics assembly. Its recent activity underscores a dual strategy of market presence and technology collaboration.
- Destaco develops mechanical and servo rotary indexers, roller dials, and drives for assembly and packaging equipment, aligning its portfolio with the needs of equipment builders and end users in high-throughput environments.
- Sanko Automation manufactures hollow and fixed-station rotary indexing tables with programmable controls for factory automation, reflecting a growing pool of regionally anchored manufacturers serving broader automation demand.
- Centricity Automation offers servo rotary indexers aligned with PLC-integrated and independent high-precision assembly applications, positioning around control integration and precision execution.
- Taktomat GmbH supplies rotary indexers with fixed and flexible division for high-speed production lines, emphasizing throughput and division flexibility in fast-cycle contexts.
- TallMan Robotics designs shaft-output rotary indexers and cam index drives for engineered automation motion, targeting applications where tailored motion paths and mechanical integration matter.
- Festo offers pneumatic rotary indexing tables suited to partially automated and buffer systems, reinforcing a role for simpler, cost-effective motion solutions where full servoization is not yet warranted.
The strategic throughline is clear: suppliers are differentiating through a combination of motion architecture, control integration, and vertical application focus. Companies that can articulate where their strengths lie—high torque, programmability, speed, integration ease, or cost efficiency—are better positioned to defend margins and win specification decisions.
Market Evolution: Consolidation, Specialization, and New Entry
The market's relatively fragmented concentration leaves room for both consolidation and further specialization. On one path, larger automation groups or component conglomerates may seek to expand their motion control portfolios through acquisitions or partnerships, aiming to offer end-to-end indexing and handling solutions. On another, agile specialists will continue to carve out niches around programmable control, sector-specific compliance, or regional service networks.
New entrants are likely to emerge where they can combine cost-competitive manufacturing with credible control integration and compliance readiness. However, entry alone is insufficient; success will depend on navigating certification landscapes, establishing reliable supply chains, and demonstrating integration compatibility within existing automation ecosystems. The more enduring competition will be around ecosystem fit—how well an indexer aligns with the control architecture, safety requirements, and throughput expectations of the target application.
Forward Outlook: Three Trends to Watch
Looking ahead to the mid-to-late 2020s and into the early 2030s, three trends are likely to shape commercial outcomes in this market.
Trend 1: Programmable and Servo-Enabled Indexers Will Capture a Growing Share of New Installations
The pull toward flexible division, variable cycle control, and tighter integration with digital automation architectures will continue to shift specification preferences toward servo-driven and programmable platforms, particularly in assembly, electronics, and medical contexts where changeover and precision matter. This does not eliminate cam-driven or pneumatic solutions, but it reallocates growth toward architectures that support reconfiguration and coordinated motion. Commercial opportunity lies in offering scalable control options, clear migration paths from fixed to programmable modes, and integration support that lowers engineering burden for buyers.
Trend 2: Compliance Readiness Will Become a Market Access Discipline, Not a Back-Office Task
As safety and machinery standards continue to shape procurement decisions, vendors that treat certification and documentation as strategic capabilities will have an advantage in multi-region selling. This includes proactive alignment with regional requirements, consistent quality systems, and the ability to provide buyers with clear compliance evidence. For manufacturers, the upside is reduced friction in specification approvals and fewer delays in deployment; for buyers, the value is lower risk and faster commissioning. The uncertainty lies in the pace and variability of regulatory updates across jurisdictions, which can alter certification roadmaps without much warning.
Trend 3: Supply Chain Resilience Will Differentiate Suppliers in Competitive Bids
Geopolitical tension and trade restrictions are likely to remain structural factors rather than transient disruptions. Manufacturers that invest in diversified sourcing, regional inventory strategies, and transparent lead-time communication will be favored by procurement teams under pressure to protect production schedules. This creates a commercial opportunity for suppliers who can Demonstrate reliability as a deliberate capability—through regional assembly, buffer stock planning, and predictable delivery commitments—rather than treating it as a reactive fix. The risk is that resilience investments raise cost bases if not managed with disciplined operations and demand forecasting.
Strategic Moves for Decision-Makers
The rotary indexer market rewards stakeholders who align their actions with the structural shifts already underway. The following considerations are most relevant for manufacturers, investors, and procurement leaders.
For Manufacturers and Solution Providers
- Clarify your motion architecture positioning. Decide where you compete—high torque, programmability, speed, integration ease, or cost efficiency—and ensure product naming, documentation, and sales narratives reinforce that choice rather than diluting it across every possible feature.
- Strengthen compliance as a product attribute. Build certification pathways and documentation into the product development cycle so that multi-region deployment does not become a last-minute engineering scramble.
- Invest in integration-friendly design. Prioritize mounting modularity, control compatibility, and clear communication interfaces to reduce the engineering lift for equipment builders and end users.
- Plan supply chain resilience deliberately. Map critical components, evaluate regional sourcing options, and communicate realistic lead times as part of your value proposition.
For Investors
- Evaluate ecosystem fit over unit pricing. Companies that can embed their indexers into broader automation workflows—through integration support, compliance readiness, and service networks—are more likely to secure durable specification wins.
- Watch for consolidation signals around motion control. The fragmented concentration suggests potential for portfolio expansion through acquisition, particularly where buyers are seeking integrated handling and indexing capabilities.
- Assess exposure to regulatory complexity. Firms with mature quality systems and multi-region certification experience are better positioned to scale without being blocked by compliance delays.
For Procurement and Engineering Leaders
- Specify for total deployment cost, not just purchase price. Factor in integration effort, lead-time risk, field support, and reconfiguration flexibility when comparing alternatives.
- Align solution choice with automation maturity. Pneumatic and fixed-cycle options may be appropriate where partial automation or buffer systems are in use, while servo-driven and programmable platforms fit lines that require frequent reconfiguration or precise coordination.
- Engage suppliers early on compliance and integration requirements. Early alignment on safety standards, control compatibility, and documentation can materially reduce commissioning risk and schedule slippage.
Closing Perspective
The rotary indexer market is moving from component-level competition to solution-level value creation. Growth will continue, but the distribution of advantage will favor players who can combine motion performance with integration ease, compliance readiness, and supply chain reliability. For manufacturers, that means sharpening positioning and treating certification and resilience as strategic capabilities. For investors, it means looking beyond headline pricing to ecosystem fit and durability of specification wins. For procurement and engineering teams, it means specifying for deployment reality—total integration effort, reconfiguration potential, and predictable delivery—rather than chasing the lowest unit cost in isolation.
The commercial landscape will keep evolving as programmable architectures expand, regulatory expectations intensify, and supply chain considerations become a more explicit part of buying decisions. Stakeholders who map these forces to their own product strategies, investment theses, and sourcing criteria will be better positioned to capture the upside while managing the inherent uncertainty of a market in transition.
Rotary Encoders Market
For detailed analysis of this topic, please visit the official page: Rotary Indexer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


