



7 Strategic Shifts Driving the Electronic Components Market to $717.6B by 2032

The Electronic Components Market: Strategic Trends and Commercial Opportunities Through 2032
The electronic components sector has transitioned from a commodity-driven business into a technology-intensive, strategically critical industry. Over the historical period from 2020 through 2025, global revenue climbed from approximately $300 billion to over $438 billion, reflecting an average compound annual growth rate of 7.36 percent across the full forecast horizon extending to 2032, when the market is projected to exceed $717 billion. This trajectory is not merely a recovery from supply disruptions of the early 2020s; it reflects a structural realignment driven by electrification, connectivity mandates, industrial automation, and a reconfiguration of global manufacturing footprints. The current landscape presents a paradox for decision makers: demand volumes are robust and accelerating, yet availability, cost structures, and competitive positioning are being reshaped by forces that do not always move in tandem.
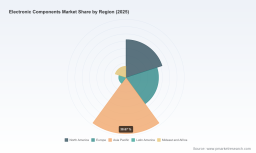
Understanding where value will concentrate, which capabilities will command premiums, and how supply-chain architecture will evolve requires looking beyond headline volumes. The segmentation of the market by component type reveals a hierarchy of strategic relevance that is not always intuitive. Active components continue to anchor the largest share of revenue, reflecting their centrality to integrated circuits, analog and power management, and embedded control functions. Passive components represent a substantial and often underestimated revenue pool, driven by demand for capacitors, inductors, resistors, and RF modules that scale directly with the complexity of electronic assemblies. Electromechanical components, while smaller in relative terms, serve as critical enablers for connectors, switches, and sensors that bridge electrical and mechanical systems. By application, consumer electronics remains the largest end-use driver, followed by telecommunications, industrial, medical, automotive, and a diversified remainder that spans aerospace, test and measurement, and specialized instrumentation. Regionally, Asia Pacific leads in volume, with North America and Europe maintaining meaningful shares supported by design activity, high-value manufacturing, and policy-driven incentives.
Any realistic strategy must be built on these structural realities. The market's growth is not uniform across products or geographies; it is uneven, with pockets of intense competition, long lead times, and pricing volatility coexisting alongside segments where differentiation and reliability command durable margins. For executives and investors, the task is to map their exposure to the segments where the economics are most favorable, and to anticipate the inflection points that will separate winners from laggards.
Market Context: Baseline Dynamics and Critical Junctures
A Growth Profile That Rewards Timing and Positioning
The market's expansion from 2020 to 2025 was propelled by a confluence of restocking after pandemic-era shortages, the acceleration of automotive electrification, the proliferation of connected devices, and sustained capital expenditure in industrial and infrastructure electronics. The forward trajectory through 2032 reflects continued momentum, but with a widening dispersion of opportunity. The overall growth rate of 7.36 percent over the forecast period is meaningful, yet it conceals divergent sub-trends: components tied to high-growth applications will outpace the average, while mature commodity categories may experience pricing pressure and cyclical volatility. The implication is that aggregate market size is a useful sanity check, but it is insufficient for tactical planning. Companies need to align their portfolios with the application and technology vectors that are expanding faster than the baseline.
Three Junctures Redefining the Playing Field
First, supply-chain resilience has moved from an operational concern to a strategic lever. Lead-time variability remains a practical challenge for certain categories, particularly automotive-grade microcontrollers and specialized discrete devices, where procurement teams report extended delivery windows for select product lines. This is not a transient inconvenience; it is a structural feature of a market where qualified production capacity for high-reliability parts does not always scale in lockstep with demand. Organizations that treat sourcing strategy as a core competency, rather than a transactional function, can convert lead-time risk into negotiating leverage and preferential access.
Second, the regulatory and sustainability agenda is reshaping cost structures and competitive dynamics. Carbon-related mechanisms, including the EU Carbon Border Adjustment Mechanism, have begun publishing certificate pricing data, signaling that environmental compliance will be increasingly priced into cross-border trade. For component manufacturers and distributors, this creates both operational complexity and differentiation potential: firms that can demonstrate transparent, lower-carbon supply chains and efficient material utilization will be better positioned for markets where procurement criteria are expanding beyond performance and price.
Third, the balance between integration and fragmentation is shifting. Large incumbents continue to consolidate capabilities across analog, power, microcontrollers, and sensing to serve high-value applications, while independent distributors and niche specialists gain relevance by offering speed, accessibility, and hard-to-source inventory. At the same time, new manufacturing initiatives and partnerships are being deployed to stabilize supply in discrete and power categories, indicating that regional diversification and capacity partnerships are becoming permanent features of the landscape rather than one-off remedies.
Key Drivers Reshaping the Market
Technology Innovation and Breakthroughs
The most consequential technology trends are converging around power semiconductors, analog and precision ICs, and the integration of sensing with processing. Wide-bandgap devices based on silicon carbide and gallium nitride are expanding the addressable range for higher-efficiency power conversion, a theme especially relevant for electric vehicles, industrial drives, and renewable-energy systems. Companies with strong positions in power semiconductors and discrete devices are investing in manufacturing and product roadmaps that target these applications, while also extending into intelligent sensing and connectivity solutions that bridge functional domains. In parallel, the push toward physically aware and secure architectures is prompting collaboration around hardware anchored in AI edge platforms, with security and reliability increasingly treated as core product attributes rather than add-ons. These advancements are not abstract; they translate into higher value per unit, longer lifecycle relevance, and greater switching costs for customers who standardize on qualified solutions.
Policy and Regulatory Environment
Policy is now an active force in shaping where production occurs, what qualifies as a compliant component, and how trade flows are priced. Incentive programs and local-content expectations have encouraged investment in new fabrication and assembly capacity across multiple regions, reducing over-concentration risk while simultaneously complicating multi-site qualification. Regulatory instruments tied to carbon intensity are becoming operational realities, with certificate pricing now visible to market participants. This trend elevates the strategic importance of supply-chain transparency, material efficiency, and energy-aware manufacturing. For buyers, it introduces a new dimension to supplier evaluation; for manufacturers, it rewards those who can quantify and reduce the footprints associated with their products. Policy is no longer a background condition. It is a variable in cost, access, and go-to-market strategy.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, two patterns stand out. Consumer electronics continues to anchor a large share of total volume, fueled by the ongoing refresh cycles of smartphones, wearables, home appliances, and connected accessories, each of which places incremental demands on passive components, RF modules, and power management. Simultaneously, enterprise demand is being reshaped by automation, data infrastructure, and the electrification of mobility and industrial equipment. Automotive and industrial applications are increasingly value-dense, with requirements that span high-reliability microcontrollers, power devices, secure connectivity, and long lifecycle support. Medical electronics is another segment where precision analog, sensing, and power management converge to support diagnostic, monitoring, and treatment devices. The practical takeaway is that demand is not only growing, it is becoming more application-specific, more certification-intensive, and more loyal to qualified suppliers, which raises the value of domain expertise.
Supply-Chain Architecture and Cost Structures
Capital intensity, lead-time discipline, and component availability are interacting to redefine cost structures. In memory-related ecosystems, production capacity has lagged rapidly growing demand, an imbalance visible in export flows from major manufacturing centers and a symptom of how quickly demand can outpace supply in certain technology nodes. In the automotive and industrial arenas, extended lead times for specific microcontroller series illustrate that even mature categories can experience bottlenecks when qualified capacity and demand are misaligned. At the same time, new partnerships in power discrete manufacturing, the opening of additional fabrication and assembly sites, and the expansion of distribution catalogs are all aimed at smoothing availability. The net effect is a market where cost is increasingly a function of reliability, qualification status, and supply assurance, not just unit price. Companies that manage inventory intelligently, qualify alternate sources prudently, and maintain visibility into production pipelines will be better positioned to absorb volatility and protect margins.
Competitive Landscape and Leading Strategies
Incumbents Anchored in Technology Gravity
The competitive field is anchored by firms with deep portfolios and established design-ins across analog, power, microcontrollers, precise sensing, and discrete devices. Several large players have built their advantage around a combination of technical breadth, application familiarity, and long-term customer relationships in automotive, industrial, and medical markets. Analog-focused companies emphasize precision and signal integrity for demanding environments. Power-semiconductor leaders are extending their relevance through wide-bandgap platforms and secure, intelligent solutions for edge and mobility applications. Microcontroller specialists serve automotive and industrial customers with architectures optimized for reliability and integration. Passive component manufacturers and connector specialists, meanwhile, compete on miniaturization, electrical performance, and the ability to scale volume with consistent quality. These positions are not easily replicated because they depend on sustained R&D investment, qualification history, and the trust that arises when components are embedded in safety-critical or high-value systems.
Strategic Moves That Are Reshaping the Landscape
Recent activity shows a market in motion. A power MOSFET manufacturing partnership was formed to strengthen supply stability, illustrating how discrete and power markets are addressing availability through collaboration and expanded fabrication reach. New manufacturing capacity has come online, including a power module plant in Southeast Asia, underscoring the multi-region footprint that major producers are building to serve global demand more flexibly. On the distribution side, catalog expansion and targeted campaigns are improving access to new parts and highlighting application areas such as industrial automation. Participation in major industry events has been used to advance hardware security and edge-compute solutions, signaling that safeguarding and intelligent processing are extensions of core component strategy. Taken together, these moves reflect a landscape where incumbents are reinforcing technology leadership and supply assurance, while distributors and specialists differentiate through breadth, speed, and application focus.
Integration, Differentiation, and the Rise of Niche Strengths
The market is not consolidating into a single mold. Instead, it is bifurcating in a productive way. Some segments reward scale, integrated portfolios, and the ability to support long-lifecycle applications with stable supply. Others reward specialization, speed to market, and the ability to source or rapidly introduce parts that are difficult to obtain. Independent distribution continues to play a meaningful role by connecting customers with new products and hard-to-find inventory, and by offering supply-chain services that go beyond transaction processing. This dual structure means that competitive advantage is context-specific: a manufacturer competing for automotive-grade design wins will pursue a different playbook than a distributor competing for rapid availability and broad catalog depth. The most resilient organizations are those that understand where they sit in this spectrum and invest accordingly.
Looking Ahead: Three Trends to Watch Through 2032
1. Power and Wide-Bandgap Economics Will Keep Improving, but Qualification Will Be the Gatekeeper
As efficiency requirements intensify across automotive, industrial, and energy applications, the addressable market for advanced power semiconductors and supporting components will expand. Yet growth will be uneven because adoption depends on qualification, system integration, and total-cost-of-ownership evidence. Organizations that can shorten qualification cycles, provide application support, and demonstrate reliability across lifecycle conditions will capture more design wins. The risk is that expectations for rapid adoption outrun the practical pace of validation, particularly in automotive and medical applications where certification timelines are long and unforgiving. Strategy should therefore pair technology roadmaps with customer-facing qualification and support capabilities.
2. Sustainability Metrics Will Be Priced Into Procurement and Product Design
With carbon-related mechanisms becoming operational and certificate pricing now visible, environmental performance is transitioning from a compliance topic to a procurement variable. Expect more purchasing decisions to incorporate supply-chain transparency, material sourcing, and energy intensity as evaluation criteria. This trend creates opportunity for manufacturers and distributors that can document and improve their footprints, and it raises the cost of opacity. The uncertainty lies in how quickly and uniformly these criteria will be applied across regions and customers. Firms that treat sustainability as a measurable, certifiable attribute rather than a narrative will have an advantage in negotiations and market access.
Electronics Market
3. Supply Assurance Will Become a Differentiated Value, Not Just a Cost Center
The combination of lead-time variability in select categories, capacity investments across multiple regions, and the strategic use of partnerships points toward supply assurance as a core competitive element. Buyers will increasingly value partners that can provide visibility, inventory flexibility, and qualification-ready alternatives. Manufacturers and distributors that invest in pipeline visibility, multi-site production options, and responsive catalog management will be able to command loyalty in segments where availability is a deciding factor. The downside risk is geopolitical and operational: the continued importance of advanced semiconductor manufacturing hubs means that regional disruptions can have disproportionate effects. Resilience planning, rather than assumption of continuity, will be a necessary discipline.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
Align product roadmaps with the applications and technologies where value density is rising, especially power management, precision analog, sensing, secure connectivity, and reliable microcontrollers for automotive and industrial use. Prioritize qualification and lifecycle support as core capabilities, because design-in decisions in high-stakes applications are often driven by risk reduction as much as by performance. Use regional capacity and partnership options to improve supply assurance without overcommitting to a single geography. Treat sustainability data as a product attribute that can support customer requirements and mitigate future trade friction. Finally, resist the temptation to chase every volume opportunity; concentrate resources where differentiation, certification, and application expertise create durable returns.
PW Consulting
For Investors and Strategic Planners
Assess exposure to sub-segments with the most favorable growth and margin dynamics rather than relying on aggregate market size alone. Favor business models that combine technology leadership with supply assurance, because these two attributes together tend to protect share and pricing. Watch for consolidation among players seeking to broaden portfolios and shorten customer time-to-integration, and monitor the role of independent distribution as a source of market intelligence and rapid introduction capability. Be mindful of policy risk and raw-material dynamics, and model scenarios that reflect extended lead times in certain categories and the possibility of pricing volatility in commodity-like segments. The most resilient investments are those that account for both upside from electrification and connectivity and the operational complexity that accompanies them.
Worldwide Rail Components Market
For Procurement, Supply-Chain, and Sourcing Leaders
Build sourcing strategies that incorporate qualification readiness, lead-time transparency, and alternate-source planning, especially for automotive-grade and industrial parts where delivery windows can be extended. Treat distributor relationships as strategic channels for new product access and hard-to-source inventory, not merely as transactional routes. Incorporate environmental and supply-chain transparency criteria into supplier evaluations, since these are increasingly part of purchasing decisions. Maintain a disciplined approach to inventory and pipeline visibility, balancing the cost of holding buffer stock against the cost of interrupted production. Where feasible, negotiate for improved visibility, regional delivery options, and design-in support, because these capabilities can reduce risk more effectively than price concessions alone.
Closing Perspective
The electronic components market is large, growing, and structurally complex. The aggregate trajectory points toward sustained expansion, but the real opportunities are distributed unevenly across technologies, applications, and geographies. Companies that map their activities to the segments where demand is intensifying, qualification matters, and supply assurance is valued will be best positioned to convert growth into durable advantage. For leaders seeking to move from broad trends to specific, actionable insight, the full research report provides detailed segment-level data and tailored recommendations to support portfolio, investment, and sourcing decisions with greater precision.
For detailed analysis of this topic, please visit the official page: Electronic Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


