



Grinding Wheels Market 2026: The 4.1% CAGR Puzzle Behind 8.77B Trends

Grinding Wheels Market: Strategic Trends and Commercial Opportunities (2026–2032)
1. Market Landscape and Core Challenges
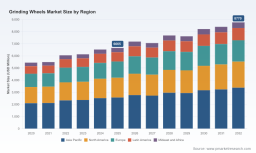
The global grinding wheels market has demonstrated steady expansion over the past five years, moving from a valuation of approximately USD 5,450 million in 2020 to an estimated USD 6,665 million in 2025. Looking ahead, the market is projected to reach USD 8,770 million by 2032, representing a compound annual growth rate of 4.1 percent across the 2026–2032 forecast period. This trajectory reflects a mature but resilient market that is increasingly shaped by shifting industrial priorities rather than raw volume growth alone.
While the top-line figures suggest continuity, the underlying structure tells a more nuanced story. Market concentration remains moderate, with the top three players accounting for roughly 28.5 percent of industry revenue and the top five reaching 35.2 percent. This fragmentation indicates that value is not solely captured by scale; differentiation in product performance, regional service capabilities, and application-specific engineering are becoming decisive competitive factors. The market is large enough to accommodate specialized players, yet consolidating around firms that can integrate abrasives knowledge with machine-tool compatibility and end-user process expertise.
Key Structural Challenges
Several intersecting pressures are redefining how grinding wheels businesses compete and plan for the near term.
- Performance-pressure vs. cost trade-offs. End users are increasingly unwilling to accept incremental wear rates or inconsistent surface finishes in exchange for lower unit prices. Grinding wheels are now evaluated as part of total cost-per-part equations, where dressing frequency, wheel life, and machine downtime carry as much weight as purchase price. This shifts competitive advantage toward suppliers who can demonstrate measurable productivity gains rather than competing purely on commodity pricing.
- Regulatory complexity and standardization. Revised safety and marking frameworks are raising the compliance bar for both wheels and the machines they run on. Updated standards have clarified arbor hole dimensions and anti-overspeed requirements, while newer machine classification schemes require risk-based safety measures, including burst guard strength calculations. At the same time, labeling obligations now extend to maximum operating speed, shelf life or expiry date, dimensions, usage restrictions, traceable manufacturing numbers, mounting instructions, and ISO-type markings. These requirements elevate quality assurance and documentation costs, particularly for cross-border trade and multi-market portfolios.
- Raw material and input volatility. The abrasive grain base remains heavily weighted toward aluminum oxide, which continues to command a substantial share of the broader abrasive grains market. Any disruption to grain supply, binder systems, or additive availability can ripple through wheel pricing and formulation stability. Suppliers that lack diversified sourcing or formulation flexibility face margin exposure when input costs move unexpectedly.
The practical implication is that the grinding wheels market is entering a phase where operational and regulatory excellence are as commercially significant as product performance. Companies that treat compliance, consistency, and process integration as strategic capabilities are better positioned to protect margins and secure long-term contracts.
2. Key Drivers Shaping the Market
Market momentum is being directed by a combination of technological, regulatory, demand-side, and supply-chain forces. Rather than operating in isolation, these drivers are reinforcing one another and reshaping what buyers expect from grinding wheel suppliers.
Technology Innovation and Breakthroughs
Precision-shaped grain technology and advanced bonding approaches are changing the performance envelope of conventional grinding wheels. Products built on controlled grain geometry can deliver more consistent cutting action and predictable wear behavior, which matters increasingly in high-value metalworking, automotive, and aerospace applications. At the same time, developments in diamond and CBN abrasives are extending the role of superabrasive solutions beyond niche operations into more mainstream grinding processes, especially where component tolerances, surface integrity, and throughput are critical.
Recent industry activity underscores this direction. During 2026 trade events, multiple participants showcased grinding-related technologies that blur the line between wheel design and machine-process compatibility. Diamond and CBN abrasives applicable to grinding wheels were highlighted as part of broader precision grinding solutions, while large-format double disc grinding wheels for face and fine grinding demonstrated continued investment in high-productivity processes. Grinding machine providers also presented equipment compatible with electroplated and dressable CBN grinding wheels, reflecting a growing emphasis on process-integrated performance rather than standalone consumable supply. In parallel, resin-bonded grinding wheel offerings continued to appear at hardware-focused exhibitions, signaling sustained interest in flexible bonding solutions for a wide range of workshop and industrial applications.
Policy and Regulatory Environment
Regulations are increasingly shaping both product design and commercial readiness. Updated standards for grinding wheels and accessories have tightened requirements around dimensional consistency and speed safety, making specification accuracy and manufacturing control more important. Machine-related classifications that assign risk levels and mandate appropriate safety measures, including burst guard strength calculations, are also influencing how wheels are selected, validated, and deployed in industrial settings.
For suppliers, these developments raise the value of robust documentation, traceable production, and consistent marking practices. For buyers, they create a stronger expectation that wheel suppliers can support compliance as part of the product proposition. The broader effect is a market where higher safety and quality standards are becoming a competitive filter rather than a back-office obligation.
Demand-Side Shifts in Transport and Steel Industries
Demand for grinding wheels remains closely tied to industrial sectors where precision metal removal, surface conditioning, and tooling support are essential. The transport industry and steel industry continue to represent significant application anchors, reflecting the ongoing need for grinding solutions across component manufacturing, maintenance, and fabrication workflows. Beyond these sectors, the wider application base remains substantial, underscoring the market's diversification across general industrial metalworking, toolmaking, and precision grinding tasks.
What is changing is not simply the volume of activity, but the performance criteria attached to it. Transport and steel-related production environments are placing greater emphasis on consistency, reduced rework, and process reliability. As a result, buyers are more inclined to evaluate grinding wheels based on how effectively they support downstream quality and machine utilization. This demand-side evolution favors suppliers that can align product recommendations with specific process conditions, machine types, and finishing objectives.
PW Consulting
Supply Chain and Cost Structure Dynamics
Cost structures across the grinding wheels value chain are being influenced by input availability, formulation complexity, and the cost of maintaining consistent quality at scale. Since a large share of abrasive grain demand is tied to aluminum oxide, grain pricing and supply reliability can have an outsized impact on margin planning. Binder systems, additives, and manufacturing precision add further layers of variability, particularly for products that must meet application-specific performance targets.
At the same time, logistics and regional demand patterns are reshaping how suppliers think about inventory positioning and production footprints. Markets with strong industrial activity are placing a premium on responsiveness, technical support, and local specification expertise. Suppliers that can balance formulation consistency with regional service capability are gaining an advantage in segments where downtime and specification errors carry significant operational costs.
3. Competitive Landscape and Leading Strategies
The competitive field in grinding wheels is broad and varied, combining large multinational abrasive businesses with focused regional producers and specialized technology providers. The market's moderate concentration suggests room for differentiation, but also intensifying competition for customers who increasingly prioritize performance reliability, application fit, and compliance support.
Worldwide Floor Grinding Tools Market
Strategic Positioning of Core Players
Several established companies illustrate the different ways value is being pursued in this market.
- Saint-Gobain Abrasives leverages its Norton Abrasives brand to serve industrial metalworking, automotive, and aerospace applications with vitrified, resin-bonded, and CBN grinding wheels. Its positioning reflects a focus on broad application coverage and a portfolio that spans conventional and superabrasive solutions.
- Norton Abrasives continues to emphasize its established manufacturing footprint in conventional aluminum oxide, silicon carbide, and superabrasive grinding wheels. Its relevance lies in the combination of product familiarity and the ability to address a wide range of standard and demanding grinding tasks.
- 3M Abrasives differentiates through precision-shaped grain technology in products such as its Cubitron II and silver series depressed-center and cut-off grinding wheels. The emphasis on controlled grain geometry highlights a strategy centered on performance consistency and process efficiency rather than commodity substitution.
- Tyrolit Group specializes in metal and precision grinding wheels, including vitrified and superabrasive products for automotive, aerospace, and toolmaking. Its profile suggests a strategy rooted in application-specific engineering and precision grinding expertise.
- Klingspor produces abrasive discs, cut-off wheels, and bonded grinding wheels, reflecting a practical, broad-based offering for workshop and industrial users. Its strength lies in versatility and coverage across common abrasive product categories.
- Camel Grinding Wheels manufactures resin-bonded and vitrified grinding wheels, cut-off wheels, and coated abrasives, positioning itself across a mix of bonded and coated solutions that serve both general and specialized applications.
- Carborundum Universal Limited operates as a leading abrasives producer for industrial applications in India and globally. Its relevance in the broader market highlights the importance of regional strength, cost-competitive production, and expanding international reach.
Taken together, these profiles show two ongoing patterns. One is the continued importance of portfolio breadth and application coverage among larger players. The other is the growing relevance of technology-led differentiation, especially where grain design, superabrasive compatibility, and process-specific recommendations can justify preferential selection.
Market Evolution and Strategic Trends
The competitive landscape appears to be moving along several recognizable paths.
- Technology-led segmentation. Suppliers are increasingly competing on process-enabling features such as grain geometry, wheel dressing compatibility, and performance stability under specific operating conditions. This creates subtle but commercially meaningful differentiation even within broadly similar product categories.
- Application and sector alignment. Companies with clearer alignment to high-value end markets, including automotive, aerospace, and precision toolmaking, are better placed to command attention from buyers who value consistency and technical support over lowest-cost supply.
- Regional presence and responsiveness. Strong local service, specification assistance, and supply reliability remain critical, especially in active industrial regions where downtime and process mismatches are expensive. This continues to support the relevance of regional leaders alongside global portfolios.
- Integration with grinding process ecosystems. The growing visibility of machine-compatible wheel solutions, including electroplated and dressable CBN options and large-format grinding formats, indicates a widening competitive field where wheel suppliers are increasingly evaluated in the context of overall grinding performance.
The market is not necessarily trending toward rapid consolidation into a single dominant model. Instead, it is becoming more layered: global portfolios provide scale and breadth, regional specialists offer responsiveness and local expertise, and technology-focused players compete on measurable process advantages. For buyers and investors alike, the most relevant question is not only who sells grinding wheels, but who can most reliably translate product characteristics into reduced total cost and improved process outcomes.
4. Future Trends to Watch (2026–2032)
Based on current market direction, regulatory development, and product activity, several trends are likely to shape commercial decision-making over the next three to five years.
Trend 1: Performance Differentiation Will Matter More Than Category Growth
With a projected CAGR of 4.1 percent through 2032, market expansion will provide a supportive backdrop, but growth alone will not determine competitive success. The more decisive battleground will be performance differentiation: wheel life consistency, surface finish quality, dressing behavior, and the ability to reduce total cost per part. Suppliers that can validate these outcomes with practical evidence will have stronger positioning in demanding metalworking, transport, and steel-related applications.
The commercial opportunity lies in moving the conversation from specification matching to process improvement. This includes helping buyers select wheels based on machine type, material removal requirements, and quality targets rather than defaulting to habitual choices. The risk is that companies relying on undifferentiated product lines may face margin pressure as buyers compare solutions more rigorously.
Trend 2: Safety, Traceability, and Compliance Will Become Commercial Levers
Updated standards for wheel marking, dimensional requirements, and anti-overspeed provisions, together with machine risk classification and burst guard considerations, are reinforcing the importance of documentation and manufacturing control. Over time, these requirements are likely to become embedded in procurement expectations, particularly in environments where safety, auditability, and supply consistency are heavily scrutinized.
This creates opportunity for suppliers that can package compliance as part of a dependable supply proposition. Traceable manufacturing numbers, clear usage restrictions, shelf life or expiry information, and complete dimensional and speed markings are increasingly part of the credibility equation. The uncertainty lies in how quickly different regions and customer types adopt consistent procurement practices around these requirements, which could create uneven implementation burdens.
Trend 3: Superabrasive and Process-Integrated Solutions Will Expand Their Reach
The continued visibility of diamond and CBN abrasives in grinding-related applications, alongside machine solutions designed for electroplated and dressable CBN wheels, points toward broader adoption of advanced grinding approaches in selected high-value processes. Large-format grinding wheels and precision-focused formats also indicate that specific high-productivity applications will continue to drive specialized demand.
For suppliers, the opportunity is to develop credible offerings where superabrasive or precision formats deliver clear advantages in tolerance, surface integrity, or throughput. For buyers, the strategic value depends on identifying the applications where these solutions justify their cost through measurable process gains. The risk is over-extension: superabrasive solutions are not universally advantageous, and misaligned adoption can erode return on investment if process conditions are not properly matched.
Grinding Media Market
5. Strategic Actions for Decision Makers
The grinding wheels market is evolving in a way that rewards preparation, evidence, and process-oriented thinking. The following actions can help different stakeholder groups respond effectively.
For Manufacturers and Product Leaders
- Prioritize differentiation through measurable performance attributes such as consistent wear behavior, predictable dressing response, and compatibility with precision grinding processes.
- Strengthen documentation and marking practices to align with evolving safety and traceability expectations, reducing friction in regulated or audit-sensitive procurement environments.
- Invest in application-specific support where transport, steel, and precision metalworking demand clearer guidance on wheel selection and process integration.
For Investors and Strategic Planners
- Assess exposure not only to overall market growth, but to segments where performance differentiation, compliance readiness, and region-specific service can sustain pricing power.
- Watch for signals of technology-led competition, including precision grain designs and superabrasive process compatibility, as indicators of where value may shift over the forecast period.
- Consider supply-chain resilience in abrasive grains and binder inputs as a strategic factor, especially in portfolios sensitive to formulation consistency and input cost volatility.
For Procurement and Operations Leaders
- Evaluate grinding wheels within total cost-per-part frameworks, incorporating wheel life, dressing frequency, rework reduction, and machine utilization rather than unit price alone.
- Verify that suppliers can meet updated marking, speed, and traceability expectations, especially where operational safety and compliance documentation are increasingly important.
- Align specifications with actual process conditions and machine compatibility, including where electroplated or dressable CBN solutions may be justified by precision and throughput requirements.
The market's trajectory suggests that the most consequential decisions will come from understanding where grinding wheels create process value, not just where they fit into a consumables budget. Detailed segmentation data, region-specific demand patterns, application-level performance profiles, and company-level competitive positioning can sharpen these decisions considerably. For readers seeking deeper, segment-level data and tailored interpretation for specific business situations, the full market research report provides a more granular view of the categories, regions, and competitive dynamics shaping the grinding wheels market through 2032.
For detailed analysis of this topic, please visit the official page: Grinding Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


