



Heat Exchanger Market: How 5.5% CAGR and Asia Pacific's 6.9B Size Redefine Growth

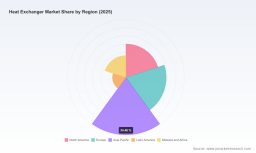
The Heat Exchanger Market: Strategic Shifts and Commercial Opportunities in a Transforming Industrial Landscape
The global heat exchanger market has entered a phase of steady, structurally driven expansion. Between 2020 and 2025, revenue climbed from approximately $14.5 billion to $20.01 billion, reflecting an environment where thermal management has become inseparable from industrial efficiency, energy transition goals, and operational resilience. The forward trajectory points to continued growth through 2032, with a compound annual growth rate of 5.5 percent and projected revenue reaching nearly $29.5 billion by the end of the forecast period. This expansion is not merely cyclical. It is being shaped by overlapping forces: stricter energy and emissions regulations, the electrification of process heat, the cooling demands of digital infrastructure, and a recalibration of supply chains after years of disruption.
For executives and investors, the market presents a familiar paradox. Demand is broad and durable, yet the profitability and competitive positioning of individual players depend heavily on product specialization, regional supply dependencies, and the ability to navigate certification and materials constraints. Understanding where value is created—and where margin pressure is intensifying—requires looking beyond top-line growth and examining the structural dynamics that will separate resilient operators from those exposed to cost volatility and substitution risk.
Market Status and Core Challenges
The current market structure reflects a mature but still evolving industry. Revenue is distributed across multiple product configurations, end-use sectors, and geographic regions, with no single segment dominating to the point of rendering others irrelevant. That dispersion is both a strength and a source of strategic complexity. Manufacturers must balance standardized high-volume offerings with engineered solutions that command higher margins but require deeper customer integration. At the same time, the industry is operating under heightened scrutiny on safety, performance verification, and traceability, which raises the barrier to entry for undifferentiated competitors but also increases compliance burdens for established players.
Heat Transfer Equipment Market
Several challenges stand out as true inflection points.
- Materials cost escalation is reshaping economics. The cost of metallic heat exchanger equipment has risen from less than $100 per kilowatt thermal to a range between $500 and $1,000 per kilowatt thermal. This shift directly affects project economics, particularly for large industrial and power-generation installations where thermal capacity is a primary cost driver. Manufacturers and buyers are now forced to weigh material selection, design optimization, and lifecycle performance more carefully than in the past.
- Regulatory and certification frameworks are tightening the operational baseline. Pressure vessel and heat exchanger fabrication increasingly depends on recognized stamps and certification programs that verify design integrity and performance. Compliance with established mechanical codes and industry certification schemes is no longer optional; it is a precondition for supplying critical industrial, HVAC, and refrigeration applications. These requirements improve safety and interoperability, but they also lengthen qualification cycles and constrain the speed at which new entrants can scale.
- Trade and import dynamics are altering supply reliability. Projections indicate substantial increases in U.S. imports of heat exchange units within specific tariff classifications through 2025. This pattern points to a market that is becoming more internationally interdependent, with sourcing strategies shifting in response to capacity constraints, regional manufacturing investments, and the need to secure consistent supply for downstream projects.
Together, these forces create a market where growth is achievable, but only for participants who can align product strategy with cost discipline, certification readiness, and supply-chain certainty. The days of competing primarily on price are giving way to competition on verified performance, delivery reliability, and application-specific engineering.
Core Drivers of Market Change
Technology Innovation and Product Differentiation
Product innovation is moving along two complementary paths: performance enhancement in established designs and targeted development for emerging cooling and thermal-management needs. In industrial applications, the emphasis remains on improving heat-transfer efficiency, reducing footprint, and extending service life under harsher operating conditions. In parallel, new product introductions are increasingly oriented toward sectors where thermal control is becoming a bottleneck, such as data center cooling and district energy systems.
Recent product activity illustrates this shift. New brazed plate heat exchanger models have been introduced specifically for data center cooling and district energy applications, signaling that manufacturers are tailoring designs to high-density thermal loads and integrated energy networks rather than treating these as generic secondary markets. At the same time, the continued expansion of large-scale plate heat exchanger manufacturing capacity in the United States reflects a strategic bet on domestic production for a product category where throughput, lead time, and proximity to customers can be decisive advantages.
For businesses, the implication is clear: technology leadership is increasingly defined by application fit rather than generic product breadth. Companies that can match thermal performance to specific operating environments—while maintaining manufacturability and serviceability—are better positioned to defend margins and capture premium projects.
Policy and Regulatory Environment
Policy and standards are not background conditions; they are actively shaping demand patterns and competitive eligibility. Mechanical design and fabrication standards for shell and tube units, certification programs for brazed and fusion-bonded plate heat exchangers, and pressure vessel stamping requirements all create a shared technical language across buyers, engineers, and suppliers. That commonality reduces transaction risk in complex projects, but it also means that compliance competence has become a core capability rather than a back-office function.
The regulatory environment also interacts with broader energy and sustainability agendas. As industries face pressure to reduce energy consumption and emissions, thermal recovery and heat integration become more valuable. Heat exchangers that enable waste-heat recovery, efficient process heating, and lower refrigeration loads are increasingly evaluated against energy-performance criteria that extend beyond initial capital cost. In practical terms, this favors suppliers that can document efficiency gains, support lifecycle assessments, and align product specifications with project-level compliance requirements.
Demand-Side Shifts in Key Sectors
Demand is being reshaped by changes in how companies use energy, how facilities are designed, and how critical infrastructure is cooled. Industrial operators are looking for equipment that supports continuous operation with fewer interruptions and lower operating expense. Commercial and infrastructure projects are placing greater emphasis on thermal systems that can scale with load variability and integrate into broader energy strategies. These shifts are not uniform across sectors, but they share a common theme: thermal management is moving from a supporting utility to a strategic performance variable.
PW Consulting
This demand evolution is visible in the localization of manufacturing and the diversification of application-focused product lines. Facility expansions in North America are intended to improve supply reliability for regional customers, while new models designed for data centers and district energy reflect an understanding that future growth will be tied to specific high-value use cases. For buyers, this means that procurement decisions are increasingly influenced by operational continuity, lead-time predictability, and the ability to match equipment to changing load profiles.
Supply Chain and Cost Structure Transformation
The cost structure of heat exchanger production is being re-evaluated in response to materials inflation, fabrication complexity, and the need for dependable delivery. The sharp increase in metallic equipment costs per unit of thermal capacity is a clear signal that design choices and procurement strategies must be recalibrated. Suppliers that rely on rigid material specifications without exploring optimization opportunities may face margin compression, while those that integrate material efficiency, standardized yet customizable platforms, and robust fabrication processes can better absorb input-cost volatility.
At the same time, trade flows and import projections suggest that sourcing strategies are becoming more dynamic. Companies are balancing domestic production with international supply to manage risk, cost, and capacity. This balancing act is especially important in segments where project timelines are tight and certification or quality documentation must be maintained across the supply chain. The organizations that succeed will be those that treat supply chain design as part of product strategy, not as a separate logistics function.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of specialized manufacturers, broad thermal-system providers, and service-oriented firms that support installation, repair, and maintenance. This diversity is one of the market’s defining features. Some companies compete through large-scale shell and tube solutions for industrial and power generation applications. Others focus on plate and frame, brazed plate, or dry cooling systems for HVAC, refrigeration, and process industries. A further group builds its position on custom fabrication, ASME-aligned pressure vessel work, or aftermarket services that extend asset life and reduce downtime.
Graphite Heat Exchanger Market
Several strategic patterns are evident among the more prominent players.
- Application anchoring. Leading manufacturers tend to differentiate by anchoring their offerings in specific end-use environments. Some build their identity around industrial and power applications, others around refrigeration and cooling, and others around engineered systems for refining and process sectors. This focus allows them to develop deeper technical credibility and repeatable project references in their chosen domains.
- Certification and standards as competitive infrastructure. Companies that operate confidently within recognized mechanical and performance standards are better positioned to win bids in regulated or safety-critical environments. Stamping readiness, documented quality systems, and alignment with widely accepted design standards reduce friction in project approval and procurement.
- Capacity and supply localization. Recent facility investments in the United States and Mexico highlight a strategic emphasis on regional production capability. Expanding domestic or nearshore manufacturing can improve delivery speed, reduce exposure to long-distance logistics risk, and strengthen relationships with customers who prioritize supply reliability.
- Aftermarket and service differentiation. Firms that provide repair, maintenance, and heat recovery services create additional value streams while reinforcing customer relationships. In asset-intensive industries, the ability to keep existing equipment operating efficiently can be as strategically important as selling new units.
The market is not consolidating into a single dominant model, and that is deliberate. The diversity of applications, sizes, materials, and certification requirements makes full horizontal consolidation difficult. Instead, the landscape is evolving through a combination of specialization, selective capacity expansion, and targeted product launches. New entrants face a meaningful hurdle because they must establish trust in performance, compliance, and delivery before they can compete for large projects. Meanwhile, established players are expanding where demand is strongest and where manufacturing scale or technical specialization gives them an advantage.
International activity also remains important. Large exhibitions and technology gatherings in Asia continue to draw hundreds of companies showcasing new equipment, materials, and process technologies. This global exchange of innovation matters because it influences product roadmaps, material choices, and competitive benchmarks across regions. Companies that monitor these developments closely can identify emerging design directions and supply-chain shifts before they become mainstream.
Future Trends and Commercial Opportunities
Trend One: Application-Specific Thermal Solutions Will Command Greater Value
Over the next three to five years, the market is likely to reward manufacturers that move from generic product catalogs to solution-oriented portfolios tailored to high-priority applications. Data centers, district energy, industrial heat recovery, and specialized refrigeration systems are all areas where thermal performance has direct operational and economic consequences. Equipment that is designed for these contexts—rather than adapted after the fact—will increasingly be preferred in procurement decisions.
The commercial opportunity lies in combining technical customization with repeatable engineering platforms. If a company can standardize core design elements while varying capacity, materials, and integration features for specific applications, it can achieve both efficiency in production and relevance in the market. The risk is that over-customization can erode the cost advantages of scale, so the balance between flexibility and standardization will be a critical managerial challenge.
Trend Two: Cost and Materials Strategy Will Become a Competitive Weapon
Given the significant increase in metallic equipment costs per unit of thermal capacity, cost management will move up the strategic agenda. Companies that succeed will not simply pass through higher input costs; they will actively redesign for material efficiency, evaluate alternative configurations where appropriate, and work with customers to optimize total cost of ownership rather than initial price. Procurement teams, in turn, will increasingly seek evidence that installed equipment will perform efficiently over time, reducing operating expense and exposure to future materials volatility.
This trend creates opportunities for suppliers that can offer transparent performance data, lifecycle cost modeling, and design choices that align material use with actual thermal requirements. It also raises the stakes for buyers, who must weigh short-term price against long-term reliability and efficiency. Misaligned purchasing decisions could lead to higher operating costs or premature replacement cycles, especially in demanding service environments.
Trend Three: Supply Reliability and Regional Manufacturing Will Shape Market Access
As import patterns shift and major manufacturers invest in North American production capacity, supply reliability is becoming a competitive differentiator. Projects that depend on tight installation schedules or operate in environments where downtime is costly will naturally favor suppliers that can demonstrate consistent delivery and strong regional support. This does not mean international supply will disappear, but it does suggest that regional manufacturing and service presence will be valued more highly than in the past.
The opportunity here is for manufacturers to align capacity investments with the customer segments most sensitive to lead time and service response. For investors, the relevant question is whether capacity expansion is attached to durable demand or merely to short-term pricing conditions. Overbuilding without clear application demand can create pressure on utilization and pricing, while targeted expansion in growing segments can strengthen market position and improve margins over time.
Uncertainty and Risk Considerations
Several uncertainties should temper overly optimistic planning. Materials cost trajectories remain volatile, and any further escalation could pressure project economics and delay capital decisions. Regulatory and certification requirements may become more demanding in certain jurisdictions, increasing qualification time and reducing flexibility in sourcing. Trade dynamics could also shift if tariff structures, import patterns, or domestic content expectations change. Finally, demand growth may be uneven across sectors, with some applications expanding rapidly while others remain constrained by broader industrial activity or capital spending cycles.
These risks do not undermine the market’s long-term direction, but they do reinforce the need for scenario-based planning. Companies that treat demand, cost, and supply assumptions as fixed are more exposed to disruption than those that prepare for a range of outcomes.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to sharpen the link between product strategy and application demand. That means identifying the segments where thermal performance, certification readiness, and delivery reliability matter most, and then concentrating engineering and manufacturing investment there. It also means reviewing material and fabrication choices with a clear eye on cost exposure, exploring where standardization can protect margins without sacrificing application fit. Companies that can offer verified performance, predictable lead times, and strong service support will be better positioned to win and retain high-value projects.
For investors, the key is to distinguish between capacity that is tied to structural demand and expansion that is primarily reactive. Look for evidence that growth is anchored in application-driven need, supported by clear operational advantages, and aligned with compliance and supply reliability. Companies with diversified but focused portfolios, strong certification capabilities, and a credible aftermarket or service presence often have more resilient business models than those relying on undifferentiated volume alone. Monitoring regional manufacturing investments and product launches in emerging applications can also provide early signals about where competitive advantages are being built.
For procurement and operations leaders, the focus should shift from transactional price comparison to total value assessment. That includes evaluating equipment against lifecycle efficiency, serviceability, delivery risk, and compliance documentation. In environments where downtime, energy cost, or regulatory exposure is significant, the cheapest initial option may not be the most economical over the life of the asset. Building procurement criteria that reflect operational reality can reduce vulnerability to supply delays, performance shortfalls, and avoidable operating expenses.
Because the market is evolving across technology, regulation, cost structure, and regional supply simultaneously, the full picture is difficult to capture from headlines or isolated announcements alone. Detailed segmentation data, company-level positioning, and scenario analysis are needed to convert these broad dynamics into concrete decisions about product investment, sourcing, and market entry. For organizations that want to move faster and with more confidence, a comprehensive research perspective can help identify where growth is most durable, where margin pressure is most likely, and which strategic choices will matter most over the next several years.
For detailed analysis of this topic, please visit the official page: Heat Exchanger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


