



MMA Market 2026: The Real Drivers Behind 7.9% CAGR Growth to 2032

Strategic Trends and Commercial Opportunities in the Global Methyl Methacrylate Market
The global methyl methacrylate (MMA) market has entered a period of structural transformation, driven by shifting capacity dynamics, evolving sustainability mandates, and expanding downstream applications. Valued at approximately 162.5 million USD in 2025, the market reflects steady expansion from 113.25 million USD in 2020, with a projected compound annual growth rate of 7.9 percent through 2032. This trajectory signals robust underlying demand, yet the growth path is neither uniform nor frictionless. Industry participants must navigate supply chain reconfigurations, regional price volatility, and intensifying competitive pressures while aligning product portfolios with emerging end-use requirements. Understanding the interplay between technological advancement, regulatory shifts, and demand-side evolution is essential for capturing value in the coming years.
The market concentration remains notably high, with the top three players holding roughly 65 percent of global capacity and the top five accounting for an estimated 85 percent. Such concentration shapes pricing dynamics, influences capacity expansion decisions, and creates both barriers and opportunities for new entrants. While the monomer remains the dominant form consumed across applications, the broader methacrylate ecosystem encompasses a range of derivatives that extend value creation beyond raw monomer supply. Companies that successfully integrate upstream efficiency with downstream formulation expertise are positioned to command stronger margins and deeper customer relationships.
Market Scale and Growth Trajectory
The historical expansion of the MMA market demonstrates consistent growth punctuated by cyclical supply disruptions and regional demand fluctuations. The transition from 2020 through 2025 saw incremental gains as downstream sectors resumed activity following global disruptions, while the forecast period through 2032 points toward accelerated expansion fueled by infrastructure investment, electrified mobility adoption, and electronics miniaturization. Growth is not evenly distributed across regions or applications, but the aggregate trajectory reflects a market that is repricing itself around sustainability premiums, supply reliability, and application-specific performance requirements.
Revenue projections indicate that the market will surpass 180 million USD by 2026 and continue climbing toward 272.5 million USD by 2032. This expansion reflects both volume growth and structural shifts in product mix, as high-performance grades and sustainably produced variants capture a larger share of downstream spending. The pace of growth will depend on how quickly capacity transitions align with demand signals, how regulatory frameworks shape production economics, and how quickly end-use industries adopt next-generation materials.
Key Challenges and Inflection Points
Several structural challenges are redefining the MMA market landscape. First, the transition from traditional C3-based production pathways to alternative feedstock routes introduces both operational complexity and capital intensity. Companies investing in newer production technologies must manage ramp-up risk, supply chain adaptation, and customer qualification timelines, all while maintaining competitive pricing in a market sensitive to raw material spreads.
Second, regional capacity realignment is reshaping supply reliability and pricing architecture. Strategic plant closures, capacity transfers, and geographic shifts in production footprint have altered regional supply balances, creating short-term volatility and forcing downstream buyers to recalibrate sourcing strategies. The interplay between legacy capacity retirement and new facility commissioning has produced uneven supply conditions that reward agile procurement and penalize rigid long-term contracting.
Third, sustainability compliance and carbon footprint differentiation are emerging as decisive commercial factors. End-use industries increasingly demand materials with lower lifecycle emissions, verified recycling integration, and transparent environmental reporting. Producers that cannot demonstrate credible sustainability performance risk losing share to competitors with lower-carbon production pathways or stronger ESG credentials. This dynamic is particularly pronounced in construction, automotive, and electronics, where regulatory pressure and corporate sustainability targets are accelerating material substitution decisions.
Key Drivers Reshaping the Market
Technological Innovation and Production Pathways
Technological advancement remains a primary catalyst for market evolution. Alternative production routes that utilize different feedstock inputs are gaining traction, offering potential advantages in carbon intensity, feedstock flexibility, and integration with circular material flows. One notable development involves the commercialization of a C2-based production pathway that integrates chemical recycling for closed-loop operations, reducing the carbon footprint associated with traditional MMA synthesis. The successful ramp-up of full industrial-scale operation at a major North American facility signals a shift toward lower-emission production models, provided that feedstock availability, operational reliability, and cost competitiveness can be sustained.
Such innovations are not merely technical achievements; they alter competitive positioning by enabling producers to differentiate on sustainability credentials, supply reliability, and long-term cost structure. Companies that can validate performance at scale, secure feedstock partnerships, and communicate environmental benefits to downstream customers are likely to capture premium positioning. Conversely, reliance on legacy production methods without parallel sustainability investments may expose suppliers to margin compression as buyers prioritize lower-carbon alternatives.
Policy and Regulatory Environment
Regulatory frameworks and policy signals are exerting growing influence on capacity planning, feedstock selection, and regional investment decisions. Environmental compliance requirements, emissions reporting mandates, and sustainability-related procurement standards are reshaping the cost calculus for both producers and downstream users. In some cases, regulatory uncertainty has prompted reassessment of large-scale capacity projects, with firms pausing or redirecting investments as they evaluate long-term policy trajectories and market demand alignment.
At the same time, sustainability-driven regulations are creating incentives for process innovation and material efficiency. Producers that proactively align operations with emerging compliance expectations can reduce future retrofit risk and position themselves as preferred suppliers for customers facing their own sustainability mandates. The regulatory landscape is therefore not simply a constraint; it is a filter that rewards operational agility and penalizes complacency.
Demand-Side Evolution and Application Expansion
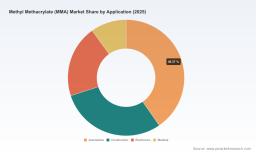
Downstream demand patterns are shifting as end-use industries pursue performance, lightweighting, and durability improvements. The automotive sector continues to drive volume through applications that require transparent, weather-resistant, and impact-tolerant materials, with electric vehicle platforms creating additional demand for specialized acrylic components and interior trim solutions. Construction activity, supported by infrastructure renewal and modernization initiatives, sustains demand for signage, glazing, and durable surface materials that benefit from MMA-derived performance characteristics.
Electronics and medical applications represent additional growth vectors. Electronics manufacturers are increasingly relying on high-purity acrylic materials for components that demand dimensional stability, optical clarity, and thermal resistance. Medical device and healthcare applications are expanding as biocompatible and sterilizable acrylic materials gain acceptance in diagnostic, procedural, and consumer health products. These application segments are not only adding volume; they are also elevating the value of specialized grades, which command stronger margins and require closer technical collaboration between suppliers and end users.
Supply Chain Dynamics and Cost Structure
Supply chain conditions and raw material cost movements are directly influencing pricing stability and margin outcomes. Global MMA prices experienced upward pressure in early 2026, with momentum intensifying toward the end of the quarter as supply tightened and production costs increased. Such price dynamics highlight the sensitivity of the market to feedstock availability, energy costs, and production utilization rates. Companies that manage feedstock sourcing, energy efficiency, and inventory positioning effectively are better equipped to navigate price volatility and protect margins.
PW Consulting
Capacity realignment across key regions has further complicated supply reliability. Strategic decisions to close certain legacy facilities while commissioning newer, more efficient plants have altered regional supply balances, creating temporary dislocations and forcing downstream buyers to adapt sourcing strategies. In parallel, some producers have adjusted product offerings and geographic sales strategies to optimize portfolio performance, reflecting a broader trend toward disciplined capacity management and targeted market participation.
Competitive Landscape and Leading Strategies
The MMA market is characterized by a concentrated set of global producers, each pursuing distinct strategic priorities to defend or expand their market position. Leading players are differentiating through a combination of production technology, geographic footprint, sustainability commitments, and application-specific product development. The competitive environment rewards scale, operational excellence, and the ability to align supply capabilities with evolving downstream requirements.
Strategic Positioning of Major Players
Major producers are pursuing multiple levers to strengthen competitive advantage. One prominent global producer has focused on expanding its methacrylate leadership through large-scale capacity investments and technology differentiation, maintaining a dominant position in global methacrylate production. Another key player has advanced sustainability-oriented production approaches, emphasizing lower-carbon pathways and closed-loop operations to appeal to customers with stringent environmental targets. Integrated producers supplying monomer and derivatives for coatings, adhesives, and polymer applications are leveraging vertical integration and technical service capabilities to deepen customer relationships and stabilize demand.
Regional presence and supply chain resilience are also central to competitive positioning. Producers with North American operations have invested in capacity expansions and facility modernizations to strengthen regional supply reliability, while Asian-focused manufacturers have adjusted pricing and product strategies in response to regional market conditions. Companies with dedicated division structures for MMA and acrylic resins are increasingly emphasizing high-performance grades for electronics, automotive, and optical applications, reflecting a strategic shift toward value-added segments rather than commodity volume competition.
Specialist producers focusing on methacrylate derivatives and sustainable PMMA solutions are carving out niches by combining application expertise with environmental credentials. Their strategy often centers on technical customization, supply consistency, and sustainability reporting that resonates with downstream customers facing procurement mandates. Meanwhile, global distributors and suppliers of methacrylate-based systems for coatings, adhesives, and polyurethane applications are expanding their geographic reach and product portfolios to capture demand across diverse end-use markets.
Poly Methyl Methacrylate (PMMA) Market
Market Evolution and Competitive Dynamics
The competitive landscape is evolving along several axes. Consolidation and capacity optimization are enabling established players to streamline operations, retire less efficient assets, and redirect capital toward higher-return projects. At the same time, the emergence of alternative production technologies and sustainability-focused differentiation is creating space for companies that can operationalize new pathways at scale. New entrants face meaningful barriers due to capital intensity, feedstock logistics, customer qualification requirements, and the prominence of incumbent technical service networks, but targeted entry into specialty grades or regional supply gaps remains plausible for well-positioned organizations.
Pricing power and margin resilience are increasingly tied to sustainability credentials, supply reliability, and application-specific expertise. Producers that can demonstrate consistent performance, lower lifecycle emissions, and responsive technical support are better positioned to negotiate favorable commercial terms and retain customers during supply disruptions. The market is therefore moving toward a more value-driven competition model, where volume alone is insufficient to secure long-term advantage.
Future Outlook and Emerging Opportunities
Trend 1: Sustainability as a Structural Differentiator
Lower-carbon production and circular material integration are set to become central competitive dimensions over the next three to five years. Producers that successfully scale alternative feedstock routes, chemical recycling integration, and verified emissions reductions will gain preferential access to customers with sustainability procurement mandates. This trend creates opportunities for suppliers to command premiums for certified low-carbon grades, secure long-term commitments from environmentally focused end users, and differentiate from competitors reliant on higher-emission pathways. The risk lies in greenwashing exposure and the need for credible verification, as downstream buyers increasingly scrutinize sustainability claims and demand transparent reporting.
Trend 2: Regional Supply Rebalancing and Sourcing Strategy Shifts
The ongoing realignment of production capacity across regions will continue to influence pricing, availability, and contract structures. As legacy facilities are retired and newer plants reach full operational scale, regional supply balances will evolve, creating both disruption and opportunity. Buyers that diversify sourcing, develop contingency supply arrangements, and align contract terms with capacity transition timelines will be better insulated from volatility. Producers that can offer reliable regional supply, flexible delivery models, and transparent capacity reporting will strengthen their negotiating position and customer retention.
Trend 3: Application Specialization and High-Performance Grade Expansion
Demand for specialized acrylic materials in automotive, electronics, medical, and advanced construction applications is expected to grow as performance requirements become more stringent. This trend favors producers with strong formulation capabilities, technical service infrastructure, and the ability to co-develop solutions with end users. Opportunities exist for suppliers to capture higher margins through grade customization, application-specific certification, and integrated product systems that address multiple performance criteria. The risk is that overinvestment in unproven application segments or inadequate technical support could limit returns, particularly if downstream adoption timelines extend or substitution alternatives emerge.
Methacrylic Acid (MAA) (CAS 79-41-4) Market
Actionable Insights for Decision Makers
The evolving MMA market environment requires proactive strategy adjustments across the value chain. Decision makers should align sourcing, investment, and product development plans with the structural trends shaping supply, pricing, and sustainability expectations.
- For manufacturers and producers, priority should be placed on operationalizing lower-carbon production pathways, securing feedstock and energy cost advantages, and building technical service capabilities that support application-specific sales. Investing in scale where it delivers cost and sustainability benefits, while maintaining disciplined capacity management, can strengthen margin resilience and customer retention.
- For investors, attention should focus on companies with credible sustainability roadmaps, visible capacity transition plans, and exposure to higher-growth application segments such as automotive electrification, electronics miniaturization, and medical devices. Assessing feedstock flexibility, regional supply positioning, and ESG verification readiness can help identify businesses positioned for durable value creation.
- For procurement and sourcing leaders, diversifying supplier bases, developing scenario-based contracting, and incorporating sustainability criteria into supplier selection can reduce exposure to regional disruptions and price volatility. Establishing clear performance and compliance requirements, while maintaining flexibility for capacity transition periods, will support supply continuity and cost control.
Detailed segmentation data, capacity flow analysis, pricing trajectory modeling, and company-level assessments can provide the precision needed to convert these strategic directions into execution plans. Organizations seeking to deepen their market intelligence and align decisions with granular demand, supply, and competitive signals will benefit from comprehensive research that maps the full landscape and isolates actionable opportunities.
For detailed analysis of this topic, please visit the official page: Methyl Methacrylate (MMA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


