



Automotive Drive Shaft Market 2026: Beyond The 5.2% CAGR—Strategic Shifts Reshaping Growth

Strategic Trends and Commercial Opportunities in the Automotive Drive Shaft Market
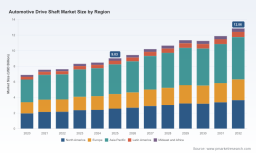
The automotive drivetrain is undergoing one of its most significant structural transformations in decades. As propulsion architectures diversify and vehicle platforms evolve, the drive shaft has shifted from a standardized mechanical component to a strategically differentiated element of vehicle performance, efficiency, and packaging. Market tracking indicates that the global automotive drive shaft sector has grown from approximately $6.9 billion in 2020 to an estimated $9.03 billion in 2025, with a projected compound annual growth rate of 5.2 percent across the 2026–2032 horizon. The trajectory points toward a market surpassing $12.8 billion by the end of the forecast period, reflecting both volume expansion and a steady shift toward higher-performance, lightweight, and application-specific designs.
Beneath the headline growth figures lies a more nuanced reality. The sector is no longer driven solely by total vehicle production; it is increasingly shaped by propulsion mix, regional platform strategies, material substitution, and the consolidation of driveline technology portfolios. For executives, investors, and procurement leaders, the question is no longer whether the market is expanding, but where value is being created, which capabilities are becoming non-negotiable, and how prevailing cost and regulatory pressures will reshape competitive dynamics over the next five years.
Market Landscape and Core Challenges
The current market structure reflects a maturing but directionally shifting ecosystem. Growth over the historical period was supported by steady passenger vehicle demand, incremental content gains in vehicle platforms, and early-stage electrification programs that required rethinking torque delivery and packaging constraints. The commercial vehicle segment continues to provide meaningful volume stability, while the passenger car segment anchors the majority of revenue. Within product categories, hollow shaft designs dominate the revenue split, driven by their weight advantages, torsional efficiency, and broader adoption in modern front-wheel and all-wheel-drive architectures. Solid shafts retain a strong presence where durability, load capacity, and cost predictability remain paramount, particularly in heavier commercial applications and certain rear-drive configurations.
Worldwide Intermediate Shaft for Vehicle Market
Against this backdrop, three core challenges are reshaping how suppliers, OEMs, and investors should read the market.
- Propulsion-mode fragmentation. The transition from conventional internal combustion architectures to hybrid and electric platforms is not a 1:1 replacement of existing driveline content. Electric and hybrid vehicles alter torque characteristics, packaging envelopes, and NVH requirements, forcing suppliers to redesign joint interfaces, support structures, and shaft geometries. This creates short-term engineering complexity and lengthens validation cycles, even as it opens longer-term opportunities for propulsion-agnostic driveline systems.
- Material cost volatility and sourcing pressure. Steel continues to serve as the foundational material for many drive shaft applications because of its balance of strength, toughness, and supply chain maturity. At the same time, aluminum and composite solutions are gaining ground where weight reduction and efficiency targets are most stringent. The practical challenge is that raw material price swings for steel, aluminum, and composites can push component costs upward by as much as 15 percent in a single year, complicating quotation stability, margin planning, and long-term program commitments.
- Competitive concentration with room for differentiation. The market remains relatively fragmented at the top, with the leading three players accounting for roughly 24.6 percent of revenue and the top five reaching about 26.2 percent. That level of concentration signals a sector where scale, customer relationships, and engineering breadth matter, but also where differentiation is still possible through application-specific engineering, regional manufacturing footprints, and value-added design services. In practical terms, market share alone does not guarantee resilience unless it is paired with program wins in higher-growth configurations and cost-competitive execution.
Key Demand Drivers
Technology Innovation and Design Breakpoints
The most consequential driver of near-term market change is the engineering redefinition of what a drive shaft must accomplish. Lightweight aluminum and carbon fiber composites are increasingly specified by EV manufacturers as standard options to meet efficiency and emissions requirements, signaling a structural shift in component specifications rather than a temporary trend. This push toward weight reduction intersects with higher torque density in electrified powertrains, which places new demands on joint durability, balance, and vibration damping. Suppliers that can deliver hollow shaft designs with tighter tolerances, optimized wall profiles, and advanced joint integration are better positioned to capture content in vehicles where every kilogram and every decibel of NVH performance matters.
Technically, the opportunity is not limited to material substitution. The growth of high-angle CV joints, telescopic solutions, and integrated driveline architectures reflects a broader demand for packaging flexibility in crossovers, EVs, and premium passenger vehicles. Product launches in this space are increasingly framed around supporting multiple propulsion types within a single platform strategy, which suggests that future winning components will be judged as much on adaptability as on baseline performance.
Policy and Regulatory Environment
Regulatory expectations continue to influence design choices indirectly but powerfully. Efficiency mandates, emissions targets, and durability standards create incentives for weight reduction, friction reduction, and longer service life. In electric vehicle programs, these requirements can translate into more aggressive use of aluminum and composites, as well as tighter specifications for rotating components. The regulatory environment also affects commercial vehicle demand, where emissions and payload considerations shape axle and driveline selection. While policy does not prescribe a single drivetrain architecture, it consistently raises the cost of inefficiency, which benefits suppliers capable of delivering lighter, more integrated, and more reliable driveline solutions.
Demand-Side Shifts in Consumer and OEM Behavior
On the demand side, the expansion of SUVs, crossovers, and premium passenger vehicles has increased the relevance of driveline systems that can accommodate varied packaging constraints and higher performance expectations. Passenger cars continue to represent the dominant revenue base, but the composition of that demand is changing. OEMs are prioritizing platforms that can be reused across propulsion types, which favors suppliers with modular, propulsion-agnostic capabilities. At the same time, commercial vehicle demand remains a critical anchor for solid shaft and heavy-duty applications, particularly where strength, load capacity, and total cost of ownership outweigh the emphasis on minimal weight.
The commercial-vehicle side also introduces a different purchasing logic. Fleet operators and commercial OEMs focus heavily on lifecycle cost, serviceability, and reliability under sustained load. That creates a dual-track market: one track oriented toward efficiency and lightweight integration in passenger vehicles, another oriented toward robustness and cost predictability in commercial applications. Suppliers that can manage both tracks without diluting engineering focus tend to be more resilient across cycles.
Supply Chain and Cost Structure Dynamics
Cost structure is becoming a strategic battleground. Established steel supply chains provide reliability and scale, but they are exposed to price volatility and regional availability constraints. Aluminum and composites can improve performance and packaging, yet they introduce additional complexity in sourcing, processing, and validation. The practical consequence is that cost competitiveness is increasingly determined not just by material choice, but by supplier integration, manufacturing efficiency, and the ability to manage mix shifts without sacrificing delivery reliability. Programs that require rapid transitions between material grades or joint configurations amplify the importance of flexible production and strong supplier relationships.
This environment favors suppliers that can combine engineering support with disciplined cost execution. In practice, the winners are those who can help OEMs navigate the trade-offs between weight, strength, NVH, and cost while keeping programs on schedule. That is especially true as recent industry developments show major players investing in driveline technologies that span EVs and conventional platforms, indicating that breadth of capability is becoming a commercial advantage.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a set of established driveline specialists, each with a distinct strategic posture. GKN Automotive remains focused on sideshafts, CV joints, and propeller shafts across ICE, hybrid, and electric vehicles, emphasizing propulsion-agnostic drive systems. That positioning reflects an effort to stay relevant across propulsion transitions rather than betting on a single powertrain future. Nexteer Automotive has built a reputation around premium telescopic drive shafts and high-angle CV joints for OEM applications, with a recent emphasis on driveline technologies designed to support both EVs and premium driving experiences across propulsion types. In the first quarter context, Dana Incorporated reported strong results alongside new business wins in drivetrain solutions, illustrating how program-level victories can reinforce commercial momentum even as broader market conditions remain mixed.
The competitive picture also includes major driveline and metal-forming players such as American Axle & Manufacturing, which supplies front and rear axles and driveshafts for global OEMs, and Hyundai WIA Corporation, which produces driveline systems and drive shafts for both passenger and commercial applications. Neapco Holdings rounds out the landscape with driveline components including driveshafts and CV joints for OEM and aftermarket use. Together, these companies highlight a market where scale, geographic reach, and application coverage matter, but differentiation increasingly depends on engineering integration and program execution.
Recent corporate and product activity underscores how the landscape is evolving. The announcement of a combination involving Dauch Corporation and Dowlais Group, integrating GKN Automotive driveline technologies, signals a consolidation path aimed at broadening technical portfolios and strengthening competitive scale. At the same time, product-level moves such as Nexteer’s introduction of three driveline technologies for EVs and premium applications show that innovation remains a central competitive lever. The pattern suggests a market that is neither fully consolidated nor static; rather, it is being shaped by selective integration, technology broadening, and continued investment in next-generation driveline architectures.
Strategic differentiation is emerging along several axes. One is propulsion-agnostic engineering: the ability to support multiple powertrain types with shared platform logic reduces OEM complexity and increases the value of suppliers that can deliver flexible component families. Another is material and design leadership, especially where lightweight solutions can be adopted without compromising durability or cost targets. A third is regional manufacturing and customer proximity, which supports faster response times, lower logistics exposure, and better alignment with local content expectations. In this environment, scale alone is inadequate; competitive advantage is increasingly tied to technical breadth, portfolio coherence, and the capacity to convert innovation into repeatable program wins.
Forward-Looking Trends and Commercial Opportunities
Trend 1: Propulsion-Agnostic Driveline Architectures Will Become a Standard Expectation
Over the next three to five years, OEMs are likely to continue prioritizing platforms that can accommodate multiple propulsion modes. That dynamic favors drive shaft and driveline solutions that can be adapted across ICE, hybrid, and electric applications without sacrificing performance or packaging efficiency. The commercial opportunity lies in offering modular component families, joint configurations, and integration support that reduce redesign effort and accelerate time-to-production. Suppliers that can demonstrate flexibility without compromising quality or cost structure will be better positioned to secure multi-program relationships.
The associated risk is execution complexity. Supporting diverse propulsion modes increases engineering workload, validation requirements, and inventory complexity. Companies that overextend across too many configurations without disciplined platform logic may face margin erosion and operational strain.
Trend 2: Lightweight Materials Will Expand, but Steel Will Remain Foundational
Industry direction points toward broader adoption of aluminum and composite solutions in applications where efficiency targets and packaging constraints are most demanding. At the same time, steel’s strength, toughness, and established supply chain will keep it central to many drive shaft applications, particularly where cost, durability, and volume manufacturing reliability matter most. The commercial opportunity here is not a simple swap from one material to another; it is the ability to offer the right material choice for each application while managing volatility in raw material costs. Suppliers with strong sourcing strategies, material expertise, and cost-forecasting discipline can convert material transitions into differentiated value rather than margin risk.
A key uncertainty is the pace and consistency of material adoption. If lightweight material specifications become more standardized across EV platforms, adoption could accelerate quickly and reward early movers with strong process capability. If volatility in raw material pricing persists, OEMs may adopt a more cautious stance, prioritizing total cost of ownership over absolute weight reduction in certain segments.
Trend 3: Consolidation and Portfolio Broadening Will Reshape Competitive Access
The market is likely to continue experiencing selective consolidation and portfolio integration as companies seek broader driveline capabilities, greater scale, and stronger positions across propulsion types. This creates two related opportunities. For larger players, integration can expand technical coverage and improve competitive positioning in high-value programs. For smaller or more specialized suppliers, the opportunity lies in focusing on niches where application knowledge, speed, or regional proximity creates defensible value. Investors and executives should watch for combinations that deepen technology portfolios, as well as for supplier strategies that emphasize end-to-end driveline integration rather than single-component competition.
The risk is that consolidation can also raise customer concentration concerns and reduce flexibility in some procurement relationships. Buyers may need to balance the benefits of integrated supply against the desire for multi-source resilience, especially in programs where supply continuity is critical.
PW Consulting
Actionable Guidance for Decision-Makers
For Manufacturers and Suppliers
Focus engineering investment on propulsion-agnostic designs and lightweight material capabilities, but pair that investment with disciplined cost management. The market is rewarding suppliers that can support multiple propulsion types while maintaining stable quotations and reliable delivery. Strengthen program-management and validation capacity so that new product introductions do not become bottlenecks. Where possible, build modular component strategies that reduce redesign risk and enable faster response to OEM platform decisions.
For Investors
Evaluate exposure not just by market size, but by technology breadth, application mix, and sensitivity to material cost volatility. Companies with strong positions in high-growth configurations, diversified propulsion coverage, and credible integration strategies are better placed to capture the next phase of growth. Monitor corporate consolidation activity closely, since combinations that broaden driveline portfolios may change competitive intensity and margin dynamics. Be mindful that revenue growth can mask uneven profitability if material volatility or program mix shifts are not managed effectively.
For Procurement and OEM Sourcing Leaders
Treat supplier selection as a multi-factor decision that includes technical flexibility, material strategy, and regional execution capability, not only unit price. Given raw material volatility, consider sourcing frameworks that provide visibility into cost drivers and allow for structured adjustments without destabilizing program economics. Where lightweight materials are specified for efficiency or emissions reasons, ensure that suppliers have validated processes and sufficient capacity to support scale-up. Diversifying across propulsion-capable suppliers can reduce program risk, especially when platform strategies span multiple powertrain types.
Closing Perspective
The automotive drive shaft market is moving from a period of steady volume-driven growth into a phase where technology choice, propulsion mix, material economics, and supplier integration matter as much as overall demand. The sector’s expansion toward the $12.8 billion range by 2032 is meaningful, but the more important story is how value is being redistributed across product types, applications, and competitive positions. Companies that can align engineering flexibility with cost discipline, while navigating material volatility and shifting propulsion requirements, are the ones most likely to convert market growth into durable advantage.
For decision-makers seeking a sharper read on regional dynamics, application-level demand patterns, material segment shifts, and company-specific positioning, a more detailed research asset can provide the granularity needed to translate these trends into procurement, investment, and product strategy. A full market report offers deeper segmentation detail, competitive benchmarking, and scenario-based guidance tailored to specific business decisions, making it a practical next step for teams that need to move from strategic direction to execution.
Cardan Shaft Market
For detailed analysis of this topic, please visit the official page: Automotive Drive Shaft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


