



Pad Printing Supplies Market: Why 5.65% CAGR Reshapes Industry Dynamics

Strategic Shifts and Commercial Opportunities in the Global Pad Printing Supplies Market
The pad printing supplies market has evolved from a niche decorating technique into a critical enabler of mass customization, product identification, and industrial marking across multiple manufacturing verticals. Over the 2020-2025 period, the sector demonstrated steady expansion, reaching a valuation of 182.0 million USD in 2025. Forward projections indicate the market will scale to 267.3 million USD by 2032, supported by a compound annual growth rate of 5.65 percent through the forecast horizon. This trajectory reflects a maturing yet still dynamic landscape where incremental technological improvements, regulatory tightening, and shifting end-user expectations are reshaping competitive priorities. For executives and investors, the market no longer rewards pure volume play; it rewards precision in formulation, compliance readiness, and the ability to integrate consumable supply with automated production workflows.
The growth pattern is not uniform across all segments. Historical momentum has been anchored by established industrial applications, but the forward curve is increasingly influenced by regions and use cases that demand higher durability, stricter chemical compliance, and faster turnaround. The market structure remains moderately fragmented, with the top three players capturing roughly a third of total revenue and the top five accounting for just under half. This concentration level signals a space where scale advantages exist but are not insurmountable, and where differentiated value propositions can still secure meaningful share. The following analysis examines the structural challenges, demand drivers, competitive positioning, and forward trends that will determine which organizations capture the next wave of value.
Market Landscape and Core Challenges
The pad printing supplies market has built its recent growth on a foundation of recurring industrial demand, but the operating environment is being reshaped by three overlapping pressures that decision-makers cannot treat as background noise. The first is the compliance burden surrounding ink chemistry and material safety. Formulators and converters are no longer competing only on adhesion, color fidelity, or drying speed. They are increasingly evaluated against a widening set of regulatory expectations that govern volatile organic compound emissions, restricted substances, and end-use safety. Products intended for toys, consumer electronics, packaging decoration, or medical-adjacent components must pass through certification and documentation requirements that vary by jurisdiction. This raises the cost of entry for new formulations and forces suppliers to treat compliance as a core product attribute rather than a post-launch add-on.
The second challenge is the tension between automation throughput and consumable consistency. As pad printing moves from manual or semi-manual cells to integrated automated lines, the tolerance for variation shrinks. Pad wear, cliché durability, ink viscosity stability, and cup performance become process reliability issues rather than simple replenishments. Manufacturers that upgrade equipment often discover that the limiting factor is not the machine itself but the consistency of the consumables feeding it. This creates a structural demand for higher-grade pads, more stable ink systems, and tighter technical support, while also exposing suppliers that rely on commodity-grade inputs to quality and claim risks.
The third challenge is cost volatility in raw materials and logistics, layered with a shift in buyer behavior toward total cost of ownership. Price-per-liter comparisons are losing relevance in many procurement cycles because they ignore waste reduction, line downtime, rework, and compliance risk. Buyers are increasingly scrutinizing whether a marginally cheaper ink generates higher hidden costs through slower curing, more frequent pad changes, or failed audits. Suppliers that compete primarily on unit price face margin compression, while those that can demonstrate measurable process efficiency and reduced compliance exposure are better positioned to defend their positioning. Together, these challenges reframe the market from a transactional supplies business into a performance and risk-management partnership.
Key Drivers of Market Evolution
Technological Innovation and Formulation Advances
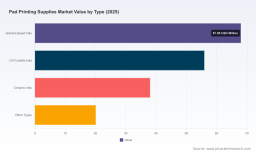
Technology is reshaping the pad printing supplies market along two reinforcing paths: ink performance and process integration. On the ink side, the industry is moving toward systems that balance print quality with environmental and safety constraints. Solvent-based formulations continue to hold a strong position where adhesion and metering stability are critical, but the innovation frontier is increasingly defined by how cleanly those systems can operate and how easily they fit into controlled production environments. UV-curable options have gained relevance where rapid hardening, reduced handling, and energy-efficient processing are priorities, especially in high-speed decorative and marking applications. Ceramic-based inks remain essential for products that must withstand elevated temperatures and harsh surface conditions, maintaining their role in demanding industrial and household contexts. The broader trend is not replacement of one chemistry by another, but the expansion of application-specific toolkits that let manufacturers match consumables to substrate, curing method, and end-use exposure.
Worldwide Specialty Ink Market
Beyond chemistry, the integration of consumables with automation is becoming a differentiator. Suppliers that support custom mixing, automated ink delivery, pad replacement schedules, and cliché management reduce the operational friction that often slows line optimization. When consumables are treated as part of a controlled process rather than as standalone purchases, manufacturers achieve more predictable output and fewer interruptions. This shift is particularly visible in high-volume environments where even small improvements in metering consistency or pad life translate into meaningful throughput gains. The strategic implication is that value is migrating from the mere supply of materials toward the supply of repeatable, documented process performance.
Regulatory and Compliance Pressure as a Market Filter
Regulatory expectations are increasingly functioning as a market filter, shaping both product design and customer selection. Standards and directives associated with chemical safety, restricted substances, and end-use certification are no longer isolated concerns for specific niches. They influence purchasing decisions across packaging decoration, electronics marking, and consumer goods. In practice, this means that documentation, substance control, and test evidence have become commercial assets. Ink systems that can demonstrate alignment with major compliance frameworks reduce the burden on downstream manufacturers and lower the risk of downstream audit failures or product holds.
Recent market activity illustrates this shift clearly. One major supplier introduced a solvent-based and sustainable pad printing ink system designed to support recycling of recovered packaging materials while maintaining durability for toys, electronics, automotive components, and promotional items. The same offering was positioned as free from phthalates and BPA and suitable for printing on the non-food contact side of packaging, with conformance claims tied to multiple regulatory frameworks. Separately, another supplier achieved certification for a group of eco-focused pad printing inks, emphasizing freedom from naphtha, PAH, and cyclohexanone, with compliance references to REACH, RoHS, and EN 71-3. These moves are not isolated product launches; they signal a broader market dynamic in which environmental and safety credentials are becoming decision-critical, especially where procurement teams must justify material choices to internal stakeholders and external auditors alike.
Digital Textile Printing Ink Market
Demand-Side Shifts in Manufacturing and Branding
Demand is being shaped by a combination of industrialization, product complexity, and brand expectations. Manufacturers are printing more than logos; they are applying identification marks, functional labels, safety information, and decorative finishes that must survive handling, cleaning, and time. The growth of short-run customization and rapid product variation also increases the value of flexible pad printing supplies that can adapt to frequent changeovers without sacrificing quality. In electronics, smaller components and tighter tolerances increase the need for precise deposition and stable ink behavior. In glass and plastic products, surface diversity demands inks and pads that can maintain adhesion across varying textures and finish types. In ceramic and porcelain applications, the need for durability under heat and moisture keeps specialty ink systems relevant.
At the same time, downstream brands and contract manufacturers are placing greater weight on process reliability and material documentation. Procurement is increasingly influenced by the need to reduce variability across shifts, minimize rework, and avoid supply-chain surprises caused by reformulation or compliance gaps. This makes supply consistency, technical support, and change-management capability more valuable than ever. Buyers are not simply purchasing pads, inks, and plates; they are purchasing predictability.
Supply Chain and Cost Structure Realignment
Cost structure is being rethought around durability, waste, and support rather than headline price. Volatile input costs and logistics uncertainty have made it harder for suppliers to compete on discount alone, while buyers are more willing to pay for solutions that reduce line waste or improve uptime. The result is a gradual realignment toward value-based positioning, where suppliers justify their pricing through measurable operational benefits. This also favors companies with stronger technical service models, more controlled formulation pipelines, and the ability to provide custom mixes or region-specific compliance support. For customers, the supply chain is becoming a source of process advantage rather than just a procurement function.
Competitive Positioning and Strategic Differentiation
The competitive landscape is defined by a mix of established ink and consumables specialists, regional machine-and-consumable integrators, and suppliers that combine equipment, tooling, and consumables under one roof. The distinct strategic advantage in this market is rarely derived from a single product feature. It is built from the combination of formulation capability, compliance readiness, automation support, and service responsiveness. Companies that treat pad printing supplies as a system rather than a commodity are better positioned to retain customers through line upgrades, regulation changes, and application expansion.
On the ink and consumables side, several players are competing on specialized chemistry and certification strength. One German-based supplier maintains a broad portfolio covering inks, clichés, printing pads, ink and doctoring cups, auxiliary materials, and laser cliché production, positioning itself as a full-line provider for pad printing operations. Another German formulates a wide range of solvent-based and UV-curable inks oriented toward industrial decoration, marking, and identification, emphasizing breadth across application types. In the United States, a major international supplier has pushed eco-oriented formulations, including solvent-based and UV pad printing inks designed without phthalates or BPA for packaging and product decoration, appealing to buyers who need both performance and cleaner substance profiles. A separate U.S. consumables specialist has emphasized eco-certified formulations, with a portion of its SB Eco Series inks achieving GOTS certification and aligning with REACH, RoHS, and EN 71-3 requirements. This certification-driven positioning is strategically important because it converts compliance into a marketable advantage rather than a hidden cost.
A second competitive cluster revolves around integration with equipment and automation. One U.S. supplier focuses on custom pad printing machines, tooling, fixtures, and consumables for high-volume automated applications, effectively combining hardware and consumables to reduce sourcing complexity. Another U.S. player offers a wide range of pad printing machines, fixtures, inks, pads, printing plates, and operates a large North American ink warehouse, leveraging distribution scale and inventory depth as a service advantage. A silicone and consumables-focused supplier produces in-house silicone pads, inks, plates, fixtures, and accessories, giving it tighter control over the pad supply chain and a direct route to custom specifications. Yet another U.S. company emphasizes custom-mixed inks, printing pads, cliché plates, and full automation support, highlighting the importance of flexibility in demanding production environments.
The competitive pattern suggests two parallel value routes. The first is depth in formulation and compliance, where differentiation comes from certification, substance control, and application-specific ink performance. The second is breadth and integration, where differentiation comes from equipment compatibility, inventory availability, custom mixing, and process support. Companies that can bridge both routes, even partially, gain a stronger hold on customers because they reduce the number of separate sourcing decisions and make it easier to standardize across multiple lines or sites.
Market structure is likely to evolve through selective consolidation and targeted specialization rather than across-the-board merger activity. Larger players with distribution scale and compliance infrastructure can absorb smaller regional suppliers or geographic distributors, especially where customers value single-source reliability. At the same time, niche specialists can prosper by owning a specific application, chemistry, or certification niche that larger generalists cannot serve as precisely. New entrants face a meaningful barrier in formulation know-how, certification timelines, and established technical service relationships, but they can still gain traction by addressing underserved compliance needs or automation-centric consumable packages. The most durable strategy appears to be building defensible positioning through either regulatory readiness and documented performance, or integrated automation support and customizability, while avoiding reliance on price alone.
Forward Trends and Commercial Implications
Compliance and Eco-Aligned Formulations Will Become Baseline Expectations
Over the next three to five years, the market is likely to see compliance-friendly and lower-impact formulations move from premium differentiators to baseline requirements in many application areas. Buyers serving consumer-facing, electronics, and packaging-adjacent markets will increasingly expect substance control, test evidence, and documentation as standard deliverables. This trend favors suppliers with established certification pathways and formulation discipline, while raising the risk for those that treat compliance as reactive. The commercial opportunity lies in building repeatable compliance narratives that simplify customer purchasing and reduce audit friction. The uncertainty is that regulatory expectations can diverge by region and application, creating a moving target for global suppliers and requiring localized documentation strategies.
Automation-Ready Consumables and Process-Locked Partnerships
As more production lines adopt higher levels of automation, consumables will be evaluated for their behavior inside controlled systems rather than in isolation. This should increase demand for inks and pads that support consistent metering, stable curing or drying, predictable wear, and easier integration with auto-ink delivery or changeover workflows. Suppliers that provide custom mixing, process tuning, and technical support will be better positioned to lock in long-term relationships, because the value they deliver is tied to line performance rather than unit transactions. The opportunity is to design consumables and service packages that reduce downtime and variability. The risk is that automation increases the stakes of inconsistency; a single recurring failure mode can erode trust quickly and push buyers toward more controlled supply alternatives.
Application Expansion and Regional Rebalancing
Forward growth is likely to be supported by continued application expansion across glass and plastic products, ceramic and porcelain items, electronic components, and other industrial uses, with regional demand patterns shifting as manufacturing footprints and export channels evolve. Regions with expanding industrial output, packaging activity, and consumer goods production will create incremental demand for marking, decoration, and identification supplies. The commercial opportunity is to align product portfolios and service coverage with the applications and geographies that are scaling fastest, rather than assuming legacy demand patterns will persist unchanged. The downside is that regional expansion can expose suppliers to new compliance regimes, logistics constraints, and competitive responses, making localized positioning and supply resilience more important than generic global messaging.
Actionable Implications for Decision-Makers
For manufacturing and operations leaders, the priority is to treat pad printing supplies as a process variable with measurable business impact. Procurement should evaluate ink systems, pads, and cliché solutions against line throughput, waste, changeover time, and compliance exposure, not just purchase price. Where production is moving toward higher automation or stricter end-use requirements, teams should prioritize suppliers that can provide documented performance, stable formulation pipelines, and responsiveness to custom specifications. Establishing clear acceptance criteria for consistency and certification documentation can reduce the risk of downstream failures and make supplier comparisons more objective.
For investors and corporate development teams, the market presents opportunities in players with credible compliance positioning, formulation depth, and integration with automation-focused customers. Businesses that have built certification readiness, custom-mixing capability, or strong regional distribution and inventory support are better placed to defend margins and capture share from purely transactional competitors. At the same time, due diligence should account for regulatory variability, raw-material exposure, and the durability of customer relationships beyond single projects. The most attractive profiles typically combine technical differentiation with recurring consumable demand and clear alignment to end-use compliance needs.
PW Consulting
For procurement and sourcing professionals, the strategic task is to move from transactional purchasing to supplier partnership models that reduce total operating risk. That includes evaluating eco-oriented and certified formulations where relevant, aligning consumable selection with equipment and line requirements, and ensuring that documentation and compliance claims are part of the sourcing decision. Where multiple sites or product families are involved, standardization on a smaller set of validated consumables can improve consistency and simplify audits, provided the selected options remain flexible enough for application-specific needs. In markets where compliance expectations are rising, sourcing decisions made without adequate documentation can create hidden cost and operational risk.
For organizations seeking deeper segmentation data, company-level positioning, and scenario-based guidance across regions and applications, the full PW Consulting market research report provides a more detailed breakdown of revenue splits, competitive profiles, and forecast assumptions. The report supports more precise planning by extending the core market view into actionable detail for procurement strategy, investment screening, and long-range capacity or portfolio decisions.
For detailed analysis of this topic, please visit the official page: Pad Printing Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


