



Bovine Lactoferrin Market 2026: How the 4.3% CAGR and Asia Pacific’s 325.41M Surge Redefine Growth

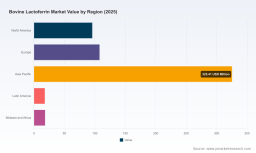
Strategic Shifts and Commercial Opportunities in the Bovine Lactoferrin Market
Market Snapshot and the Structural Inflection Point
The bovine lactoferrin market has moved from a niche specialty ingredient to a strategically significant component of the global nutrition and health ecosystem. Valued at approximately 378.0 million USD in 2020, the market expanded to 565.08 million USD by 2025, reflecting a compound annual growth rate of 4.3 percent over the 2026-2032 forecast period. Annual revenue is projected to progress from 591.33 million USD in 2026 toward 747.35 million USD by 2032, signaling sustained demand expansion rather than a temporary cyclical uptick.
This trajectory is not uniform across segments or geographies. The market is fragmenting along functional, regulatory, and sourcing lines, creating pockets of high-value growth alongside commodity-like pressure in commoditized supply chains. For executives and investors, the headline growth rate obscures a more nuanced reality: value migration is occurring toward producers who can guarantee purity, traceability, functional consistency, and regulatory clearance across multiple jurisdictions simultaneously.
Several structural challenges and inflection points are reshaping how participants position themselves:
- Functional consistency versus scale tension . Manufacturers face mounting pressure to deliver batch-to-batch consistency in iron-binding capacity, protein integrity, and microbiological profile while scaling output. As demand concentrates in infant nutrition and premium dietary supplements, buyers increasingly treat lactoferrin as a functional active rather than a bulk dairy by-product, raising the cost of quality failures.
- Regulatory divergence as a market filter . Jurisdictional differences in ingredient classification, novel food assessment, and safety notifications are creating asymmetric market access. Companies that can navigate multiple regulatory pathways simultaneously are gaining disproportionate commercial leverage, while those dependent on a single region face constrained expansion options.
- Feedstock volatility and margin sensitivity . High-quality bovine milk feedstock exhibits price volatility tied to seasonal variations, feed costs, and broader dairy market fluctuations. This introduces margin unpredictability for producers and complicates long-term pricing commitments for formulators, particularly in categories where lactoferrin represents a meaningful share of raw material cost.
These dynamics are not merely operational headaches; they are strategic filters. They determine which players can credibly serve premium segments, which can secure multi-year supply agreements, and which are relegated to price-competitive commodity positions.
Key Drivers Reshaping the Market
Precision fermentation and bioprocessing breakthroughs
A defining shift in the market is the emergence of precision-fermented bovine lactoferrin as a commercially viable alternative to milk-derived extraction. In May 2025, TurtleTree received the first FDA no-questions GRAS letter for precision-fermented bovine lactoferrin, enabling broader use in food and supplement applications. Around the same time, the FDA issued a no-questions GRAS letter for recombinant bovine lactoferrin isolate produced by Komagataella phaffii M020. These regulatory milestones matter because they open a supply pathway that is less tethered to dairy feedstock volatility and potentially more scalable for high-purity applications.
The strategic implication is twofold. First, fermentation-based supply expands the addressable market by reducing dependency on milk supply constraints and offering a potentially more controlled production environment. Second, it introduces a new competitive axis: producers of milk-derived lactoferrin must differentiate on native protein attributes, organic certification, and established regulatory status, while fermentation players compete on scalability, purity, and pricing predictability. This does not eliminate dairy-derived lactoferrin; rather, it segments the market into performance- and credential-driven tiers.
Regulatory acceleration and market access realignment
Regulatory developments are simultaneously opening and structuring demand. China eliminated import tariffs on dairy-based formula foods for special medical purposes, effective in late 2023 and continuing into 2025, creating a more favorable environment for specialized nutrition imports. In parallel, the European Union assessed bovine lactoferrin as a food ingredient in 2025 under Novel Food regulation for uses in infant formula, supplements, and sports nutrition. These processes are not just compliance exercises; they redefine which applications can scale and which regions can serve as growth platforms.
Bovine Colostrum Market
For commercial planners, the key insight is that regulatory clarity often precedes demand formalization. Once an ingredient is cleared for specific categories, formulators can invest in product development, claim substantiation, and distribution with reduced regulatory risk. The uneven pace of approvals across regions means that early movers in cleared markets can build brand and supply relationships before competition intensifies.
Demand-side evolution toward functional and clinical nutrition
Consumer and enterprise demand is increasingly shaped by functional outcomes rather than generic protein supplementation. Infant formula remains a central application area, driven by the perceived nutritional and immune-support benefits of lactoferrin for early-life development. Dietary supplements continue to absorb meaningful volume as well, particularly where lactoferrin is positioned around immune health and active wellness. At the same time, interest is expanding into sports nutrition, medical nutrition, and functional food and beverage formats, where lactoferrin's iron-binding and bioactive properties are being repurposed for differentiated product claims.
This demand evolution raises the stakes for ingredient suppliers. Formulators want documentation, stability data, application compatibility, and regulatory support, not just price and bulk availability. The winners are increasingly those who function as application partners, helping customers integrate lactoferrin into complex matrices while maintaining label-claim integrity and sensory acceptance.
Supply chain reconfiguration and capacity investments
Capacity expansion is a visible signal of strategic confidence in the category. Beston Global Food Company Ltd expanded lactoferrin production capacity at its Jervois dairy factory in Australia to up to 25 MT of 95% pure lactoferrin per year. More broadly, the U.S. Department of Energy invested $9.7 million in alternative protein projects, including lactoferrin, to support decarbonization of the food sector in 2025, reinforcing the policy tailwinds behind alternative and lower-impact production routes.
These investments reflect a broader realignment in supply chain thinking. Participants are increasingly weighing feedstock security, geographic diversification, and processing efficiency alongside traditional metrics such as throughput and unit cost. For buyers, this means supply is becoming more modular and regionally distributed, which can improve resilience but also increases the importance of qualification, vendor auditing, and multi-source strategies.
Competitive Landscape and the Emerging Strategic Playbook
The bovine lactoferrin market remains moderately concentrated, with CR3 at 34.2 percent and CR5 at 41.5 percent. This concentration level suggests a landscape where leading players hold meaningful share but no single entity dominates the category outright. The result is a market in which differentiation, application expertise, and regulatory positioning matter as much as sheer scale.
Worldwide 2'-Fucosyllactose (2'-FL) Market
Several patterns distinguish the more strategically advantaged participants:
- Vertical integration from dairy processing to high-value ingredients . Companies rooted in dairy processing are leveraging existing milk supply, quality systems, and co-product economics to produce lactoferrin alongside broader ingredient portfolios. This model can lower effective feedstock risk and provide operational leverage, particularly when lactoferrin is positioned within a wider nutritional ingredients offering rather than as a standalone commodity.
- Specialization in organic and native-grade positioning . A subset of manufacturers is building reputation around native bovine lactoferrin with specific certification profiles, including organic grade for infant nutrition and dry-mix applications. This approach targets premium segments where purity credentials, traceability, and application-specific documentation command higher margins and deeper customer stickiness.
- Process technology ownership and scale leadership . Long-standing technology relationships and proprietary processing approaches remain a durable advantage. One of the largest-volume producers uses Morinaga process technology, illustrating how established production know-how can underpin scale leadership and consistent output. In a category where functional performance depends heavily on processing integrity, technology lineage is a meaningful moat.
- Regional branding and traceability narratives . Some producers emphasize origin-specific attributes, such as Australian whey sourcing or Swiss production, to differentiate in premium markets. These narratives can support pricing power when they are paired with verifiable quality systems and strong documentation, especially in categories where safety and provenance are closely scrutinized.
Strategic developments in 2024 and 2025 point to an accelerating evolution in the competitive map:
- Joint ventures and commercialization partnerships . In December 2025, All G and Armor Protéines formed a joint venture to scale production and commercialization of human and bovine lactoferrin, with All G's first bovine lactoferrin powder product launching in late 2025. This reflects a broader trend in which companies combine complementary capabilities—one partner may bring production or process strengths, while the other contributes market access or application expertise—to reduce time to scale and de-risk commercialization.
- Capital reinforcement for first-mover positioning . In January 2025, All G raised over A$10 million to support commercial-scale production of its first bovine lactoferrin product, with launch targeted for Q1 2026. Capital inflows of this type often signal investor conviction that scale, purity, and timing can translate into defensible market positions, particularly when paired with clear application roadmaps.
- Regulatory milestones enabling category expansion . TurtleTree's FDA GRAS notice and related regulatory activity are lowering barriers for precision-fermented lactoferrin in food and supplement channels. This expands the competitive field by enabling new entrants to pursue applications that previously depended on milk-derived supply and more complex compliance pathways.
- Capacity and purity upgrades among established producers . Beston Global Food Company Ltd's capacity expansion and emphasis on up to 95% purity illustrate how incumbents are responding to premiumization by improving both volume and grade. This is a competitive response to buyers who increasingly evaluate lactoferrin on functional performance and specification consistency rather than price alone.
The market is therefore not simply consolidating or fragmenting; it is stratifying. At one end, price-competitive volume players compete on supply efficiency and broad availability. At the other, capabilities-driven participants compete on regulatory clearance, application support, purity, and brand credibility. Between these poles, partnerships and joint ventures are becoming a practical mechanism for bridging production scale with commercialization reach.
A critical trend to watch is the rise of hybrid supply strategies. As fermentation-based and dairy-derived routes both advance, some downstream buyers will seek multi-source portfolios to balance cost, resilience, and functional requirements. That, in turn, may push ingredient suppliers to develop clearer product-line segmentation, with distinct specifications and value propositions for different end-use categories rather than offering a single undifferentiated lactoferrin product.
Outlook for the Next Three to Five Years
Precision-fermented lactoferrin will move from regulatory novelty to commercial optionality
The 2025 regulatory progress for precision-fermented bovine lactoferrin is likely to translate into a growing set of commercial pilots and selective scale-up over the next few years. The near-term opportunity lies in applications where controlled purity, supply consistency, and reduced dairy feedstock exposure provide tangible value, such as specialized supplements and certain functional food formats. Over time, fermentation routes could pressure margins in commoditizing segments while also expanding total addressable demand by making high-purity lactoferrin more broadly available.
The commercial risk is that fermentation-based supply initially enters at a cost or scale disadvantage in some applications, or faces its own regulatory and consumer-acceptance hurdles in specific markets. Companies will need to track not just approval status, but actual adoption curves, labeling outcomes, and procurement economics before treating fermentation as a full substitute for milk-derived supply.
Demand will increasingly center on documented functionality and application fit
Over the next three to five years, procurement decisions are likely to place greater weight on functional documentation, stability performance, and compatibility with target matrices. Infant nutrition and premium dietary supplements will remain anchor categories, but the growth conversation will also include sports nutrition, medical nutrition, and functional food and beverage formats where lactoferrin is used for differentiated benefits. Suppliers that can provide robust technical support and category-specific solutions will be better positioned to capture value than those competing primarily on volume and price.
Regulatory and geopolitical asymmetry will shape geographic expansion
PW Consulting
Because regulatory pathways and trade conditions are not moving in lockstep, geographic expansion will increasingly require localized regulatory strategy rather than uniform global positioning. Tariff changes, novel food assessments, and import conditions can open or constrain markets with little warning. Participants that build regional regulatory intelligence into their product and supply planning will gain faster market entry and fewer stalled launches. At the same time, feedstock cost volatility and dairy market swings will continue to require pricing and sourcing strategies that can absorb short-term disruption without undermining long-term contract credibility.
Strategic Actions for Decision Makers
For manufacturers and ingredient suppliers
- Define clear product-tier strategies that separate premium, application-specific offerings from volume-oriented supply. Purity, certification, documentation, and application support should be explicitly mapped to the segments where they generate pricing power and customer retention.
- Invest in regulatory and market-access capabilities as a core commercial function. Track GRAS and novel food developments, tariff shifts, and category-specific clearance status in target markets so that product roadmaps are aligned with where demand can realistically scale.
- Evaluate partnerships and joint ventures where complementary strengths accelerate scale or market entry. In a moderately concentrated market, combining process technology, supply access, or application expertise can be more efficient than building every capability internally.
For investors and corporate development teams
- Assess lactoferrin exposure in the context of application mix and supply route resilience rather than top-line growth alone. Value creation will likely accrue to businesses that can protect margins through differentiation, multi-source options, or regulatory positioning, not simply to those with the largest volume footprint.
- Monitor fermentation-based entrants as both competitors and potential partnership candidates. The strategic question is not whether alternative production will matter, but where it will be economically superior and which applications it will unlock first.
- Watch for consolidation signals around capacity, purity upgrades, and commercialization agreements. Joint ventures and targeted capital raises may indicate where the market is moving from early validation toward scaled commercialization.
For procurement and supply chain leaders
- Diversify sourcing strategies across dairy-derived and emerging supply routes where specifications and compliance profiles align with product requirements. Multi-source portfolios can improve resilience against feedstock volatility and regional supply disruptions, provided qualification and documentation are managed rigorously.
- Standardize technical and regulatory evaluation criteria for lactoferrin ingredients. Batch consistency, purity specifications, stability data, and application compatibility should be assessed with the same discipline as cost, especially when lactoferrin supports claim-sensitive formulations.
- Build forward-looking sourcing plans around expected regulatory and capacity changes. As new capacity comes online and regulatory clearances expand, early qualification of alternative suppliers can reduce launch risk and preserve negotiating leverage.
The bovine lactoferrin market is entering a phase in which commercial success is increasingly determined by specificity: specificity of application, of regulatory readiness, of supply strategy, and of value proposition. Broad market growth provides opportunity, but durable advantage will depend on which organizations can translate that growth into differentiated, defensible positions across increasingly segmented demand and supply environments. Detailed segmentation data, company-level capability assessments, and scenario-based market outlooks can sharpen these decisions further, especially for teams weighing entry timing, capacity commitments, and multi-market rollout strategies.
For detailed analysis of this topic, please visit the official page: Bovine Lactoferrin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


