



High Precision Planetary Gear Reducers Market: How Asia Pacific’s 1772M Demand Reshapes Growth

High Precision Planetary Gear Reducers: Strategic Trends and Commercial Opportunities in a Maturing Market
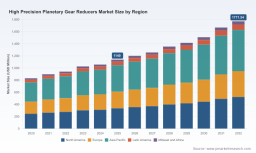
The high precision planetary gear reducer market has entered a phase of disciplined expansion, transitioning from a niche component supplier ecosystem to a critical enabler of next-generation motion control. Valued at approximately $1,140 million in 2025, the market has sustained a compound annual growth rate of 6.5% over the 2026–2032 horizon, with forward projections pointing toward $1,771 million by 2032. This trajectory reflects a fundamental shift in how industrial systems are engineered: precision gearing is no longer a passive power transmission element but an active determinant of throughput, energy efficiency, and operational reliability. The market’s evolution is shaped by tightening technical standards, accelerating automation adoption, and a competitive landscape where regional manufacturing footprints and application-specific engineering increasingly dictate commercial advantage.
For executives and investors, the opportunity lies not in capturing volume at any cost, but in aligning product architectures with the demand curves that will define the next decade. The following analysis maps the structural drivers, competitive dynamics, and actionable positioning strategies that will determine which players capture sustainable margin expansion and market relevance.
Market现状与核心挑战
The market’s current size and forecast profile reveal a sector that has survived the volatility of the early 2020s and is now consolidating around predictable, application-driven demand. Growth is no longer propelled by broad industrial recovery alone but by specific technology adoption cycles where precision gearing serves as a bottleneck or enabler. Three structural challenges define the current inflection point.
Precision Verification and Thermal Stability Requirements
Transmission performance is increasingly evaluated under dynamic operating conditions rather than static laboratory benchmarks. Updated international transmission precision guidelines now incorporate more stringent dynamic testing requirements under thermal equilibrium, raising the bar for validation protocols and forcing manufacturers to redesign testing infrastructure and quality assurance workflows. This shift compresses development cycles for new product lines, increases certification costs, and rewards suppliers who can demonstrate repeatable performance under sustained thermal loads. Companies that rely on legacy verification methods face higher rejection rates, longer customization lead times, and diminished credibility in applications where micro-backlash variations directly translate into positioning errors.
Automation Adoption as a Volume Amplifier
Global industrial robot installations surpassed 590,000 units in 2023, with over 62% of those installations incorporating high precision planetary gear reducers for torque control and precision motion. Simultaneously, the adoption of servo-based automation systems expanded by 13.4% in 2024, reflecting a broader structural preference for closed-loop motion control in both discrete manufacturing and process equipment. This demand surge is not uniform across sectors; it concentrates where cycle time reduction, repeatability, and footprint constraints justify the premium for precision gearing. The challenge for suppliers is to scale production without diluting engineering responsiveness, as standardization and application support become equally valuable as raw output capacity.
Geopolitical and Regional Manufacturing Realignment
Machine tool exports exceeded $10.7 billion in 2023, underscoring the continued strength of precision manufacturing exports in major industrial economies. Yet the same export momentum coincides with growing localization pressure in end markets, where lead time expectations, supply chain resilience, and total cost of ownership calculations are pushing buyers toward regional assembly and faster catalog fulfillment. Suppliers that depend on centralized production and long freight routes are encountering longer quotation-to-delivery windows, currency exposure, and reduced agility in responding to regional specification variations. The market is gradually rewarding localized capacity and modular product platforms that can be configured close to the point of use.
关键驱动因素分析
The market’s growth trajectory is being pulled by a small set of structural forces that interact with each other faster than historical forecasting models anticipated. Understanding these drivers is essential for prioritizing R&D investment, capacity strategy, and commercial positioning.
PW Consulting Automotive & Machinery Research Center
Technical Innovation and Materials Engineering
Precision gearing performance is increasingly determined by material selection, heat treatment consistency, and gear geometry optimization rather than by incremental scale gains. Manufacturers are moving toward carburized alloy steels and multi-planetary architectures that distribute load more evenly across tooth engagement surfaces, extending fatigue life and reducing torque ripple under variable loading. These design choices directly address the thermal stability requirements now embedded in updated precision guidelines, enabling gearboxes to maintain backlash characteristics across longer duty cycles. Innovation is also extending into lubrication management, sealing integrity, and housing stiffness, where marginal gains compound into measurable improvements in positioning accuracy and maintenance intervals. For suppliers, the commercial implication is clear: technical differentiation is shifting from catalog specifications to verifiable performance under real operating conditions, and the winners will be those who can translate materials engineering into documented reliability advantages.
Policy and Standardization Momentum
Standardization is no longer a passive compliance exercise; it is actively shaping purchasing criteria and supplier qualification. The updated transmission precision framework has elevated dynamic thermal testing from an advisory practice to a market expectation, which in turn creates a barrier for suppliers lacking rigorous validation capability. At the same time, automation adoption trends are being reinforced by broader industrial modernization objectives in multiple regions, where labor productivity, energy efficiency, and traceability requirements are pushing manufacturers toward integrated servo-mechanical systems. Policy environments that favor automation deployment, machine tool modernization, and local content preferences indirectly expand the addressable base for high precision reducers by accelerating the transition from conventional mechanical drives to precision motion control architectures. The strategic takeaway is that standardization and policy alignment are reshaping the qualification filter: suppliers that can demonstrate compliant test documentation, traceable manufacturing processes, and predictable delivery are gaining preferential access to tenders and long-term automation programs.
Demand-Side Behavior and Application Specificity
End-user behavior is shifting from generic specification purchasing toward application-tuned selection. In robotics, compact motion control demands low-backlash performance and minimal size, pushing suppliers toward integrated servo gear reducers that balance torque density with repeatability. In industrial manufacturing, the emphasis is on torque capacity, serviceability, and integration with higher-level control architectures, favoring product lines that can be configured for a range of ratios and mounting constraints. Semiconductor equipment applications impose a different set of requirements, where cleanliness, thermal steadiness, and micro-positioning reliability determine component selection more than absolute cost. This demand differentiation means that volume growth is increasingly segmented: suppliers that maintain a single generic product strategy face margin compression, while those that engineer for specific application envelopes can command pricing stability and deeper customer lock-in.
Supply Chain Structure and Cost Positioning
Cost structures are being reshaped by localization decisions and assembly sequencing. A notable example is the initiation of local assembly of P2.e planetary gear units in South Carolina, which reduced lead times for cataloged ratios to as short as six weeks. This move illustrates a broader trend: regional assembly capability is becoming a commercial differentiator because it shortens delivery cycles, reduces freight exposure, and improves responsiveness to specification adjustments without requiring full product redesign. At the same time, raw material consistency, heat treatment capacity, and precision machining availability remain binding constraints on output quality. Suppliers are responding by tightening upstream material sourcing, increasing in-house treatment capability, and standardizing modular ratio configurations to reduce custom engineering load. The cost implication is not simply lower unit pricing but lower total cost of ownership for buyers, which is increasingly the decisive factor in multi-year automation programs.
竞争格局与领先策略
The competitive landscape is characterized by moderate concentration, with the top three suppliers accounting for approximately 25% of market revenue and the top five extending to 35%. This distribution leaves substantial room for regional specialists, application-focused entrants, and integrated manufacturers to compete on engineering fit and delivery reliability rather than price alone. The market is not yet consolidating into a handful of dominant players, but it is stratifying around distinct value creation models.
Strategic Positioning Among Leading Suppliers
Leading companies have carved out defensible positions by aligning product architecture with specific application expectations. Neugart GmbH emphasizes low backlash and high rigidity across Economy and Precision Line series, targeting industrial motion control environments where repeatability and mechanical stiffness are paramount. Wittenstein SE competes on low-backlash servo gearboxes and hygienic design variants, positioning itself for demanding applications where cleanliness and precision must coexist. Apex Dynamics Inc. focuses on helical gearing for low backlash and high torque in servo applications, appealing to customers who prioritize torque transmission smoothness within compact envelopes. Harmonic Drive LLC markets zero-backlash planetary gearboxes engineered for robotics and precision actuation, reinforcing a performance-first positioning where elimination of mechanical play is the central value proposition. SEW-EURODRIVE GmbH & Co. KG offers high-torque planetary gear units with ratings up to 124 kNm, addressing industrial and servo applications where load capacity and durability determine system sizing. In parallel, several regionally anchored manufacturers are expanding their visibility through trade engagement and localized engineering support, signaling a market where regional presence, material specifications, and application demonstration increasingly influence procurement decisions.
Differentiation and Margin Protection
Sustainable differentiation in this market rarely comes from a single specification breakthrough; it emerges from the combination of precision validation, application support, and supply responsiveness. Suppliers that can document thermal-stable backlash behavior, provide modular ratio sets, and offer predictable delivery timelines are better positioned to protect margins than those competing primarily on unit price. Engineering services also matter: the ability to advise on mounting configurations, lubrication intervals, and integration with servo drives reduces implementation risk for buyers and increases switching costs. In practice, the most resilient players treat the gear reducer not as a standalone commodity but as part of an integrated motion solution, where documentation, testing evidence, and post-sale technical support reinforce the initial purchase decision.
Robot Joint Precision Reducers Market
Market Evolution: Integration, Fragmentation, and New Entrants
The landscape is evolving along two simultaneous tracks. On one hand, larger industrial drive and transmission groups continue to integrate planetary gearing into broader automation portfolios, leveraging existing distribution channels and application engineering teams. On the other hand, the market remains open to regional specialists and application-focused entrants who can win on precision claims, localized assembly, or domain-specific validation. New entrants are most likely to succeed where they can demonstrate measurable advantages in thermal stability, backlash control, or delivery speed, rather than attempting to compete across the full product spectrum. Consolidation is expected to remain selective, driven by the need to secure material supply, testing capability, and regional service coverage rather than by volume aggregation alone. The practical implication is that competitive advantage will increasingly belong to suppliers who can combine engineering credibility with agile commercial execution.
未来趋势预测
The next three to five years are likely to be defined by tighter performance verification, expanding application reach, and continued localization of supply. These trends create clear commercial opportunities, but they also introduce execution risks that demand disciplined planning.
Thermal-Validated Precision as a Baseline Expectation
Dynamic thermal testing and equilibrium-based verification are likely to move from guideline adherence to purchasing prerequisite. As end-users integrate gear reducers into high-duty-cycle automation systems, they will demand documented performance under sustained loads rather than nominal specifications. Suppliers that invest early in thermal validation infrastructure, repeatable test protocols, and transparent documentation will gain access to higher-value programs and reduce quotation-to-approval friction. The commercial opportunity lies in positioning precision verification as a risk-reduction asset for system integrators and original equipment manufacturers, not merely as a compliance cost. The risk, however, is that validation requirements raise the entry barrier and compress margins for suppliers that cannot efficiently scale testing throughput.
Worldwide Precise Servo Reducer Market
Robotics and Semiconductor-Driven Demand Expansion
Robotics will continue to be a primary volume driver, but high-precision planetary gear demand will increasingly be shaped by semiconductor equipment and advanced manufacturing systems that require micro-positioning reliability and thermal steadiness. This divergence means that growth will not be uniform; it will concentrate in applications where positioning accuracy directly affects yield, throughput, or equipment uptime. Suppliers that build application-specific engineering capabilities for these sectors can secure longer program cycles and more predictable demand. The upside is meaningful, but the downside risk is concentration risk: over-indexing on a single application without diversification can expose a supplier to cyclical downturns or technology substitution if alternative actuation methods gain traction.
Regional Assembly and Lead-Time Competition
Local assembly, modular ratio configuration, and regional distribution will become more important as buyers prioritize fast fulfillment and reduced supply chain uncertainty. The ability to deliver catalog ratios within short lead times is already reshaping purchasing expectations, and this pressure will likely intensify as automation programs accelerate and inventory strategies shift toward just-in-time readiness. Suppliers that establish regional assembly capability, standardize configurable product blocks, and maintain material consistency will be better positioned to capture demand in markets where delivery reliability equates to operational continuity. The associated risk is capital intensity and coordination complexity: regional capacity must be managed carefully to avoid fragmented production quality or excess inventory if demand forecasts shift.
决策者行动建议
Strategic choices in this market should be guided by the recognition that precision, delivery reliability, and application support are becoming as commercially significant as unit cost. The following recommendations are geared toward the main stakeholder groups evaluating exposure to high precision planetary gear reducers.
For Manufacturers and Product Companies
Engineer for application envelopes rather than generic catalogs. Prioritize thermal-stable backlash performance, modular ratio configurations, and documented validation evidence, because these attributes increasingly determine qualification success and pricing resilience. Invest in regional assembly or localized configuration capability where lead time expectations are compressing, and align material sourcing with consistent heat treatment and machining availability to protect quality at volume. Develop application-specific technical support that helps system integrators reduce integration risk, since post-sale engineering value is becoming a differentiator in multi-year automation deployments.
For Investors and Commercial Evaluators
Assess suppliers on verifiable precision capability, testing throughput, and regional delivery infrastructure rather than headline revenue alone. Favor companies that demonstrate modular product architecture, stable material supply, and the ability to shorten lead times for cataloged configurations, because these traits support margin stability and customer retention. Monitor application concentration as a risk indicator: businesses that are heavily dependent on a single sector should be evaluated against the potential for demand volatility or technology substitution, while diversified application portfolios typically offer more resilient growth profiles.
For Buyers and Procurement Teams
Shift evaluation criteria toward total cost of ownership, thermal-stable performance documentation, and delivery reliability. Request verification evidence under dynamic conditions, clarify ratio availability and lead-time expectations for cataloged configurations, and assess supplier capability to support integration with servo control architectures. Prioritize suppliers that can provide predictable delivery and application engineering assistance, because implementation risk and downtime avoidance often outweigh marginal unit price differences in precision automation programs.
For organizations seeking a deeper dive into segment-level sizing, regional dynamics, application demand curves, and competitive benchmarking, the full market research report provides detailed breakdowns and customized strategic recommendations that extend beyond the directional insights outlined here. Accessing that level of granularity can help align investment timing, product planning, and sourcing strategy with the specific demand drivers that will shape the next phase of market growth.
For detailed analysis of this topic, please visit the official page: High Precision Planetary Gear Reducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


