



Algae Products Market Surpasses $15B: 8.2% CAGR Trajectory and 3 Strategic Shifts

Strategic Horizons: Navigating Growth and Complexity in the Algae Products Market
1. Market Trajectory and Core Pressures
The global algae products market has entered a phase of accelerated expansion, driven by converging forces across nutrition, industrial sustainability, and biotechnological innovation. Valued at approximately $9,400 million in 2020, the sector has more than doubled in relative terms, reaching an estimated $15,151 million by 2025. Current projections indicate a steady growth trajectory through 2032, with a compound annual growth rate of 8.2 percent, positioning the market to approach $26.3 billion by the end of the forecast period. This expansion reflects a structural shift rather than a cyclical upturn, as algae-derived ingredients move from niche applications into mainstream dietary supplements, functional foods, animal nutrition, and industrial raw materials.
Worldwide Algal Biofuel Market
Despite the favorable trajectory, the industry stands at a critical juncture where scaling ambitions intersect with operational and regulatory realities. Three interlocking challenges define the current landscape. First, production scalability remains uneven across cultivation methods, with open-pond systems facing climate dependency and contamination risks, while closed photobioreactor and heterotrophic fermentation platforms demand significant capital investment and energy optimization. Second, regulatory scrutiny has intensified in key export markets, particularly around contaminant thresholds, strain-specific safety assessments, and novel-food categorization, raising compliance costs and lengthening time-to-market for new ingredients. Third, the supply chain for high-value fractions such as omega-3 oils, phycocyanin, and specialty proteins continues to experience bottlenecks in downstream processing, drying, and stabilization, which compress margins and limit format flexibility. These pressures are not insurmountable, but they require coordinated investment in process engineering, quality systems, and regional regulatory strategy.
2. Force Multipliers: What Is Driving the Market Forward
Technological Innovation and Strain-Level Breakthroughs
Advancements in cultivation architecture, strain selection, and downstream fractionation are reshaping the economics of algae production. Industry participants are increasingly pairing controlled-environment systems with real-time monitoring, automated feeding, and precision harvesting to improve yield consistency and reduce water and energy intensity. The integration of digital control systems into cultivation facilities has enabled tighter management of growth conditions, which is particularly valuable for high-potency extracts where potency, purity, and batch repeatability command premium pricing. Parallel progress in heterotrophic fermentation and metabolic engineering is expanding the range of commercially viable strains, allowing producers to decouple output from seasonal sunlight and weather variability. These developments are lowering the cost curve for specialized molecules while creating new format options for end users, from stabilized powders to concentrated oils and colorants.
Regulatory Evolution as a Market Catalyst
Regulatory dynamics in major markets are simultaneously tightening and enabling. In 2025, additional chlorella and spirulina strains received Generally Recognized as Safe status in the United States, broadening the formulation toolkit for supplement and food manufacturers. Around the same period, the European Food Safety Authority granted novel-food approvals for algae-derived omega-3 oils and phycocyanin colorants, opening doors for ingredient diversification in European markets. At the same time, both EFSA and the United States Pharmacopeia tightened contaminant thresholds for algae-based ingredients, elevating quality assurance expectations across the value chain. The net effect is a market that rewards disciplined producers with robust analytical capabilities, traceable sourcing, and documented process controls. Regulatory clarity, where it emerges, reduces uncertainty for downstream buyers and accelerates ingredient adoption, while stricter thresholds raise the competitive bar for entrants lacking validated quality infrastructure.
Demand-Side Shifts and Portfolio Reconfiguration
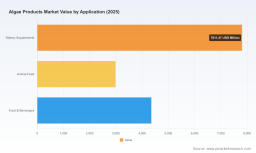
Consumer and corporate behavior is reordering ingredient preferences across multiple categories. Health-conscious consumers are increasingly seeking plant-based, ocean-friendly alternatives to fish-derived omega-3s, a trend that is expanding the addressable market for algal DHA and EPA oils in supplements, functional foods, and maternal nutrition. Beyond personal nutrition, manufacturers in food and beverage are exploring algae-derived proteins, colorants, and texturizing agents to support clean-label and sustainability claims. In animal nutrition, the push for alternative protein and lipid sources in aquaculture and livestock feed is creating incremental demand for algae-based meals and oils, particularly where feed conversion efficiency and disease resistance are priorities. These demand signals are not uniform, but they are broad enough to support diversified product strategies and reduce reliance on any single application vertical.
Supply Chain and Cost Structure Realignment
Cost competitiveness in the algae sector is increasingly determined by downstream efficiency and geographic positioning. Energy consumption, water management, harvesting yield, and drying technology are the primary levers that separate margin-resilient operations from those exposed to commodity volatility. Recent moves to localize cultivation and processing in regions with favorable climate, renewable energy access, and proximity to end markets are helping participants manage freight costs and reduce lead times. At the same time, partnerships between ingredient specialists and technology or agricultural partners are accelerating the commercialization of novel molecules, particularly astaxanthin and high-potency omega-3 fractions. Together, these shifts are turning cost structure from a static constraint into a dynamic design variable, where process choice, location, and collaboration model directly influence market positioning.
3. Competitive Dynamics and Strategic Positioning
The competitive landscape is characterized by a mix of established life-science and ingredients multinationals, specialized algae producers, and emerging technology-driven entrants. Market concentration is significant, with the top three players accounting for approximately 68 percent of revenue and the top five capturing roughly 82 percent, underscoring the advantage of scale, regulatory experience, and integrated supply chains. Yet the ecosystem also includes highly specialized firms that compete on potency, strain uniqueness, geographic sourcing, or application expertise, creating a layered market where leadership is defined as much by differentiation as by volume.
A review of recent corporate activity illustrates how participants are building durable advantage. In mid-2025, a leading algae-based omega-3 and specialty ingredients supplier secured regulatory approval in China for its algae-based omega-3 solutions, extending its commercial footprint into a high-growth market and strengthening its position in nutraceutical and food applications. Shortly thereafter, the same company partnered with an agricultural systems specialist to develop and commercialize natural astaxanthin derived from heterotrophic microalgae, signaling a deliberate expansion into high-value colorant and nutraceutical molecules through collaborative commercialization. In early 2025, a major spirulina producer inaugurated a new cultivation facility equipped with AI-enabled process control, SCADA monitoring, robotics, and zero-discharge systems, demonstrating how operational automation and environmental controls are being embedded into capacity expansion. In the second half of 2025, a prominent life-science and nutrition player launched an ultra-potent algal DHA oil formulation delivering substantially higher DHA and meaningful EPA levels per gram, targeting infant nutrition and premium supplement formats where concentration and dosage efficiency matter. Earlier, in late 2024, a collaborative product launch introduced microalgae-derived cooking oils produced via fermentation from sugarcane sugars, illustrating how alternative feedstock pathways and fermentation platforms are entering the consumer-facing food ingredient space.
Strategic Archetypes in the Market
These activities reveal several distinct strategic archetypes. One is the integrated multinational that leverages regulatory expertise, global distribution, and application support to dominate high-volume categories such as omega-3 oils and nutrition ingredients. Another is the specialist producer that competes on geographic origin, strain heritage, and purity narratives, often building loyalty through quality certification and category-specific formulation knowledge. A third is the technology-forward entrant that uses photobioreactors, fermentation, or advanced downstream processing to access molecules with superior potency, consistency, or cost profiles. Each archetype carries trade-offs: scale and integration support pricing power and market access, while specialization and technology intensity support margin resilience and differentiation but demand disciplined capital allocation and execution.
Evolution of the Competitive Map
Looking ahead, the market is likely to experience both consolidation and fragmentation simultaneously. Larger players will continue to pursue portfolio breadth, regulatory wins, and regional capacity to secure supply reliability for demanding buyers. At the same time, targeted partnerships and licensing arrangements will allow smaller or more specialized firms to commercialize novel molecules without bearing the full burden of standalone scale-up. New entrants with strong fermentation, strain engineering, or process automation capabilities may capture specific formulation niches, particularly where potency, sustainability, or clean-label positioning create meaningful price premiums. The net result is a market in which competitive advantage will increasingly depend on the ability to combine quality assurance, process efficiency, regulatory fluency, and application-specific value propositions rather than on volume alone.
PW Consulting Health Care Research Center
4. Forward Outlook: Trends Shaping the Next 3–5 Years
Three trends are likely to define the market’s evolution over the next several years. The first is the continued migration of algae-derived ingredients from specialty niches into mainstream nutrition and food formats. As regulatory approvals broaden and formulation know-how matures, algae-based omega-3s, proteins, colorants, and functional extracts will appear in more conventional product architectures, supported by consumer preference for plant-based and traceable inputs. The commercial opportunity here lies in format innovation and application engineering: products that deliver dosing convenience, sensory compatibility, and stability will gain shelf preference and retail traction.
The second trend is the growing importance of process intensity and digital control as margin determinants. Facilities that integrate automated cultivation management, precise harvesting, and energy-efficient drying will be better positioned to meet rising quality expectations while managing unit costs. Heterotrophic fermentation and hybrid cultivation models will expand where feedstock availability and process economics align, enabling more predictable output and reducing exposure to climate variability. For commercial teams, the implication is clear: sourcing decisions and partnership strategies should account for process transparency, quality documentation, and scalability pathways, not just current price points.
The third trend is regulatory normalization paired with higher compliance baselines. As more strains and ingredient categories secure approvals and contaminant thresholds become more stringent, the market will reward producers that demonstrate analytical rigor, batch traceability, and consistent documentation. This dynamic will raise barriers for low-cost, low-control operators while creating a more stable environment for established suppliers and well-capitalized newcomers. The associated risk is that compliance costs and approval timelines may compress short-term capacity additions, and that divergence in regional standards could complicate global supply strategies if not managed proactively.
5. Strategic Implications for Decision Makers
For manufacturers and ingredient developers, the priority is to align product roadmaps with where regulatory clarity, demand momentum, and process advantage intersect. This means prioritizing molecules and formats with clear adoption pathways, investing in quality systems and analytical capabilities that satisfy tightening contaminant thresholds, and selecting cultivation or fermentation models that match target margin profiles and volume requirements. Companies should also evaluate partnerships that can accelerate commercialization of high-value fractions, particularly where collaborative models reduce capital exposure while securing supply reliability.
For investors, the key is to distinguish durable advantage from short-term momentum. Favor platforms that combine regulatory track records, process automation, and defensible strain or formulation IP with evidence of scalable unit economics. Evaluate exposure to regional regulatory timelines and contaminant compliance costs, and assess whether a company’s competitive positioning depends on volume, potency, or differentiation. Diversification across applications can reduce concentration risk, but only when each vertical has a credible cost and quality story.
For procurement and formulation teams, the emphasis should be on supply resilience and specification integrity. Build multi-source strategies where feasible, prioritize suppliers with documented quality controls and robust traceability, and validate performance under real formulation conditions rather than relying on potency claims alone. As regulatory expectations rise and demand expands across food, supplement, and feed applications, procurement decisions that embed quality, compliance, and scalability considerations will reduce downstream disruption and support faster time-to-market.
As the market continues to scale, the difference between marginal participation and strategic advantage will increasingly come down to the precision of market intelligence. Detailed segmentation data, regional regulatory tracking, pricing and margin dynamics, and company-level capability assessments are essential inputs for capital allocation, partnership decisions, and formulation planning. Readers seeking deeper segmentation detail, regional demand patterns, and customized strategic recommendations can access the full research report for granular data and tailored guidance.
Microalgae Market
For detailed analysis of this topic, please visit the official page: Algae Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


