



NB Latex Market 2026-2032: Why 7.45% CAGR and the $215M 2025 Milestone Redefine Growth Dynamics

Navigating the NB Latex Market: Strategic Trends and Commercial Opportunities Through 2032
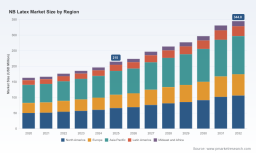
The NB Latex Market has matured from a commodity-driven segment into a strategically differentiated landscape where performance specifications, supply chain resilience, and regulatory compliance increasingly determine competitive advantage. Measured in 2025 at approximately USD 215.0 million, the market expanded at a compound annual rate of 7.45% between 2020 and 2025, and forward projections point to sustained momentum through the end of the decade. By 2032, total market size is expected to reach USD 344.8 million, reflecting a trajectory that rewards players capable of aligning product quality, geographic exposure, and operational efficiency with evolving demand patterns.
PW Consulting Health Care Research Center
This growth trajectory is not distributed uniformly. Demand pull comes from multiple end-use channels, while supply-side dynamics remain anchored in a concentrated group of processors and exporters with significant regional footprints. The intersection of tighter environmental regulation, shifting raw material economics, and product specialization is reshaping how value is captured across the chain. For executives and investors, the central question is no longer whether the market will grow, but where differentiation will emerge and how quickly operational models can adapt.
Market Context: Size, Trajectory, and Structural Pressures
A Market Defined by Steady Expansion and Fragmented Value Capture
The overall market has progressed from USD 163.15 million in 2020 to USD 215.0 million in 2025, with the pace of expansion accelerating in recent years as downstream applications broaden and higher-grade latex specifications gain acceptance. The forecast window to 2032 implies continued compounding, though the path will likely be uneven as raw material volatility, regulatory deadlines, and regional demand cycles introduce periodic adjustments. A top-line CAGR of 7.45% signals healthy underlying demand, but it also raises the bar for operational execution, since margin capture increasingly depends on grade consistency, certification readiness, and logistics optimization rather than volume alone.
The value chain remains moderately concentrated. The top three participants account for roughly 23.5% of market revenue, and the top five collectively represent about 28.7%. This structure suggests room for competitive maneuvering, particularly for mid-tier processors that can secure reliable feedstock, differentiate on specialty grades, or embed themselves in customer-specific supply programs. At the same time, the presence of larger, vertically integrated operators indicates that scale advantages in processing capacity, quality control, and export logistics will continue to matter.
Worldwide Latex Binders Market
Key Challenges and Inflection Points
Several structural pressures are redefining the operating environment. First, compliance costs and traceability requirements are rising. The European Union Deforestation Regulation requires operators and traders placing natural rubber latex or products containing it on the EU market to provide geolocation data up to the plantation level for compliance. Enforcement timelines have been adjusted, with large and medium operators facing a December 2026 deadline and micro and small operators a June 2027 deadline following changes made in December 2025. This creates a near-term implementation squeeze: companies must build or verify plantation-level traceability, document chain-of-custody processes, and stand ready for customer and regulator scrutiny without derailing existing export flows.
Second, raw material economics are under continuous renegotiation. Price signals in related commodity markets can influence input cost expectations and plantation economics. For example, palm oil prices fell to 4,554 MYR/T on June 5, 2026, down 1.02% from the previous day, while rising 0.60% over the past month and 16.26% compared to the same time last year. Such movements illustrate how agricultural commodity markets can oscillate within short windows, affecting cost planning and hedging strategies for processors that operate around interlinked feedstock ecosystems. In a related policy move, Indonesia raised the export duty on crude palm oil from 10% to 12.5% starting March 1, 2026, directly increasing production costs for palm oil producers. Although this measure targets palm oil, it reflects a broader pattern of export-duty adjustments in producing countries that can indirectly shape cost structures, trade flows, and regional competitiveness for processors handling multiple agricultural streams.
Third, demand-side expectations are shifting from volume to performance. Buyers increasingly seek latex grades that meet tighter technical specifications, consistent viscosity and purity profiles, and certifications aligned with downstream manufacturing requirements. This creates a divide between suppliers that can reliably deliver standardized, certified products and those that remain dependent on more variable commodity streams. The market is therefore approaching an inflection point where quality assurance and documentation capabilities are becoming as commercially significant as capacity.
Key Drivers Shaping the NB Latex Market
Technical Innovation and Grade Specialization
Innovation in latex processing is increasingly oriented around consistency, contamination control, and specification alignment. For automotive and industrial users, tighter tolerances and dependable lot-to-lot performance reduce downstream processing risk and support broader use in higher-value applications. Suppliers with strong process control, filtration and stabilization capabilities, and quality-certified grades are better positioned to serve customers that require repeatable input characteristics. In practical terms, innovation here is less about radical product reinvention and more about process refinement, analytical rigor, and the ability to package reliability as a commercial differentiator.
This trend benefits processors that can demonstrate controlled parameters and certified output. It also raises the importance of technical service: customers are more likely to commit to suppliers who can support specification matching, troubleshooting, and supply continuity. As a result, the competitive edge is shifting toward organizations that combine operational discipline with application-aware customer engagement.
Policy and Regulatory Environment
Regulatory developments are emerging as a structural driver rather than a peripheral compliance issue. The EU Deforestation Regulation is a prominent example: it requires operators and traders placing natural rubber latex or products containing it on the EU market to provide geolocation data up to the plantation level for compliance. The enforcement timeline has been postponed to 30 December 2026 for large and medium operators and to 30 June 2027 for micro and small operators following December 2025 changes. While the postponement provides additional preparation time, the direction of travel is clear: traceability and geolocation documentation are becoming prerequisites for continued access to European channels.
For exporters and processors, the practical implication is that compliance readiness will increasingly influence market access, buyer selection, and contract negotiation dynamics. Companies that invest early in mapping plantation sources, strengthening documentation, and aligning internal processes with geolocation requirements will be better placed to maintain relationships with customers that prioritize regulatory assurance. Those that delay could face higher transaction costs, reduced optionality, or exclusion from certain procurement programs.
Demand-Side Evolution Across End-Use Segments
Demand is broadening beyond traditional channels, and the composition of growth is changing. Automotive applications remain a significant pull, supported by tire and component requirements that favor reliable natural rubber latex inputs. Construction and building materials, consumer goods and personal care, industrial products, and other segments each contribute to aggregate demand in different ways, with varying sensitivity to price, specification, and certification. What matters strategically is that downstream industries are not moving in lockstep. Some channels prioritize cost efficiency, while others place greater weight on performance consistency or compliance documentation.
This segmentation of demand means suppliers need flexible commercial models. A single product strategy is less effective when customers in different verticals evaluate trade-offs differently. Processors that can offer multiple grade options, maintain clear segregation of volumes by specification, and align supply with customer-specific requirements are more likely to retain share as demand patterns shift. The ability to anticipate which segments will expand faster, and to align capacity and certifications accordingly, will be a meaningful source of advantage.
Supply Chain and Cost Structure Dynamics
Cost structures in the NB Latex Market are shaped by feedstock availability, processing efficiency, logistics, and the broader policy environment in producing regions. Price signals from commodity markets can influence planning horizons and risk management decisions. The recent movement in palm oil prices illustrates the kind of volatility that processors may observe in adjacent agricultural markets, with short-term declines coexisting alongside stronger year-on-year comparisons. On the policy side, Indonesia raised the export duty on crude palm oil from 10% to 12.5% starting March 1, 2026, directly increasing production costs for palm oil producers. Such measures matter because they reflect a recurring theme: producing countries periodically adjust export duties and related fiscal instruments, which can alter cost competitiveness and trade routing over time.
At the same time, supply tightness in major producing countries continues to influence pricing expectations. The World Bank projected Technically Specified Rubber 20 natural rubber prices to increase approximately 7.3% in 2026 to around USD 1.90 per kilogram, supported by steady automotive-sector demand growth and ongoing supply tightness across major producing countries. This outlook underscores that feedstock economics will remain an important variable for latex processors, particularly where natural rubber is a central input. Companies that can manage procurement risk, secure dependable supply, and optimize processing yields will be better equipped to navigate price fluctuations without sacrificing margin stability.
Competitive Landscape: Positioning, Differentiation, and Evolution
Core Players and Strategic Positioning
The competitive set is anchored by processors and exporters with significant capacity and regional reach, many based in Thailand and neighboring Southeast Asian markets, alongside integrated traders and producers in broader Asian supply chains. Several companies stand out for the way they combine capacity, grade focus, and supply chain positioning.
Latex Powder Market
- Sri Trang Agro-Industry Public Company Limited operates as a leading producer and exporter of natural rubber latex concentrate, with global processing capacity exceeding 1.5 million tonnes per year and about 10% share of global natural rubber consumption. Its scale and market participation give it a strong base for volume reliability and broad customer coverage.
- Von Bundit Co., Ltd. is a major processor and exporter of natural rubber latex with production capacity of approximately 2 million tonnes per annum and emphasis on quality-certified grades. This positions the company around specification reliability and certified output, which aligns with buyers seeking consistent input quality.
- Halcyon Agri Corporation Limited is an integrated producer and processor of natural rubber latex serving tire, glove, and industrial applications with vertical supply chain control. Vertical integration can reduce dependency on external procurement channels and support more controlled feedstock and processing flows.
- Thai Rubber Latex Group Public Company Limited supplies concentrated and creamed natural rubber latex with focus on export volumes to Malaysia, China, and other markets. Its export-oriented profile highlights the importance of logistics, destination-market relationships, and trade routing.
- Southland Rubber Co., Ltd. processes natural rubber latex and solid rubber products with capabilities in specialty grades for healthcare and industrial uses. Specialty-grade capability is a notable differentiator in segments where regulated or performance-sensitive applications matter.
- Thai Hua Rubber Public Company Limited is a major player in concentrated natural rubber latex production and export from Thai plantations. Its positioning reflects the continuing importance of Thailand as a processing and export hub.
- Vietnam Rubber Group is a state-linked producer and exporter of natural rubber latex concentrate with significant share in Southeast Asian supply. Its role illustrates how national-level institutions can influence regional supply dynamics and export availability.
- Sinochem International Corporation is an integrated trader and processor supplying natural rubber latex to global markets. Trade and processing integration can support broad market reach and flexible supply arrangements.
- Num Rubber & Latex Co., Ltd. is an active manufacturer of natural rubber latex products and concentrates for medical and industrial applications. Its focus on medical and industrial segments points to the value of application-specific product development and certification readiness.
- Apcotex Industries Limited is a supplier of natural rubber latex for adhesive, coating, and industrial applications. This specialization highlights demand from industrial formulation uses where latex properties influence end-product performance.
Differentiation Themes Among Leading Players
Across this group, several differentiation themes recur. Scale and processing capacity provide volume reliability and the ability to serve large, multi-site customers. Quality-certified grades and specialty offerings support access to more demanding applications, where specification adherence and documentation are critical. Vertical supply chain control and integration can improve feedstock security and reduce exposure to intermediate market disruptions. Export orientation and destination-market relationships shape commercial reach, especially where logistics, customs coordination, and customer proximity influence service levels. Application-specific focus, whether in healthcare, industrial formulation, tire-related uses, or consumer-adjacent products, allows suppliers to build deeper relationships and more tailored value propositions.
The strategic implication is that no single advantage is sufficient on its own. Capacity without quality control limits access to premium channels. Quality and certification without reliable supply can undermine customer confidence. Export relationships without compliance readiness become riskier as regulatory expectations rise. The strongest positions tend to combine several of these elements in a coherent operating model.
Market Structure Evolution: Consolidation, Diversification, and New Entry
The market is likely to evolve through a combination of consolidation among scaled processors, diversification into higher-value grades and applications, and selective new entry where niche positioning or regional advantages are strong. Moderate concentration leaves space for competitive shifts, but it also encourages larger players to deepen customer commitments, strengthen traceability, and invest in process consistency. Mid-tier participants may pursue specialization, regional partnerships, or certification-driven differentiation to expand their addressable market without competing purely on volume.
New entry is most plausible where companies can demonstrate a clear value proposition: reliable traceability, specialty-grade capability, cost-efficient processing, or access to underserved destination markets. In contrast, entry that relies only on commodity positioning is harder to sustain as buyers increasingly weigh specification reliability and compliance assurance alongside price. Over time, the landscape may become more layered, with premium, certified, and application-specific segments becoming more distinct from standard commodity-grade channels.
Outlook: Three Strategic Trends to 2032
Trend 1: Compliance and Traceability as Commercial Gatekeepers
Traceability and geolocation readiness will increasingly function as commercial gatekeepers for access to regulated markets. The EU Deforestation Regulation requires operators and traders placing natural rubber latex or products containing it on the EU market to provide geolocation data up to the plantation level for compliance, and the adjusted enforcement schedule still places large and medium operators under a December 2026 deadline and smaller operators under a June 2027 deadline. This timeline creates a practical window for preparation, but it also raises the likelihood that compliance maturity will influence buyer decisions and contract eligibility.
The commercial opportunity lies in turning compliance into a differentiator. Suppliers that can present verifiable plantation-level data, robust documentation, and repeatable audit readiness may find it easier to enter or retain relationships with customers that require regulatory assurance. The risk is that companies with weak traceability infrastructure face growing friction, higher transaction costs, or narrowing market access, especially in channels where buyers are especially sensitive to regulatory exposure.
Trend 2: Grade Specialization and Specification-Driven Demand
Demand is expected to place greater weight on specification consistency, certified grades, and application-aligned product attributes. Automotive and industrial channels, in particular, benefit from latex inputs that support stable downstream processing and predictable performance. This favors processors that can maintain tight control over quality parameters and deliver certified output with dependable lot consistency.
For commercial strategy, this trend suggests a shift toward value-based positioning rather than price-only competition. Companies that can match grades to customer requirements, provide technical support, and ensure supply continuity may command stronger relationships and better margin protection. The uncertainty is that specification demands may diverge across segments, requiring suppliers to manage a broader set of product configurations without losing operational efficiency.
Trend 3: Supply-Side Volatility and the Need for Procurement Resilience
Feedstock economics and policy adjustments will continue to shape cost structures and supply planning. With natural rubber prices projected to increase approximately 7.3% in 2026 to around USD 1.90 per kilogram, supported by steady automotive-sector demand growth and ongoing supply tightness across major producing countries, processors should expect continued pressure on input economics. At the same time, policy actions such as Indonesia raising the export duty on crude palm oil from 10% to 12.5% starting March 1, 2026, and short-term commodity price movements like palm oil falling to 4,554 MYR/T on June 5, 2026, illustrate how quickly cost expectations can shift in adjacent agricultural markets.
The strategic response is to build procurement resilience: diversified sourcing where feasible, stronger supplier relationships, improved yield and process efficiency, and disciplined risk management. The opportunity is to reduce vulnerability to price spikes and supply interruptions while maintaining competitive pricing for customers. The risk is that firms with limited flexibility may face margin compression or supply uncertainty when markets tighten or policy changes alter cost dynamics.
Actionable Recommendations for Decision-Makers
For Manufacturers and Processors
Invest early in traceability and documentation infrastructure, especially if European market access is part of the commercial plan. Plantation-level geolocation readiness, chain-of-custody records, and auditable process controls will become more valuable as deadlines approach and buyer expectations firm up. At the same time, review grade architecture and quality systems to ensure the product mix supports specification-driven demand. Where possible, strengthen process consistency and certification readiness so the business can serve higher-value applications without compromising reliability.
For Investors
Look beyond aggregate market size and focus on the structural attributes that determine durable value capture. Scale, vertical integration, certification capability, specialty-grade positioning, and compliance readiness each influence competitive resilience in different ways. Evaluate whether target companies have credible pathways to maintain supply security, meet rising traceability expectations, and serve demand channels that are expanding faster than the average. Pay attention to regional exposure and policy risk, since export-duty changes and commodity price volatility can affect cost structures and trade routing over time.
For Procurement and Supply Chain Leaders
Treat latex sourcing as a multi-factor decision rather than a price-only exercise. Specification consistency, certification status, traceability readiness, and supply continuity should be weighted alongside cost, particularly where downstream manufacturing risk or regulatory exposure is significant. Diversify sourcing where feasible, clarify documentation requirements with suppliers, and establish expectations for geolocation and compliance data if EU-market-bound products are in scope. Building these expectations into procurement criteria early can reduce disruption later and improve negotiating leverage.
The NB Latex Market is entering a phase in which growth is necessary but not sufficient. The companies and investors that fare best will be those that treat compliance readiness, grade specialization, and supply resilience as core strategic capabilities rather than operational afterthoughts. Detailed segmentation data, company-level benchmarks, and scenario-based guidance can help convert these strategic themes into specific investment, sourcing, and product decisions. Readers seeking a more granular view of regional splits, application dynamics, type-level comparisons, and competitive positioning can access the full PW Consulting report for detailed figures and customized recommendations tailored to their commercial objectives.
For detailed analysis of this topic, please visit the official page: NB Latex Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


