



Micro-Lens Arrays Market: 6.49% CAGR to $344.8M By 2032

Micro-Lens Arrays Market: Strategic Trends and Commercial Opportunities Beyond 2030
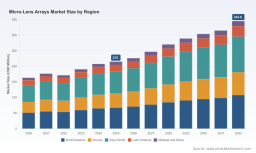
The global micro-lens array (MLA) market has matured into a strategically vital component of modern optical systems, driven by the convergence of photonics innovation, automotive electrification, and high-bandwidth data infrastructure. From 2020 through 2025, the sector expanded from approximately USD 163 million to an estimated USD 215 million, reflecting a compound annual growth rate (CAGR) of 6.49% across the forecast horizon extending to 2032. This trajectory is not merely a function of incremental demand; it signals a structural shift in how precision optics are integrated across telecommunications, advanced driver-assistance systems, medical imaging, and next-generation energy modules. As the market approaches a projected valuation exceeding USD 340 million by 2032, executives and investors must navigate a landscape where technological differentiation, supply chain resilience, and regulatory volatility intersect.
PW Consulting
Market Snapshot: Scale, Structure, and Hidden Pressures
The MLA ecosystem has transitioned from a niche photonics supplier to a foundational enabler of high-value optical architectures. Historical revenue patterns reveal a market that experienced a brief contraction in 2022, followed by a robust rebound and sustained expansion through 2025. This correction was temporary but instructive: it exposed the fragility of highly optimized, geographically concentrated supply chains when confronted with raw material constraints and sudden trade policy shifts. By 2025, the market's recovery and upward momentum underscore a broader reality—demand for micro-optical components is no longer cyclical; it is structurally embedded in multiple high-growth verticals.
Worldwide Microdisplay Spatial Light Modulators Market
Several structural pressures are reshaping how manufacturers, buyers, and capital allocators approach the space. First, precision fabrication requirements have tightened tolerances across pitch accuracy, surface quality, and coupling efficiency, elevating process control costs and extending lead times. Second, raw material dynamics have introduced periodic volatility, particularly for specialty optical glasses doped with rare-earth elements, where sourcing bottlenecks can quickly translate into pricing adjustments. Third, regulatory interventions in major consumer markets have recalibrated procurement strategies, compelling buyers and producers alike to reconsider geographic sourcing, inventory buffering, and localized production pathways. These pressures are not isolated disruptions; they are becoming baseline considerations in strategic planning.
Key Drivers Reshaping the Micro-Lens Arrays Landscape
Technological Innovation and Process Maturation
The acceleration of co-packaged optics (CPO), silicon photonics integration, and high-density fiber coupling has elevated MLAs from passive optical elements to active performance determinants. Fabricators are increasingly deploying wafer-level imprint lithography, two-photon polymerization, and hybrid glass-composite molding to achieve freeform, aspherical, and sub-micron pitch architectures. These process advances enable tighter beam shaping, improved homogenization, and higher coupling efficiency in telecom and datacom environments. At the same time, additive microfabrication techniques are unlocking complex geometries that were previously cost-prohibitive, expanding the design space for machine vision, laser systems, and compact medical optics. The commercial implication is clear: vendors that can translate fabrication agility into repeatable, high-yield production gain a measurable edge in qualification cycles and customer retention.
Policy and Regulatory Realignment
Trade policy adjustments in the United States during 2025 introduced additional duties on imported fused silica substrates and finished microlens arrays, directly altering cost structures and procurement timelines. Rather than treating these measures as transient friction, leading organizations are recalibrating sourcing architectures to reduce exposure to single-point customs risk. This has spurred incremental investments in localized manufacturing, dual-sourcing arrangements, and qualification of alternative substrate materials. Regulatory shifts of this nature typically accelerate supplier consolidation among entities with established compliance infrastructure, while simultaneously opening opportunities for regional producers capable of meeting technical specifications without compromising lead times.
Demand-Side Evolution in End-Use Verticals
Demand momentum is increasingly dictated by application adoption curves rather than broad macroeconomic indicators. In telecommunications and IT infrastructure, the push toward higher bandwidth, lower latency, and integrated optical interconnects continues to drive MLA utilization in fiber coupling and light management. Automotive applications are expanding as advanced lighting architectures, sensing modules, and in-vehicle optical systems require compact, reliable micro-optics that can withstand harsh environmental conditions and meet stringent quality standards. Medical imaging, diagnostic devices, and specialized laser systems contribute a steady, high-value demand stream where precision and repeatability outweigh cost sensitivity. Concurrently, solar module optimization and auxiliary optical applications provide incremental volume that supports capacity utilization. For commercial leaders, the strategic takeaway is to align product roadmaps with the qualification rhythms and technical thresholds of these verticals, rather than competing solely on price in commoditized segments.
Supply Chain and Cost Structure Realities
Precision manufacturing of MLAs remains labor- and process-intensive. High-precision polishing, alignment, and metrology contribute to elevated unit economics, particularly as volumes scale and tolerance requirements tighten. Material supply concentration in select regions for high-grade optical glass introduces vulnerability to geopolitical friction, export control expansions, and localized disruptions. These structural characteristics mean that lead-time reliability, quality consistency, and technical support often carry as much commercial weight as baseline pricing. Organizations that invest in process stabilization, qualification transparency, and resilient material sourcing are better positioned to convert technical capability into sustained contract wins and reduced negotiation friction.
Competitive Landscape: Positioning, Differentiation, and Evolution
The MLA market remains moderately concentrated, with the top three participants collectively accounting for just under a quarter of total revenue and the top five holding a slightly larger share. This fragmentation reflects a market where technical specialization, application-specific qualification, and regional servicing capabilities often matter more than scale alone. Several established players illustrate distinct strategic archetypes that define current competitive dynamics.
Glass-focused fabricators have built reputations around high-precision glass microfabrication, molding, and composite technologies, targeting applications such as CPO, digital imaging, high-brightness LEDs, and OLED architectures. Their differentiation typically hinges on material consistency, yield stability, and deep process know-how in glass-based optics. Custom photonics specialists, by contrast, emphasize design flexibility and rapid iteration, offering dedicated engineering services that help customers translate optical concepts into manufacturable MLA devices. This service-led model supports next-generation photonics development and positions the supplier as a design partner rather than a pure component vendor.
Wafer-scale manufacturers operating on 150mm and 150mm-class platforms serve telecom, datacom, automotive, and consumer segments with a focus on pitch accuracy and coupling efficiency. Their competitive strength lies in standardized substrate handling, repeatable wafer-level processes, and qualification pathways aligned with automotive and semiconductor expectations. Meanwhile, additive microfabrication providers leverage two-photon polymerization to deliver freeform and hybrid micro-optics on fibers and chips, targeting complex geometries and rapid prototyping cycles that conventional lithography cannot easily accommodate. Imprint lithography specialists contribute wafer-level MLAs suited for automotive lighting, fiber coupling, photonic integrated circuits, and semiconductor applications, with quality systems aligned to automotive production standards.
Other participants differentiate through material selection and application focus. Some offer high-grade fused silica arrays with spheric, aspheric, or freeform profiles tailored for fiber coupling, while others emphasize precision polishing and alignment for machine vision, laser systems, and optical sensing. PMMA-based arrays remain relevant for light homogenization and shaping in research, instrumentation, and industrial settings where cost and ease of integration are prioritized. Across these profiles, the common thread is application alignment: vendors that embed their technical strengths within the qualification and performance requirements of specific use cases tend to secure more durable demand.
The competitive trajectory is moving toward selective consolidation and parallel specialization. Larger optical and materials groups are exploring targeted acquisitions or partnerships to broaden substrate capabilities, strengthen regional service coverage, and accelerate qualification in regulated verticals. At the same time, new entrants with advanced fabrication methods or niche design expertise continue to fragment the market at the high-value end, particularly where freeform design, hybrid materials, or custom photonics services create Defensible differentiation. The net effect is a landscape where broad commoditization is limited; value accrues to organizations that can combine technical precision, application understanding, and supply chain reliability.
Optical Lenses Market
Commercial Implications of the Competitive Shift
- Technical service and design engagement are becoming as important as component pricing, especially for customers developing next-generation optical architectures.
- Regional qualification and compliance readiness increasingly influence sourcing decisions, particularly in automotive and telecom environments.
- Substrate availability and material continuity are emerging as deal-critical factors, elevating the strategic importance of diversified sourcing and inventory planning.
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend 1: Integration-Driven Demand in High-Bandwidth Optical Architectures
As co-packaged optics and photonic integration gain traction in datacom and telecom deployments, MLAs will be evaluated less as standalone components and more as integrated elements within broader optical subsystems. This shift favors suppliers who can support system-level design considerations, including alignment tolerances, thermal stability, and coupling efficiency under realistic operating conditions. The opportunity lies in offering qualified, repeatable MLAs that reduce integration risk for system designers, while the risk is that pricing pressure intensifies if specifications become standardized across multiple vendors.
Trend 2: Regionalization of Sourcing and Manufacturing Capability
tariff measures and raw material concentration risks are accelerating a broader move toward localized production, dual sourcing, and qualification of alternative supply bases. Over the next several years, this is likely to produce a more geographically diversified supplier base for fused silica and specialty glass MLAs, with regional hubs emerging to serve nearby automotive, medical, and industrial customers. The upside is improved lead-time predictability and reduced customs exposure; the downside is that firms without capital to invest in localized capacity or qualification infrastructure may face margin compression or exclusion from preferred supplier lists.
Trend 3: Advanced Fabrication Methods Opening High-Value Niches
Additive microfabrication, imprint lithography, and hybrid molding are expanding the feasible design space for freeform, hybrid, and complex micro-optics. These methods create openings in custom photonics, compact sensing, and specialized imaging applications where performance requirements cannot be met by conventional arrays. The commercial benefit is access to higher-margin, application-specific work; the risk is that process scalability and cost control remain challenging, potentially limiting volume growth if demand stays fragmented across many small programs.
Associated Risks and Uncertainties
- Raw material availability for rare-earth-doped optical glasses may continue to create periodic cost and lead-time volatility during demand spikes.
- Regulatory frameworks can shift quickly, altering the relative attractiveness of different sourcing routes and requiring continuous supply chain reassessment.
- Labor intensity in high-precision polishing and alignment may sustain elevated unit economics, limiting the pace at which cost reductions can be passed through to customers.
- Geopolitical disruptions or export control expansions could disproportionately affect supply chains with concentrated production in a small number of regions.
Strategic Actions for Decision Makers
For Manufacturers and Technology Providers
Prioritize process stabilization and qualification transparency in the segments where you intend to compete. In automotive and telecom environments, documentation, repeatability, and compliance readiness often determine supplier selection as much as baseline performance. Evaluate whether to deepen specialization in a high-value niche—such as custom photonics design, freeform micro-optics, or wafer-level automotive lighting—or to expand substrate and material options to reduce concentration risk. Where feasible, develop dual-sourcing strategies for critical raw materials and consider regional capacity or partnerships that shorten lead times for nearby customer bases.
For Investors and Capital Allocators
Focus diligence on differentiation durability rather than headline growth alone. The most resilient opportunities typically combine technical moats, application-specific qualification, and supply chain resilience. Assess whether target companies have clear pathways to scale without sacrificing quality, whether their customer base is diversified across multiple verticals or overly dependent on a single program cycle, and whether they have responded to recent trade and material dynamics with actionable sourcing or capacity strategies. In a moderately concentrated market, value creation often comes from firms that can convert specialized capability into recurring, qualified demand rather than from broad-based volume plays.
For Procurement and Engineering Leaders
Treat MLA sourcing as a systems-integration decision rather than a commodity purchase. Align specifications with actual performance needs, qualify alternative substrates and suppliers where feasible, and build buffer strategies for materials with known concentration risk. Engage suppliers early on design-for-manufacturability and qualification timelines to reduce downstream rework and schedule risk. Where application requirements permit, balance precision requirements against cost by selecting the simplest architecture that meets system performance targets, reserving high-complexity freeform or hybrid designs for cases where they deliver measurable system-level benefits.
The micro-lens arrays market is entering a phase where technical capability, supply chain resilience, and application alignment determine commercial outcomes more than volume alone. Decision makers who map their strategies to these structural dynamics will be better positioned to capture high-value demand while navigating material, regulatory, and process uncertainties. For organizations seeking detailed segmentation data, regional demand patterns, and tailored recommendations aligned to specific product portfolios or investment theses, the full PW Consulting research report provides the deeper quantitative and qualitative detail needed to translate these trends into concrete action.
For detailed analysis of this topic, please visit the official page: Micro-Lens Arrays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


