



Print Quality Inspection System Market: Why 5.8% CAGR and $300M Expansion Reshape Production

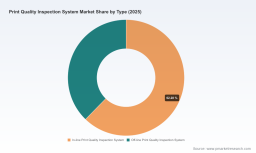
The Print Quality Inspection System Market: Navigating Strategic Shifts and Commercial Opportunities
The global landscape for print quality inspection systems is undergoing a structural transformation. What was once a niche segment focused on routine defect detection has evolved into a critical infrastructure layer for manufacturing industries where visual fidelity, regulatory compliance, and production efficiency intersect. The market has demonstrated steady expansion over the past half-decade, with revenue climbing from approximately USD 148.5 million in 2020 to USD 201.5 million in 2025. Projections through 2032 indicate continued growth, reaching an estimated USD 300.0 million by the end of the forecast period, supported by a compound annual growth rate of 5.8 percent. This trajectory reflects more than incremental demand; it signals a fundamental reassessment of how manufacturers approach quality assurance in an era defined by tighter regulatory frameworks, rising labor costs, and accelerating automation adoption.
Yet the growth narrative is not uniform across all segments or regions. The market remains moderately fragmented, with the top three players capturing roughly 24.6 percent of total revenue and the top five accounting for approximately 26.2 percent. Such concentration levels suggest a competitive environment where established incumbents hold meaningful advantages in brand recognition, installed base, and technical maturity, but where room exists for differentiated newcomers and niche specialists to carve out defensible positions. The following sections dissect the forces shaping this market, the competitive dynamics at play, and the strategic implications for executives navigating procurement decisions, investment allocations, and product development roadmaps.
Market Structure and the Current Growth Trajectory
The print quality inspection system market has expanded consistently since 2020, with each year underscoring a broader industrial shift toward automated visual verification. Revenue growth between 2023 and 2024, for instance, reflected a notable step change as manufacturers accelerated deployment of inspection hardware on high-speed production lines. By 2025, the market had surpassed the USD 200 million threshold, and forward estimates suggest that annual revenue will continue climbing at a pace that outstrips general manufacturing equipment growth rates. This expansion is not merely a function of unit sales; it is increasingly tied to the value of integrated software, cloud-enabled workflows, and AI-driven defect classification, which together elevate the total cost of ownership and lifetime value of each installation.
Geographically, the market exhibits a multi-polar distribution rather than reliance on a single dominant region. North America, Europe, and Asia Pacific each represent substantial revenue pools, reflecting the widespread adoption of inspection systems across packaging, pharmaceutical labeling, and consumer goods manufacturing. Emerging regions such as Latin America and the Middle East and Africa contribute smaller but growing shares, often driven by localized packaging investments and the gradual modernization of legacy production lines. The geographic spread indicates that demand is not confined to mature industrial economies; rather, it is spreading as manufacturing capabilities and regulatory expectations mature across diverse markets.
Key Challenges and Inflection Points
Despite the favorable growth backdrop, the market faces several friction points that will determine which participants capture disproportionate value over the next five to seven years.
First, the transition from traditional rule-based inspection to AI-enhanced defect recognition remains uneven. While the technology promise is clear, manufacturers must weigh the upfront integration complexity against incremental yield improvements. Legacy systems often rely on fixed thresholds and manual calibration, which limits adaptability to shifting substrates, ink formulations, or packaging designs. Upgrading to systems capable of learning from production variability requires not only hardware refresh but also data infrastructure, operator training, and sustained model maintenance. This creates a barrier for mid-sized producers who may lack the internal engineering capacity to manage algorithmic lifecycle management.
Second, regulatory pressure is intensifying the stakes for inspection accuracy, particularly in sectors where visual defects carry compliance or safety implications. In pharmaceutical and medical packaging, print quality is not merely a cosmetic concern; it is tied to traceability, dosage clarity, and patient safety. Recent regulatory updates, including the Quality Management System Regulation that took effect in early 2026 and incorporated ISO 13485:2016 principles, have tightened quality management expectations for device manufacturers. These changes increase the value of inspection systems that can provide auditable records, consistent defect classification, and integration with broader quality management workflows. At the same time, they raise the compliance burden for suppliers who must demonstrate that their inspection solutions meet evolving standards across multiple jurisdictions.
Third, capital intensity and infrastructure requirements constrain adoption in certain deployment contexts. High-speed line scan imaging modules, specialized illumination, and integration with existing web or sheet-fed lines represent significant investment. For some producers, the decision to deploy a comprehensive inspection system competes with other capital priorities, especially when labor shortages are not yet acute enough to force automation. Industry data points to rising labor constraints in manufacturing as a broader catalyst for inspection adoption, but the translation of labor pressure into procurement decisions varies by region, sector, and company size. This creates a bifurcated market where large, efficiency-focused operators move quickly while smaller or margin-constrained players lag.
Core Drivers Shaping the Market
The sustained expansion of the print quality inspection system market is propelled by a convergence of technological, regulatory, and operational forces. Understanding these drivers in isolation is useful; understanding their interaction is essential for strategic planning.
Technological Innovation and the AI Transition
The most consequential shift in the market is the integration of machine vision and AI-based defect detection into inspection workflows. Vendors are increasingly offering systems that combine high-resolution imaging with algorithmic classification, enabling real-time identification of misregistration, color deviation, foreign material, and substrate defects. This evolution addresses a long-standing limitation of earlier inspection approaches: the reliance on static defect libraries that struggle to adapt to new packaging formats or variable production conditions. AI-enhanced systems can reduce false rejects, improve line throughput, and provide richer data outputs that feed into downstream quality analytics.
Product launches and software releases over recent years illustrate how vendors are translating this technological trajectory into commercial offerings. One notable example is the introduction of an AI-powered inspection platform designed for high-speed printing and packaging environments, which emphasizes automated visual quality control and defect detection at production speeds. Another significant development is the release of cloud-based prepress inspection software that operates independently of specific hardware configurations, reflecting a broader industry move toward software-centric value addition. These releases signal that competitive differentiation is increasingly determined by software ecosystems, data portability, and the ability to integrate with prepress, production, and quality management systems rather than by imaging hardware alone.
Regulatory and Compliance Pressures
Regulatory expectations are reinforcing demand for inspection systems that deliver consistency, traceability, and audit readiness. Quality management standards such as ISO 9001:2015 serve as foundational references for inspection workflows across global manufacturing, while sector-specific requirements add further layers of complexity. In pharmaceutical and medical packaging, inspection systems must align with standards enforced by regulatory bodies such as the FDA and EMA, ensuring that print quality supports broader compliance obligations. The recent amendment of device current good manufacturing practice requirements through the Quality Management System Regulation exemplifies how regulatory updates can directly influence procurement priorities by raising the bar for documented quality control and process verification.
For manufacturers operating in regulated environments, the commercial case for advanced inspection systems is strengthened by the potential to reduce compliance risk, streamline audit preparation, and standardize defect documentation across lines and sites. This dynamic is particularly relevant for multinational producers who must maintain consistent quality standards across diverse regulatory regimes. Inspection systems that offer configurable rule sets, robust data logging, and integration with quality management platforms are better positioned to meet these demands than standalone defect detection tools.
Demand-Side Shifts in Packaging and Labeling
Consumer expectations and retail dynamics are reshaping the packaging and labeling sector in ways that indirectly elevate the importance of print quality inspection. Brands are increasingly reliant on packaging as a primary engagement channel, which raises the visibility of print defects and the reputational cost of quality failures. At the same time, the proliferation of short-run packaging, variable data printing, and customized labeling increases production variability, making manual inspection less scalable and more error-prone. In food and beverage, consumer goods, and medical packaging, the combination of higher quality expectations and more heterogeneous production runs drives demand for inspection systems that can maintain accuracy across frequent changeovers.
Worldwide Thermal Warpage Inspection System Market
This demand-side evolution also intersects with operational efficiency goals. As manufacturers seek to minimize waste, reduce rework, and improve first-pass yield, inspection systems function as both a quality gate and a productivity enabler. Real-time defect detection allows operators to intervene before defective material proceeds further down the line, reducing material loss and downstream sorting costs. In high-volume environments, even small improvements in defect capture rates can translate into meaningful savings over time, strengthening the return case for inspection investments.
Supply Chain and Cost Structure Considerations
The cost structure surrounding print quality inspection systems is influenced by component availability, integration complexity, and the broader economics of high-speed imaging hardware. Capital equipment costs and infrastructure investments for advanced line scan modules represent a notable deployment barrier, particularly for producers upgrading from legacy systems or introducing inspection on previously unmonitored lines. At the same time, the supply chain for vision components, illumination systems, and processing hardware continues to evolve, with vendors seeking to balance performance with total cost of ownership.
Rising labor costs and workforce constraints in manufacturing are also reshaping the cost-benefit calculus for inspection adoption. In environments where skilled operators are difficult to recruit or retain, automated inspection offers a pathway to stabilize quality output while reducing reliance on manual inspection labor. This dynamic does not uniformly apply across all markets, but it is increasingly relevant in regions and sectors where labor availability is tightening. The interaction between labor economics and inspection investment helps explain why adoption rates can diverge even among producers with similar product portfolios.
Competitive Landscape and Strategic Positioning
The competitive environment in the print quality inspection system market is characterized by a mix of specialized inspection vendors, broader machine vision providers, and prepress solution companies. This diversity reflects the multidisciplinary nature of the market, which draws on expertise in imaging, color measurement, web monitoring, packaging workflows, and quality management software. The presence of both established European and North American players and rapidly evolving Asian manufacturers adds further complexity, as differing regional strengths shape product focus, pricing approaches, and go-to-market strategies.
Differentiation Strategies Among Leading Players
Leading participants are pursuing differentiation along several axes, with the most successful strategies combining technical capability with workflow integration and sector-specific relevance.
- Some vendors position themselves around AI-powered inspection for packaging and printed products, emphasizing defect detection and prepress verification across dedicated hardware and software series. Their approach targets customers who prioritize integrated solutions with established brand recognition in print inspection.
- Other companies focus on label and flexible packaging applications, offering real-time defect detection and color measurement tools designed to reduce waste and support high-speed production environments. This specialization allows them to align closely with the operational priorities of label converters and flexible packaging manufacturers.
- A separate group develops vision-based inspection systems for printing and packaging that emphasize automated visual quality control at high speeds, often leveraging AI to improve defect classification and adaptability across substrates.
- Web monitoring and inspection specialists serve the pulp, paper, and printing industries with surface defect detection solutions, reflecting a distinct application focus that differs from packaging-centric vendors.
- Providers of integrated web inspection and tension control systems combine print quality solutions with broader process control capabilities, appealing to customers who value unified monitoring across multiple production parameters.
- Machine vision and vision system companies offer automated inspection and verification tools for packaging and labeling, drawing on broader portfolio strength in industrial vision to address print quality as part of a larger automation strategy.
- Prepress and artwork verification vendors concentrate on upstream quality control, enabling automated artwork and packaging verification before production, which complements downstream inspection and can reduce defect propagation.
These positioning differences matter because they shape which customers view a given vendor as a natural fit. A label converter prioritizing real-time waste reduction will evaluate vendors differently than a pharmaceutical packaging producer focused on compliance documentation and audit readiness. Similarly, a printing operation seeking to upgrade both prepress and in-line inspection may prefer a vendor with capabilities spanning both domains, while another may value best-of-breed specialization.
Recent Market Movements and Their Strategic Signals
Recent corporate and product developments provide useful signals about where competitive pressure is intensifying and how vendors are attempting to capture value. One significant move involved the acquisition and restructuring of a prominent inspection company into an independent entity, enabling a dedicated focus on print quality inspection solutions. Such a transformation typically reflects a strategic decision to sharpen product focus, reallocate resources, and respond more agilely to market demands without the constraints of a broader corporate structure. For customers, this can translate into more specialized support and roadmap clarity; for competitors, it may intensify pressure in segments where the newly independent company has strong installed bases.
On the product side, the launch of a next-generation AI inspection system at a major industry event highlighted the continuing emphasis on AI-driven visual quality control for printing applications. Concurrently, another vendor introduced cloud-based prepress inspection software designed to operate independently of specific hardware, underscoring a shift toward software-defined inspection workflows that can reduce dependency on proprietary hardware ecosystems. The visibility of these solutions at major trade events further illustrates how vendors are using industry platforms to demonstrate defect detection capabilities and align product messaging with current production challenges.
Taken together, these developments suggest a market in which hardware capability remains important, but software flexibility, AI maturity, and workflow integration are increasingly decisive in competitive battles. Vendors that can offer modular, upgradeable solutions and clear data pathways between prepress, production, and quality management systems are better positioned to retain customers through technology refresh cycles.
Market Structure Evolution: Consolidation, Specialization, and New Entrants
The moderate concentration levels in the market indicate that fragmentation persists, but the trajectory points toward gradual consolidation in certain segments. Larger machine vision and industrial automation companies may seek to expand their footprint by leveraging existing customer relationships and broader automation portfolios, while specialized inspection vendors may pursue partnerships, selective acquisitions, or geographic expansion to strengthen their positions. At the same time, new entrants—particularly those bringing novel AI capabilities or cost-competitive imaging architectures—can gain traction in segments where incumbents are slow to adapt or where price sensitivity is elevated.
The evolution of the market will likely be shaped by the relative success of three dynamics. First, consolidation may accelerate where installed base advantages and service networks create meaningful switching costs, allowing larger players to capture share through bundling and cross-selling. Second, specialization may remain attractive in high-value verticals such as pharmaceutical packaging, where compliance expertise and sector-specific workflows command premium positioning. Third, new entrants may disrupt segments where traditional inspection approaches are perceived as overly rigid or too costly relative to emerging AI-based alternatives. The interplay among these dynamics will determine which companies build durable advantages and which face pressure to differentiate more sharply or reposition.
X-ray Inspection Systems Market
Forward Outlook: Three Trends to Watch
Looking ahead, the print quality inspection system market is likely to be shaped by several interconnected trends over the next three to five years.
AI Maturity and the Shift from Detection to Classification and Prediction
The next phase of AI adoption in inspection systems is expected to move beyond basic defect detection toward more sophisticated classification, root-cause suggestion, and predictive quality analytics. As algorithms become more robust and training data more abundant, inspection systems can increasingly distinguish between defect types, prioritize issues by severity, and feed insights back into process control. This evolution enhances the value of inspection not only as a gate but as an intelligence source that supports continuous improvement. Commercial opportunity lies in systems that can integrate defect data with production parameters, enabling operators to correlate visual defects with substrate changes, ink variability, or machine settings. The primary risk is that AI capabilities may outpace customers’ ability to operationalize them, creating a gap between feature availability and practical benefit realization.
Software-Defined Inspection and Interoperability as Competitive Battlegrounds
The introduction of hardware-independent, cloud-enabled inspection software reflects a broader movement toward interoperability and software-centric value. As manufacturers seek to avoid lock-in and integrate inspection data across prepress, production, and enterprise quality systems, the ability to exchange data seamlessly and configure inspection workflows without hardware constraints will become more important. Vendors that invest in open architectures, standardized data outputs, and flexible deployment models are likely to gain an advantage in environments where multi-vendor equipment and evolving IT strategies are the norm. The risk for the market is that interoperability expectations may pressure margins for vendors reliant on proprietary hardware ecosystems, while also raising the bar for software development and integration support.
PW Consulting
Regulatory Tightening and Sector-Specific Premiumization
As regulatory frameworks continue to evolve, particularly in pharmaceutical, medical, and food-related packaging, the premium on inspection systems that support compliance documentation, audit readiness, and consistent defect classification is likely to increase. This creates a segmentation dynamic in which regulated sectors may adopt higher-specification solutions and accept stronger compliance-related value propositions, while less regulated segments may compete more intensely on price and throughput. Commercial opportunity exists for vendors that can clearly articulate compliance benefits, provide configurable rule sets aligned with sector requirements, and offer data integrity features that support audit trails. The uncertainty lies in the pace and variability of regulatory change across jurisdictions, which can complicate product planning and require ongoing adaptation.
Strategic Guidance for Decision Makers
The trajectory of the print quality inspection system market suggests that decision makers should evaluate opportunities and risks through a lens that goes beyond unit pricing and specification sheets. In practice, three strategic considerations stand out.
For manufacturers and producers considering inspection deployment, the priority should be to align system selection with the broader quality and operational roadmap rather than treating inspection as an isolated procurement. This means evaluating how well a solution integrates with prepress workflows, production line control, and quality management systems, and whether it can scale as defect classification, data analytics, and regulatory documentation needs evolve. It also means assessing total cost of ownership in the context of labor constraints, waste reduction potential, and compliance risk, rather than focusing solely on initial capital expenditure. Where possible, manufacturers should favor solutions that offer modular upgrade paths, configurable inspection rules, and clear data portability, reducing the risk of obsolescence as requirements change.
For investors and strategic partners, the market presents a nuanced opportunity set shaped by the balance between hardware-driven deployments and software-defined value creation. Companies that can demonstrate AI capability, interoperability, and sector-specific relevance are better positioned to capture share than those competing primarily on imaging hardware alone. Investment theses should consider the durability of installed base advantages, the potential for consolidation in segments with high switching costs, and the risk that new entrants with novel AI or cost architectures could challenge incumbents in price-sensitive segments. Due diligence should also account for regulatory exposure, particularly in verticals where compliance dynamics directly influence procurement decisions and solution requirements.
For procurement and quality leaders, the immediate focus should be on building an inspection strategy that balances near-term defect reduction with long-term data utilization. This includes defining clear acceptance criteria for defect classification accuracy, false reject rates, and integration requirements; ensuring that inspection data can feed into broader quality analytics; and evaluating vendor support for changeovers, substrate variability, and evolving regulatory expectations. Procurement decisions made without a clear view of data integration, compliance alignment, and upgrade flexibility may deliver short-term savings but create downstream bottlenecks as quality programs mature. Access to detailed segmentation data, vendor benchmarking, and customized deployment scenarios can materially improve the quality of these decisions, particularly when evaluating multi-vendor shortlists or planning multi-site rollouts.
For executives seeking a more granular understanding of regional demand patterns, application-specific growth differentials, and vendor-level positioning across sub-segments, a deeper dive into the full research dataset can provide the scaffolding needed to translate these market-level insights into actionable plans. Detailed breakdowns of segmentation dynamics, competitive benchmarks, and scenario-based procurement considerations can help clarify where to prioritize investment, which vendor profiles warrant closer evaluation, and how to structure quality inspection roadmaps in line with operational and regulatory realities.
For detailed analysis of this topic, please visit the official page: Print Quality Inspection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


