



Eddy Current Sensor Market: How $1.86B Scale and 6.5% CAGR Redefine 2026 Growth

Navigating the Eddy Current Sensor Market: Strategic Trends and Commercial Opportunities Through 2032
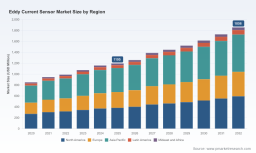
The eddy current sensor market has evolved from a niche instrumentation segment into a critical enabler of precision monitoring, non-destructive testing, and automated control across heavy industry, advanced manufacturing, and critical infrastructure. Tracking the revenue trajectory from 2020 through 2032 reveals a market that has consistently expanded, crossing the 1.1 billion threshold by 2025 and moving toward approaching 1.9 billion by the end of the forecast horizon. The compound annual growth rate sits at approximately 6.5 percent, a rate that signals steady, technology-led expansion rather than cyclical volatility. This growth is not uniform across all segments; it reflects a reallocation of capital toward high-reliability displacement and condition monitoring applications, alongside a steady uptake of advanced inspection probes in asset-intensive sectors.
For executives and investors, the headline numbers matter less than the structural shifts underneath them. The market is maturing in ways that reward suppliers who can pair submicron measurement accuracy with ruggedized packaging, certified reliability, and integration-ready interfaces. At the same time, procurement teams and system integrators face a landscape where raw material volatility, certification requirements, and shifting trade policies are reshaping cost structures and lead times. Understanding these dynamics is essential for positioning product portfolios, negotiating supplier relationships, and anticipating where value will accrue over the next several years.
Market Snapshot and Core Challenges
The revenue path from 2020 to 2032 illustrates a market that has grown through steady adoption rather than sudden spurts. After moving from roughly 850 million in 2020 to approximately 1.195 billion in 2025, the trajectory continues upward with incremental but compounding gains each year, reaching an estimated 1.856 billion by 2032. This pattern points to a market where recurring replacement cycles, expanding end-use monitoring requirements, and the gradual penetration of advanced sensor types are driving volume. The consistency of the growth curve also suggests that demand is becoming more predictable, which benefits suppliers that can plan capacity and service networks with greater confidence.
Despite the positive trajectory, the industry faces a set of challenges that will define competitive outcomes. Three stand out as especially consequential for strategy and operations.
Precision-to-Ruggedness Trade-offs in Harsh Environments
As deployment shifts from controlled laboratory and clean manufacturing settings into turbines, petrochemical plants, and outdoor automation cells, the tolerance for environmental stress has increased sharply. Sensors must now deliver submicron accuracy while surviving high temperatures, moisture, chemical exposure, and mechanical shock. The push for ingress-protected designs, such as IP69K-rated housings, is no longer optional for many industrial buyers. This creates a design tension: protecting the sensing element and electronics without compromising thermal stability, signal integrity, or mounting flexibility. Suppliers that solve this engineering puzzle with purpose-built mechanical designs and validated sealing approaches gain a meaningful advantage in bids where reliability is weighted heavily against price.
Certification, Qualification, and Personnel Requirements
Non-destructive testing and condition monitoring applications increasingly require adherence to recognized standards for both equipment and personnel. For eddy current testing, qualification frameworks for inspectors and the alignment of sensor performance with accepted procedures are becoming table stakes in regulated sectors. This raises the barrier to entry for generic instrumentation and favors suppliers that can document traceability, provide application guidance, and support certification workflows. For buyers, the challenge is not only evaluating sensor accuracy but also ensuring that the entire measurement chain—from probe selection to data interpretation—meets auditable standards. This dynamic is shifting purchasing decisions toward bundled solutions that include training, documentation, and service support, rather than standalone hardware.
Cost Structure Pressure from Materials and Trade Policy
The bill of materials for eddy current probes and instruments is increasingly exposed to commodity and trade dynamics. Copper wire coils, essential to many sensor designs, are subject to price swings tied to broader commodity volatility. At the same time, magnet assemblies used in high-frequency sensors depend on materials that face export constraints in key sourcing regions. Layered on top of this are tariffs and trade measures that affect the landed cost of sensors originating in certain countries, particularly for North American manufacturers. These pressures do not invalidate the market's growth but they do compress margins for suppliers that rely on undifferentiated component sourcing and pass through cost shocks without engineering countermeasures. Forward-looking players are responding with material substitution where feasible, dual-sourcing strategies, and design choices that reduce sensitivity to any single input.
Key Drivers Shaping the Market
Growth in this market is being propelled by a combination of technological advancement, regulatory and standards activity, evolving demand-side behavior, and supply-side restructuring. Each driver reinforces the others, creating a multi-year pull that extends beyond simple capacity expansion.
Technology Innovation: Submicron Accuracy Meets Industrial Hardening
Recent product introductions show a clear emphasis on improving measurement fidelity while extending environmental durability. The launch of new eddy current displacement sensor series with submicron accuracy and high ingress protection ratings reflects a deliberate push to serve applications where even minor measurement drift can affect process quality or equipment safety. In turbomachinery and other rotating equipment, updated sensor specifications for radial and axial displacement are enabling more precise vibration and shaft monitoring, which supports predictive maintenance and reduces unplanned downtime. For non-destructive testing, the continued refinement of eddy current array probes and associated instrumentation is expanding inspection coverage and reducing scan time on complex geometries. These innovations matter because they convert sensors from passive measurement devices into integral parts of reliability and quality programs, increasing their value proposition and sticking power in customer operations.
Policy and Standards Environment: Compliance as a Competitive Moat
Regulatory and standards activity is shaping both procurement and product development. Personnel qualification requirements for eddy current testing reinforce the importance of instruments that produce repeatable, interpretable results and that can be supported with documented procedures. In parallel, equipment-level protection standards are becoming reference points in industrial procurement, with IP-rated sensors increasingly specified where washdown, chemical exposure, or outdoor deployment is expected. This environment rewards suppliers that invest in compliance documentation, application notes, and service frameworks that reduce the administrative burden on end users. It also raises the cost of disintermediation: once a sensor family is integrated into a certified maintenance or inspection workflow, switching costs rise, creating longer contract horizons and more predictable revenue for incumbents.
Eddy Current NDT Equipment Market
Demand-Side Shifts: Predictive Maintenance and Automation Integration
On the demand side, the most important behavioral change is the accelerating move from reactive repair to condition-based and predictive maintenance. Industrial operators are deploying displacement, vibration, and proximity monitoring earlier in asset lifecycles and integrating sensor data into broader digital maintenance strategies. In factory automation, the push for more reliable presence detection, positioning, and displacement feedback is driving adoption in high-cycle environments where contactless measurement offers clear advantages in wear reduction and throughput. In energy and heavy process industries, turbines, generators, and rotating shafts are being monitored with greater rigor to protect availability and extend service intervals. This demand shift is significant because it expands the addressable use cases for eddy current sensors beyond inspection alone, pulling them into continuous monitoring and control loops where recurring value is created.
Supply Chain and Cost Structure: Regional Realignment and Collaboration
Supply-side dynamics are being reshaped by both cost pressures and strategic collaboration. Tariffs and trade measures affecting certain sensor origins are prompting North American and European manufacturers to reconsider sourcing and assembly footprints, with some shifting toward regional integration or diversified supplier bases to manage landed cost and lead time risk. At the same time, partnerships aimed at joint development of advanced displacement sensors for factory automation signal a move toward co-engineering and scaled deployment, where shared roadmaps and large installation targets reduce per-unit risk and accelerate field validation. These developments indicate that the market is moving beyond fragmented, transactional sales toward more structured ecosystems in which partners align on performance targets, qualification paths, and deployment scale. For suppliers, this means that supply chain resilience and partnership strategy are now as important as sensor performance in winning multi-year programs.
Competitive Landscape and Leading Strategies
The market is characterized by a meaningful but not immovable concentration, with the top three competitors accounting for roughly 48 percent of revenue and the top five approaching 58 percent. This structure suggests that established players hold strong positions in high-value applications and regional channels, while there is still room for specialized entrants and regional challengers to capture share in focused segments. The competitive game is increasingly defined by application mastery, environmental robustness, certification support, and the ability to embed sensors into broader automation or inspection solutions rather than selling components in isolation.
Magnetic Field Sensors Market
Differentiation Themes Among Leading Players
Several companies illustrate the breadth of strategic positioning in the market. One German manufacturer has built a reputation around high-precision non-contact displacement measurement, with product lines designed for applications that demand stable accuracy and clean signal performance. Its recent introduction of a new displacement sensor series with submicron accuracy and IP69K protection underscores a strategy of pairing measurement precision with ruggedization for harsh industrial settings. A United States-based specialist focuses on linear encoders and displacement sensors that emphasize reliable linear measurement for automation and machine building, positioning itself around repeatable feedback in production environments. A Canadian company has carved out a differentiated role in non-destructive testing through eddy current array probes and instruments, where inspection coverage and data quality are the primary value drivers. A German test equipment maker emphasizes crack detection and material sorting through its eddy current test instruments and probes, serving qualification-heavy environments where procedural reliability matters as much as hardware performance. A major United States industrial player contributes a different dimension with sensors designed for turbomachinery displacement and vibration monitoring, linking sensor performance to rotating equipment reliability programs.
Additional participants broaden the competitive field. A Japanese manufacturer offers eddy current sensors and measuring systems for displacement, rotation, and vibration, reflecting a strategy that spans multiple measurement modalities within a unified portfolio. A Chinese manufacturer targets non-destructive testing applications with eddy current detectors and testing systems, competing on accessibility and application breadth in inspection workflows. A United States precision instruments company supplies eddy current proximity probes for displacement and vibration measurement, reinforcing the importance of established probe families in condition monitoring. A Japanese measurement systems leader integrates eddy current displacement sensors into broader measurement platforms, illustrating a strategy that leverages platform ecosystems and customer relationships to expand sensor attachment rates. Together, these players show that success is not monolithic: some win on precision and ruggedness, others on inspection coverage, some on platform integration, and others on cost-accessible testing solutions.
Strategic Moves and What They Signal
Recent developments provide a window into how competitors are shaping the next phase of the market. The introduction of a new displacement sensor series with submicron accuracy and high ingress protection indicates that incremental performance gains continue to be a viable growth lever, especially where environmental resilience is becoming a procurement requirement. A partnership between a large automation supplier and a sensor specialist to jointly develop advanced displacement sensors for factory automation, with a target of over 18,000 installations, signals the increasing importance of scaled co-development and deployment-oriented roadmaps. This kind of collaboration reduces risk for both sides and creates a pathway to embedded adoption in standardized automation cells, where sensor selection is influenced by integration readiness and service support as much as by raw specification.
On the instrumentation side, an updated specification sheet for a 5mm eddy current sensor for radial and axial shaft displacement in turbomachinery highlights the continued refinement of rotating equipment monitoring products, where small specification improvements can unlock broader acceptance in reliability programs. More dramatically, the acquisition of a leading eddy current array and NDNondestructive Testing solutions provider by a large industrial corporation demonstrates that consolidation is actively reshaping the landscape. This transaction enhances the acquirer's portfolio in eddy current array and inspection solutions, adding capability that can be leveraged across a broader customer base and combined with adjacent technologies. The implication for the market is that capability concentration is increasing at the high end of non-destructive testing, while displacement and proximity sensing remain competitive across a wider set of specialists and platform players.
Market Evolution: Consolidation, Differentiation, and Selective Entry
The competitive trajectory appears to be moving along three parallel paths. Consolidation is strengthening the offerings of larger players in inspection and condition monitoring, particularly where array-based testing and rotating equipment monitoring can be bundled with broader service and platform capabilities. Differentiation is deepening around environmental robustness, submicron accuracy, certification support, and integration readiness, making product selection more application-specific and reducing the relevance of price-only comparisons in high-stakes deployments. Selective entry remains possible in regional or application-focused niches, especially where suppliers can offer cost-effective testing systems, strong local support, or specialized probe geometries for particular inspection challenges. For buyers, this means that the supplier landscape is increasingly stratified: a handful of broad-capability leaders, a set of application-dominant specialists, and a tail of regional or price-competitive providers. Navigating this landscape successfully requires matching the supplier's strengths to the application's criticality, compliance needs, and integration requirements.
Future Outlook: Trends and Commercial Opportunities
Looking ahead three to five years, the market's direction is likely to be shaped by the convergence of measurement performance, environmental hardening, and integration depth. Three trends stand out as particularly consequential for strategy and investment.
Trend One: Embedded Monitoring Becomes the Default in Critical Assets
Edy current sensors are increasingly being specified earlier in asset design and integrated into continuous monitoring architectures for turbines, generators, rotating shafts, and high-cycle automation equipment. This trend is driven by the availability of ruggedized, high-accuracy sensors and by the economic logic of predictive maintenance: avoiding downtime and extending service intervals creates value that justifies higher sensor performance and more thorough installation. The commercial opportunity here lies in moving from component sales to solution-oriented engagement, where suppliers help define mounting, calibration, data paths, and maintenance procedures. Suppliers that can document reliability in service, simplify integration, and support data workflows will capture more of the lifecycle value than those that stop at the point of hardware sale.
Trend Two: Inspection Coverage and Speed Improvements Expand NDT Use
In non-destructive testing, eddy current array probes and associated instrumentation continue to improve inspection coverage and reduce scan time on complex components. As certification and qualification expectations rise, the ability to produce repeatable, well-documented results becomes a stronger differentiator. The opportunity for technology providers is to align probe designs and instrument features with the practical needs of inspectors and quality teams, including intuitive operation, clear data presentation, and support for standardized procedures. For operators, the upside is faster throughput and broader inspection coverage without sacrificing compliance, which can translate into lower inspection cost per unit and better asset availability. The risk is that procurement may treat inspection sensors as commoditized unless suppliers invest in documentation, training, and application engineering that reinforces the link between equipment performance and inspection quality.
Trend Three: Supply Chain Resilience and Regional Strategy Become Pricing and Margin Determinants
Material volatility in copper and constraints on certain magnet materials, combined with tariffs and trade measures affecting specific origins, are making supply chain strategy a direct determinant of competitiveness. Over the next several years, suppliers that diversify sourcing, qualify alternative materials where performance allows, and structure assembly and logistics to reduce landed-cost exposure will be better positioned to hold margin while remaining responsive to customers. There is also an opportunity for partnerships and co-development models that spread risk across larger installation targets and shared roadmaps, particularly in factory automation where standardized deployments can amortize engineering cost. The uncertainty here lies in the trajectory of trade policy and commodity markets; both can shift quickly, and suppliers that have not built flexibility into their cost structures may find themselves reacting rather than shaping commercial terms.
Strategic Guidance for Decision-Makers
The market's trajectory creates different implications for manufacturers, investors, and procurement organizations. In each case, the key is to align strategy with where value is consolidating and where flexibility is most needed.
For Manufacturers and Product Leaders
- Prioritize ruggedized precision as a combined design objective. Submicron accuracy is increasingly expected, but industrial bids are increasingly won by products that pair accuracy with verified ingress protection, thermal stability, and mounting practicality. Treat environmental robustness as a core specification, not a secondary feature.
- Invest in integration readiness and documentation. Suppliers that provide clear mounting guidance, calibration support, and compliance-relevant documentation reduce the friction of adoption in certified maintenance and inspection workflows. This lengthens contract horizons and raises switching costs in the customer's favor.
- Build supply chain optionality. Where copper and magnet dependencies create exposure, explore qualified alternatives, dual sources, and design adjustments that reduce sensitivity to any single input. Pair this with regional sourcing or assembly considerations where trade policy affects landed cost.
For Investors and Corporate Development Teams
- Focus on application depth over broad component exposure. Value is accruing to players with strong positioning in rotating equipment monitoring, factory automation displacement feedback, and advanced array-based inspection, where performance, certification, and integration create defensible positions. Evaluate targets and partners through the lens of application mastery and service attach rates rather than unit volume alone.
- Watch consolidation in non-destructive testing and the co-development model in automation. Acquisitions that add array and inspection capability can create cross-selling and platform leverage, while partnerships aimed at large installation targets can accelerate deployment and reduce per-unit risk. Both structures can improve competitive durability if they are paired with strong field support and qualification alignment.
- Assess exposure to trade and material dynamics in cost models. Investments that assume stable input costs or single-origin supply may face margin pressure if commodity volatility or tariff structures shift. Portfolios with diversified sourcing and regional flexibility are better positioned to preserve returns through cycles.
For Procurement and Operations Leaders
- Evaluate the full measurement chain, not just the sensor. In regulated or high-availability contexts, total value includes qualification support, repeatability documentation, ingress protection, and the supplier's ability to support installation and service. A marginally cheaper sensor that creates compliance friction or integration rework can carry higher total cost than a better-documented alternative.
- Specify environmental and protection requirements explicitly. Where washdown, chemical exposure, temperature extremes, or outdoor deployment are expected, treat ingress protection and ruggedization as primary selection criteria. This reduces the risk of field failures and rework and aligns procurement with the realities of the operating environment.
- Negotiate with supply continuity in mind. Given volatility in key materials and trade-related cost impacts, consider sourcing strategies that include qualified alternatives, regional supply options, and clear lead-time commitments. Contracts that account for material and logistics realities are more resilient than those based on static pricing assumptions.
The eddy current sensor market is moving from a phase defined by incremental specification gains to one shaped by application integration, environmental robustness, compliance alignment, and supply chain strategy. Growth at a steady mid-single-digit pace through the end of the forecast period provides a constructive backdrop, but the commercial winners will be those who convert that growth into durable positions in critical monitoring and inspection applications. For decision-makers who need segment-level sizing, regional deployment patterns, competitive benchmarking, and tailored scenario planning, a detailed research report can provide the deeper data and structured frameworks required to translate these trends into concrete portfolio, sourcing, and investment decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Eddy Current Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


