



Hexagonal BN Market Insights: Why 4.71% CAGR Signals Strategic Shifts

The Hexagonal Boron Nitride Market: Strategic Trends and Commercial Opportunities Through 2032
The hexagonal boron nitride market is undergoing a structural shift. Once confined to niche industrial niches, the material is now embedded in the strategic planning of companies operating in electronics, advanced coatings, and thermal management. Market size has expanded from approximately 766 million in 2020 to an estimated 954 million in 2025, representing a compound annual growth rate of 4.71 percent through 2032. The trajectory points toward a market crossing the 1.3 billion mark by 2032, driven by accelerating demand in high-performance applications and a gradually maturing supply base. This article examines the forces shaping the market, the competitive dynamics at play, and the strategic decisions that will separate winners from laggards over the next five years.
For executives and investors, the central question is no longer whether hexagonal boron nitride will see broader adoption, but where the value will concentrate and how to position for it. The answers hinge on understanding the interplay between technological breakthroughs, regulatory tailwinds, shifting demand patterns, and a supply chain that is beginning to reorganize.
PW Consulting Chemical & Energy Research Center
Market Reality and Core Challenges
The market's recent expansion reflects a compounding of steady industrial demand and targeted investment in applications that require thermal conductivity, electrical insulation, and chemical stability. While the overall growth rate is moderate, it masks underlying volatility across customer segments and geographies. Revenue distribution is not uniform, and the structural drivers differ sharply depending on whether the end use is coatings, thermal management, or specialty industrial processes.
Three challenges define the current inflection point.
-
Raw material economics and feedstock volatility. Although import unit values for combined US boron materials have eased, providing temporary relief for producers, the broader cost environment remains sensitive to logistics, regional pricing, and the availability of refined borax and boric acid. Feedstock stability influences margin predictability and limits the speed at which manufacturers can scale without incurring cost risk.
-
Regulatory and supply chain realignment. The designation of boron as a critical mineral has shifted attention toward domestic production incentives and supply chain resilience. This development creates opportunities for onshore capacity but also raises compliance complexity, investment thresholds, and coordination requirements among miners, refiners, and downstream manufacturers.
-
Application fragmentation and qualification hurdles. Demand is distributed across multiple use cases, but each segment carries distinct technical requirements, testing standards, and procurement cycles. This fragmentation slows the conversion of laboratory promise into commercial volume, particularly in electronics-adjacent applications where material consistency, purity, and integration reliability must be demonstrated.
These challenges are interconnected. Feedstock volatility influences cost structures, regulatory shifts affect where capacity is built and how supply is secured, and application fragmentation determines which segments can scale quickly and which remain constrained by qualification timelines. The net effect is a market that is expanding but not uniformly easy to navigate.
Key Drivers Shaping the Market
Technology Innovation and Performance Breakthroughs
The most consequential driver is the continued improvement in material form and integration methods. Hexagonal boron nitride is increasingly valued not just as a powder but as engineered solutions tailored for specific performance profiles. Advances in monolayer films, high-purity powders, and composite formulations are expanding the addressable set of applications, especially where thermal management and electrical insulation must coexist in compact devices.
Suppliers that can deliver controlled particle size, consistent purity, and reproducible performance characteristics are gaining traction in high-value segments. In semiconductor and advanced electronics contexts, the ability to provide films and powders that meet stringent integration requirements is a meaningful differentiator. This focus on performance consistency is shifting the competitive battleground from volume alone to quality and technical support.
Policy and Regulatory Environment
Policy dynamics are becoming a more visible force. The inclusion of boron in the critical minerals list has formalized government attention on supply security, onshore production, and resilience. For hexagonal boron nitride producers, this signals potential support mechanisms, procurement preferences, and incentives that could favor domestic or allied supply chains.
At the same time, the regulatory environment introduces a dual effect. It can accelerate investment in local feedstock and processing capacity, but it can also lengthen planning horizons as companies navigate qualification, permitting, and partnership structures. Firms that anticipate these shifts and align their sourcing and capacity strategies early are better positioned to benefit from policy momentum rather than respond after the fact.
Demand-Side Shifts in End-Use Industries
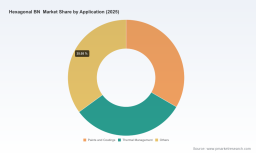
Demand is being reshaped by two complementary trends. First, thermal management is moving up the priority list in power electronics, LEDs, and related devices, where efficiency, reliability, and compactness are non-negotiable. Second, in coatings and industrial applications, the material's lubrication, non-stick, and high-temperature stability properties continue to support steady adoption, especially where downtime reduction and surface protection deliver clear operational value.
What is changing is not just the volume of demand but the specificity of requirements. Customers increasingly want materials that are not merely available but demonstrably compatible with their processes, test protocols, and performance targets. This is pushing more technical engagement earlier in the buying cycle and rewarding suppliers that can offer application engineering support alongside product supply.
Supply Chain Evolution and Cost Structure
Supply chain dynamics are evolving as producers react to cost pressures, geographic concentration, and the push for resilience. Import data indicates that unit values for combined US boron materials have softened, which provides some margin breathing room. At the same time, volumes of refined borax and boric acid have remained stable, supporting a more predictable flow into downstream processing.
The broader implication is that the cost environment is improving in the near term but remains exposed to longer-cycle risks. Producers that diversify sourcing, invest in processing efficiency, and secure multi-source feedstock arrangements can translate temporary relief into durable cost advantages. Those dependent on single-channel supply or unable to manage quality consistency may find that any temporary cost improvement is quickly eroded by volatility.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the top three firms accounting for roughly 52 percent of revenue and the top five closer to 64 percent. This structure suggests meaningful scale advantages for established players, while still leaving room for specialists and regional suppliers to compete on performance, service, and niche positioning.
Several strategic archetypes are visible among the leading companies.
CBN Abrasives Market
-
Large diversified producers offer breadth, global reach, and the ability to serve multiple application verticals. Their advantage lies in scale, integrated capabilities, and the capacity to support customers across thermal management, lubrication, insulation, and advanced ceramics.
-
Specialists and technology-focused firms compete on material form, purity, and application fit. Companies working on high-quality films, high-purity powders, and semiconductor-adjacent solutions are building defensibility by aligning closely with demanding end uses and technical qualification cycles.
-
Regional and volume-oriented manufacturers, particularly in Asia Pacific, leverage scale in powder production and industrial composite applications. Their strength is often rooted in domestic market depth, strong production volume, and cost-competitive positioning.
The differentiation is increasingly less about who can produce hexagonal boron nitride and more about how well a supplier can match material properties to application requirements while maintaining supply reliability. Leading players combine consistent quality, application engineering, and supply chain readiness with a clear focus on the segments where they can win on performance rather than price alone.
Market Structure Evolution
The landscape is likely to evolve through a combination of consolidation, specialization, and selective new entry. Consolidation may continue among players seeking scale advantages and broader application coverage. At the same time, the demand for specialized films, high-purity materials, and application-specific formulations will sustain a role for focused specialists, especially where technical barriers and qualification requirements create moats.
New entrants will face a steep climb unless they bring a clear advantage in material quality, process control, regional supply access, or application alignment. The critical mineral designation and growing attention to supply resilience may also encourage investment in new capacity, particularly where feedstock access and downstream partnerships can be aligned early.
Forward Trends and Commercial Opportunities
Trend 1: Thermal Management Moves from Opportunity to Requirement
As power electronics, LEDs, and compact high-performance devices continue to advance, thermal management becomes less optional and more foundational. Hexagonal boron nitride's combination of thermal conductivity and electrical insulation positions it for continued relevance. The commercial opportunity lies not simply in higher volume but in integrated solutions that reduce design friction, improve reliability, and shorten qualification cycles for end customers.
Producers that pair material performance with application engineering and predictable supply are likely to capture disproportionate value in this trend. The risk is that without consistent quality and clear integration support, thermal management demand may fragment across suppliers or shift toward alternative materials where performance and availability are easier to certify.
Trend 2: Supply Chain Localization and Critical Mineral Momentum
The critical mineral status of boron is likely to reinforce interest in regional supply chains, domestic sourcing incentives, and resilience-focused procurement. Over the next three to five years, this could translate into new investment in feedstock access, processing capacity, and strategic partnerships that reduce exposure to foreign supply shocks.
The opportunity is for companies to align capacity plans, sourcing strategies, and customer commitments with the direction of policy and procurement preferences. The uncertainty lies in timing and execution. Policy support does not automatically convert into demand at scale, and capacity built without corresponding demand visibility or application fit can create overinvestment risk.
Trend 3: Higher Performance Standards and Application Qualification
Demand across coatings, thermal solutions, and industrial uses is increasingly conditional on verified performance. This raises the bar for consistency, documentation, and technical support. Suppliers that can provide traceable quality, reproducible properties, and application-specific validation will face fewer barriers to scale-up in demanding segments.
The upside is stronger pricing power and longer customer relationships in applications where qualification is a barrier to entry. The downside is that any lapse in quality or supply consistency can rapidly erode trust and open the door to competitors or alternative materials, especially in segments where switching costs are moderate and performance differentials must be proven continuously.
Action Implications for Decision-Makers
For Manufacturers and Material Suppliers
-
Invest in application-visible differentiation. Performance consistency, particle and film control, purity, and integration support matter more as demand shifts toward electronics-adjacent and thermal management applications. Competing on volume alone is increasingly insufficient where qualification and reliability drive selection.
-
Strengthen feedstock resilience and cost control. Even with near-term import unit value relief, build multi-source sourcing and processing efficiency to protect margins against future volatility. Align capacity expansion with segments where demand visibility and qualification pathways are clearest.
-
Prepare for policy-driven supply shifts. Anticipate the implications of critical mineral momentum on sourcing, partnerships, and capacity location decisions. Early alignment with regional supply incentives and resilient feedstock strategies can turn policy momentum into a competitive advantage.
For Investors and Strategic Planners
-
Focus on the segments where qualification and performance create durable advantages. Thermal management and high-purity, application-specific materials offer more defensible positioning than commoditized volume plays. Assess companies on their ability to sustain quality, support integration, and navigate supply chain complexity, not just on production capacity.
-
Watch for consolidation signals and regional capacity shifts. Moderately high concentration leaves room for both consolidation and specialization. Evaluate the strategic logic behind moves that expand application breadth, secure feedstock access, or strengthen regional presence, especially where critical mineral policy and demand resilience are converging.
-
Stress-test assumptions around demand timing and supply response. Policy support and technical promise do not automatically equal immediate volume. Build scenarios that separate near-term cost relief and stable feedstock flows from longer-cycle demand conversion, and assess whether companies have the application alignment to scale without overinvesting.
For Procurement and Sourcing Leaders
-
Prioritize suppliers with verified consistency and application support. In thermals, coatings, and industrial uses, the risk of performance variation or supply inconsistency often outweighs marginal cost savings. Evaluate supply partners on quality documentation, technical engagement, and resilience of their feedstock and capacity base.
-
Diversify strategically, not indiscriminately. Multi-source strategies should be paired with clear criteria for performance equivalence and qualification readiness. The goal is resilience without fragmenting the supply base in ways that increase validation burden or dilute performance reliability.
-
Monitor policy and feedstock signals as part of sourcing risk management. Critical mineral designation and import unit value trends can change the attractiveness of regional supply options and the timing of capacity decisions. Incorporating these signals into sourcing plans helps avoid reactive shifts when supply conditions change.
Conclusion
The hexagonal boron nitride market is moving from steady industrial relevance toward a more strategically significant position, especially where thermal management, high-performance coatings, and advanced electronics applications converge. Growth to the 1.3 billion range by 2032 is plausible within the current trajectory, but the real commercial action will depend on how well participants navigate feedstock economics, regulatory momentum, and application qualification. The winners are likely to be those who convert material capability into application-ready solutions, secure resilient supply chains, and align with the demand profiles that value performance consistency as much as availability.
Boron Nitride Nanotubes (BNNT) Market
For organizations making investment, sourcing, or production decisions, the next step is to assess exposure to these dynamics in detail. A fuller evaluation of segment-level demand, regional supply patterns, competitive positioning, and scenario-based risk can clarify where to build advantage now and where to monitor for change. Detailed analysis is available in the complete research report.
For detailed analysis of this topic, please visit the official page: Hexagonal BN Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


