



Whole-house Ventilation System Market: How 6.52% CAGR Reshapes Residential Growth

The Whole-house Ventilation System Market: Strategic Trends and Commercial Opportunities Through 2032
The global whole-house ventilation system market has entered a phase of structural expansion, driven by tightening building codes, growing awareness of indoor air quality, and the broader transition toward energy-efficient residential design. Valued at approximately 3.84 billion USD in 2025, the market has grown steadily from 2.8 billion USD in 2020, reflecting a compound annual growth rate that positions it for sustained momentum through the end of the decade. Projections indicate revenue will reach roughly 5.97 billion USD by 2032, underpinned by a CAGR of 6.52 percent across the forecast period. This trajectory is not merely a function of incremental demand growth; it reflects a fundamental shift in how buildings are designed, regulated, and operated. Ventilation is no longer treated as a passive exhaust function but as an integrated component of indoor environmental quality, energy management, and occupant health.
PW Consulting
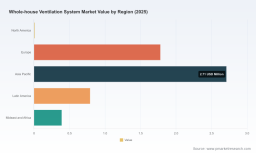
The market's expansion is geographically uneven, with mature regulatory environments and high construction activity driving adoption in certain regions, while emerging markets are accelerating uptake as building standards converge with international best practices. Product segmentation reveals a clear preference for heat recovery and energy recovery technologies, which together dominate revenue share due to their ability to balance fresh air intake with thermal efficiency. Residential applications account for the largest share of demand, reflecting both new construction requirements and retrofit activity in existing housing stock. Commercial and industrial segments, while smaller in absolute terms, are growing as facility operators prioritize air quality compliance and energy performance in larger building portfolios. Despite this growth, the market remains moderately fragmented, with the top three players capturing less than a quarter of total revenue and the top five holding a similarly limited share. This fragmentation suggests room for consolidation, strategic positioning, and differentiation as the market matures.
Key Challenges and Inflection Points
The industry faces several structural challenges that will shape competitive dynamics over the next forecasting cycle. First, regulatory fragmentation across jurisdictions creates compliance complexity for manufacturers and distributors. While a growing number of U.S. jurisdictions now require whole-house ventilation systems in new single-family and multifamily construction, the specific standards, testing protocols, and enforcement mechanisms vary widely. This patchwork increases product adaptation costs and complicates market entry strategies for firms targeting multiple regions. Second, the market is experiencing a technology transition as builders and homeowners weigh the performance characteristics of heat recovery versus energy recovery systems. Each approach offers distinct advantages in different climate conditions, and the optimal choice depends on local humidity profiles, energy costs, and design priorities. Misalignment between product capabilities and regional requirements can lead to underperformance, warranty claims, and reputational risk. Third, the industry must navigate supply chain and cost pressures that affect both manufacturing economics and end-user affordability. Component availability, material cost volatility, and labor constraints can compress margins and delay project timelines, particularly in high-growth segments where demand outpaces production capacity.
Key Drivers of Market Change
Technological Innovation and Performance Breakthroughs
Advances in heat and energy recovery technologies are reshaping the value proposition of whole-house ventilation systems. Modern units are achieving higher sensible and latent recovery efficiencies while reducing fan power consumption, enabling builders to meet stringent energy codes without sacrificing indoor air quality. Innovations in enthalpy exchange media, modular design, and integrated controls allow systems to adapt to variable operating conditions and maintain performance across seasonal shifts. Cold-climate optimization has become a particular focus, as manufacturers develop units that maintain recovery efficiency and condensate management in low-temperature environments. These technical improvements are not incremental refinements; they are expanding the addressable market by making ventilation systems viable in regions where earlier generations of equipment struggled to deliver consistent performance.
Policy and Regulatory Environment
Regulatory momentum is one of the strongest catalysts for adoption. Building code adoptions across multiple U.S. jurisdictions now require whole-house ventilation in new single-family and multifamily homes, embedding these systems into the baseline design of new construction rather than treating them as optional upgrades. California's 2025 Energy Code exemplifies this shift by prohibiting exhaust-only systems in new multifamily construction and mandating fault indicator displays for HRV and ERV systems, which raises the bar for monitoring and maintenance. Acceptance testing protocols, such as the 2025 NRCA-MCH-23-A standard, verify airflow, sensible recovery, and fan power compliance for multifamily buildings, creating a more rigorous validation framework. At the national level, ASHRAE Standard 62.2 continues to serve as the reference for minimum ventilation rates in residential mechanical systems, providing a consistent technical baseline that manufacturers can align with. Together, these regulatory developments are converting ventilation from a discretionary specification into a code-driven requirement, which stabilizes demand and encourages standardized product architectures.
Demand-Side Shifts in Consumer and Builder Behavior
Demand is being reinforced by changing expectations around indoor environmental quality. Homebuyers and commercial facility operators increasingly view air quality, humidity control, and ventilation performance as integral to health, comfort, and asset value. This perspective is amplified by greater public awareness of airborne contaminants and the role of mechanical ventilation in managing indoor pollutant levels. Builders are responding by specifying ventilation systems earlier in the design process, integrating them with HVAC architectures to simplify installation and improve balanced air exchange. In multifamily projects, developers are recognizing that compliant, efficient ventilation systems can reduce operational liabilities and support certification goals tied to energy performance and occupant well-being. The result is a demand environment that values not just airflow volume but measurable recovery efficiency, reliability, and ease of commissioning.
Residential Ventilation Systems Market
Supply Chain and Cost Structure Dynamics
Cost structures are evolving as manufacturers scale production, optimize component sourcing, and invest in design-for-manufacturability. Economies of scale are beginning to moderate unit costs for high-volume product lines, though premium segments with advanced controls or specialized climate adaptations remain relatively pricey. The supply chain for core components, including heat exchange media, fans, and control electronics, is maturing but remains sensitive to material price fluctuations and logistics constraints. Firms that secure reliable sourcing, standardize subassemblies across product families, and align production capacity with regional demand patterns are better positioned to protect margins. At the same time, installation and commissioning complexity can affect total cost of ownership for end users, making turnkey solutions and dealer support networks increasingly important competitive factors.
Competitive Landscape and Leading Strategies
The competitive field is populated by a mix of established HVAC manufacturers, specialized ventilation brands, and regional players with strong climate-specific engineering. Carrier offers energy-efficient HRV and ERV ventilator systems designed for whole-house indoor air quality and balanced ventilation, leveraging its broader residential portfolio to integrate ventilation with familiar HVAC platforms. Zehnder America focuses on the ComfoAir series of ERV and HRV units engineered for whole-house fresh air supply with high efficiency, emphasizing performance consistency and installer-friendly design. Panasonic contributes WhisperComfort ERV and related heat and energy recovery systems tailored for whole-house residential use, drawing on its reputation for quiet operation and reliability in connected home environments.
Broan-Nutone and RenewAire both target residential applications with integrated ventilation products and balanced ERV systems, respectively, with an emphasis on whole-house indoor air quality and fresh air exchange. Lifebreath has carved out a position around cold-climate ERV and HRV systems optimized for whole-house ventilation performance, addressing markets where temperature extremes demand robust recovery and defrost management. EXINDA provides HVI-certified ERV units for whole-house fresh air solutions that comply with North American standards, appealing to specifiers seeking verified performance and code alignment. Trane integrates whole-house ventilation with its broader HVAC offerings to improve IAQ and balanced air exchange, positioning ventilation as part of a unified climate control strategy rather than a standalone add-on.
In Europe, STIEBEL ELTRON offers the LWZ series of central ventilation systems with enthalpy heat exchangers for whole-house indoor air quality, reflecting a design philosophy that centralizes air handling for larger or more complex residential layouts. Aereco differentiates through hybrid ventilation systems with room-by-room demand control, targeting applications where adaptive airflow can reduce energy use while maintaining air quality in specific zones. These varied approaches illustrate how companies are aligning product architectures with regional climate needs, installation practices, and buyer expectations.
Strategic Positioning and Differentiation
Leading firms are differentiating along several axes. Some emphasize integration with existing HVAC ecosystems, reducing installation friction and enabling unified controls. Others focus on certified performance, climate-specific engineering, or demand-controlled airflow to appeal to performance-driven specifiers and code-conscious developers. Brand trust, warranty support, and dealer network strength also play outsized roles, particularly in residential markets where installers influence equipment selection. Companies that combine high recovery efficiency with low fan power, clear fault indication, and straightforward commissioning are gaining traction in jurisdictions where testing and compliance requirements are becoming more stringent.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market's moderate concentration leaves space for both consolidation and targeted fragmentation. Larger HVAC players may pursue acquisitions to fill geographic gaps, expand product lines, or acquire specialized engineering capabilities in cold-climate or demand-control ventilation. At the same time, niche entrants can thrive by serving specific climate zones, certification requirements, or application segments where standardized offerings fall short. New entrants from adjacent industries, including building automation and indoor air quality monitoring, may seek to bundle ventilation with sensing and control platforms, creating integrated solutions that address both air quality and energy performance. The likely outcome is a maturing landscape where scale advantages matter more, yet differentiated technical positioning remains a viable path to growth.
Future Trends and Commercial Opportunities
Trend 1: Code-Driven Standardization and Certification as a Competitive Moat
As more jurisdictions adopt ventilation requirements and acceptance testing protocols, compliance will become a baseline expectation rather than a differentiator. Products that demonstrate verified airflow, sensible recovery, and fan power performance will be preferred in bid processes and inspections. This trend favors manufacturers that invest in third-party certification, clear documentation, and repeatable commissioning procedures. Commercial opportunity lies in designing product families that can be configured to meet multiple regional standards without extensive custom engineering, reducing time-to-market and installation risk.
Trend 2: Integration of Ventilation with Smart Controls and IAQ Monitoring
The next phase of value creation will come from linking ventilation hardware with sensing, controls, and building management platforms. Demand-controlled ventilation, fault detection, and adaptive recovery strategies can optimize energy use while maintaining air quality targets. This convergence creates opportunities for bundled offerings that combine ventilation equipment with monitoring endpoints and control logic, appealing to homeowners who want visibility and to commercial operators who need centralized management. The risk is that integration complexity can raise costs and create dependency on software ecosystems, so interoperability and open communication pathways will be important to sustain adoption.
Trend 3: Climate-Specific Engineering and Regional Product Strategies
Climate diversity will continue to reward specialized engineering. Cold-climate HRV and ERV performance, humid-region latent load management, and mixed-climate flexibility will remain critical purchase criteria. Companies that maintain distinct product variants for key climate bands, rather than offering a one-size-fits-all lineup, are better positioned to capture regional demand without compromising performance. The associated opportunity is to build regional go-to-market strategies that pair the right product architecture with local installer training, warranty support, and code alignment. A potential risk is over-segmentation, which can inflate inventory and manufacturing complexity; disciplined platform design with modular options is the balance point.
Actionable Guidance for Decision Makers
For Manufacturers and Product Leaders
Prioritize platform strategies that allow climate-specific and code-specific variants to be derived from a common core. Invest in certified performance data, fault indication, and commissioning simplicity, as these features are increasingly tied to approval and installers' willingness to specify. Strengthen dealer and installer support, because in residential markets the installation ecosystem often determines repeat business and brand reputation. Evaluate where integration with HVAC platforms or smart controls adds genuine value versus where it introduces unnecessary complexity, and focus differentiation on the attributes that most directly affect compliance, energy performance, and reliability.
For Investors and Strategic Allocators
Look for companies with clear climate adaptation capabilities, credible certification footprints, and distribution relationships that can scale with code-driven demand. Favor business models that can expand revenue through add-on controls, maintenance services, or retrofit solutions, as these can improve lifetime value without requiring constant new construction volume. Monitor consolidation signals, particularly where larger HVAC portfolios seek to absorb specialized ventilation brands to broaden geographic reach or technical coverage. Be mindful of regulatory variability across regions, which can create uneven revenue trajectories even within a single national market.
For Procurement and Specification Teams
Specify ventilation systems with verified performance, clear fault indication, and documented compliance with relevant standards, rather than relying on nominal airflow claims. Evaluate total cost of ownership including installation complexity, commissioning requirements, and ongoing maintenance, since these factors often determine operational outcomes more than equipment price alone. Where possible, align product selection with regional code trajectories and climate conditions to avoid over-engineering in mild climates or under-specifying in extreme ones. Build relationships with installers and service providers early in the specification process to ensure that selected systems can be deployed and maintained effectively.
The whole-house ventilation system market is moving from optional specification to code-embedded infrastructure, with technological improvements, regulatory momentum, and demand-side expectations reinforcing one another. The firms and investors that understand these dynamics, and that align product strategy with regional requirements and performance verification, are best positioned to capture value as the market expands toward 2032 and beyond. For decision makers seeking detailed segmentation data, regional breakdowns, and customized strategic recommendations, the full PW Consulting report provides the granular analysis needed to translate these trends into concrete action plans.
Energy Recovery Ventilation System Market
For detailed analysis of this topic, please visit the official page: Whole-house Ventilation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


