



LTCC Ceramic Substrates Market: 6.3% CAGR Trajectory and Regional Shifts to 2032

Navigating the LTCC Ceramic Substrates Market: Strategic Trends and Commercial Opportunities Through 2032
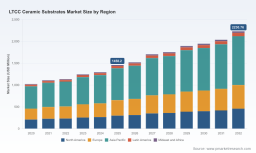
The low-temperature co-fired ceramic (LTCC) substrates market has entered a decisive growth phase, driven by the convergence of high-frequency connectivity, automotive electrification, and advanced packaging demands. Between 2020 and 2025, global revenue expanded from approximately 1,022.6 million USD to 1,458.2 million USD, reflecting sustained investment in miniaturized, high-reliability interconnect solutions. The forward trajectory points to a compound annual growth rate of 6.3 percent, with the market projected to reach 2,230.8 million USD by 2032. This expansion is not uniform; it is concentrated among a handful of established manufacturers, with the top three players capturing roughly 65 percent of revenue and the top five accounting for approximately 75 percent. The market structure signals both maturity and opportunity: incumbents hold significant technical and capacity advantages, while lingering pockets of regional and application-specific demand create room for targeted differentiation and strategic entry.
Understanding this landscape requires moving beyond aggregate numbers. The pace of growth, the concentration of supply, and the shifting priorities of end-use industries all carry direct implications for procurement planning, capacity investment, and competitive positioning. The following analysis distills the structural forces shaping the LTCC substrate market, the competitive behaviors defining the leading cohort, and the strategic choices that decision-makers should prioritize as the market moves through 2026 and beyond.
Market Landscape and Core Challenges
The LTCC substrate market has navigated a period of steady expansion, but the current environment is defined less by raw growth and more by the quality and direction of that growth. Over the past five years, demand have been supported by the adoption of multilayer ceramic architectures in applications requiring high integration density, stable dielectric performance, and robust thermal characteristics. The market's ability to grow at a mid-single-digit pace through 2032 suggests that LTCC substrates are becoming an embedded component in several technology roadmaps rather than a cyclical beneficiary of a single end market.
Despite this favorable trajectory, the industry faces three interconnected challenges that will shape competitive outcomes in the near term:
-
Demand diversification across applications and regions. Revenue is increasingly distributed among multiple application categories, with consumer electronics representing the largest segment, followed by automotive electronics, aerospace and military use, and a smaller residual category. This dispersion means that no single application can be treated as a universal proxy for market health. Suppliers must manage distinct qualification cycles, performance requirements, and volume profiles simultaneously, which complicates capacity planning and margin management.
-
Market concentration and the risk of complacency. With the top three and top five firms holding significant revenue shares, the market exhibits characteristics of a consolidated value chain. Concentration can yield scale efficiencies and consistent quality, but it also raises the bar for differentiation. Incumbents must continuously invest in material formulations, process control, and integration capabilities to defend positions, while smaller players must identify niches where specialized performance, lead-time advantages, or regional proximity offer defensible value.
-
Technology and qualification pressures in high-reliability segments. As LTCC substrates expand into automotive radar, 5G RF modules, and advanced semiconductor packaging, the tolerance for variability narrows. Meeting automotive and defense-grade expectations requires rigorous process consistency, advanced dielectric control, and documented supply-chain traceability. These requirements lengthen time-to-revenue for new designs and increase the cost of quality, pressuring firms to balance innovation with certified repeatability.
A secondary but material consideration is the stability of the input environment. Alumina feedstock prices have remained stable, with no reported increases or disruptions affecting LTCC production in 2025 and 2026. The broader alumina supply chain showed no force majeure events or capacity constraints as of early 2026, and there have been no new export controls or tariffs specifically targeting alumina or LTCC ceramic substrates in major economies during this period. Compliance with ISO 9001 and automotive AEC-Q200 standards continues as a baseline requirement without recent regulatory changes, and no new environmental restrictions or transport surcharges on key precursors have been reported. This relative calm in raw material and regulatory conditions provides a stable backdrop for investment, but it also means that competitive advantage will be determined more by process know-how and product architecture than by input cost arbitrage.
PW Consulting
Key Drivers Shaping Market Dynamics
Technological Innovation and Material Advancements
The most compelling driver of market evolution is the ongoing refinement of LTCC materials and multilayer architectures. LTCC technology enables high-density interconnect with embedded passive elements, controlled impedance, and thermal performance suited to demanding RF and power applications. Recent product activity illustrates how manufacturers are translating material science into commercial advantage. In April 2026, a major ceramics supplier announced the commercialization of a breakthrough multilayer ceramic core substrate for advanced AI semiconductors, featuring high rigidity and circuit miniaturization, with an unveiling planned at ECTC 2026. This development signals a deliberate push to extend LTCC beyond traditional RF and sensor applications into advanced packaging domains where dimensional stability and mechanical robustness are critical.
Simultaneously, peers have focused on expanding the performance envelope for connectivity and mobility. In May 2025, a leading manufacturer introduced a next-generation ceramic substrate optimized for high-frequency 5G modules and automotive radar applications. This launch reflects the broader requirement to support wider bandwidths, tighter integration, and consistent signal integrity in environments where electrical performance and mechanical reliability must coexist. Capacity decisions reinforce this direction: in July 2025, another major player expanded production capacity for multilayer ceramic capacitors integral to LTCC substrate performance to meet automotive and telecommunications demand. These moves indicate that substrate suppliers are not only improving individual product attributes but are also aligning capacity and component availability to support system-level integration.
Ceramic Substrate Market
Policy and Regulatory Environment
The policy backdrop has been a stabilizing force rather than a disruptive one. The absence of new export controls or targeted tariffs on alumina or LTCC ceramic substrates in 2025 and 2026 has reduced the likelihood of sudden cost shocks or supply fragmentation. Equally important, the regulatory expectations that do exist—such as ISO 9001 and automotive AEC-Q200 compliance—are well established and continuously applied across active producers. For decision-makers, this means that qualification frameworks are predictable, but they still represent meaningful barriers. Firms that have matured their quality systems and documentation processes are better positioned to win automotive and defense-related programs, while newer entrants face a steeper path to certification. The policy environment therefore favors disciplined, process-oriented operators and rewards long-term investment in quality infrastructure.
Demand-Side Shifts in Consumer, Automotive, and High-Reliability Markets
On the demand side, the market is being reshaped by the needs of three broad clusters. Consumer electronics continue to provide the largest revenue base, driven by the ongoing need for compact, high-integration solutions in mobile and connectivity-oriented devices. Automotive electronics represent the second-largest segment, fueled by the expansion of advanced driver-assistance systems, radar-based sensing, and power management modules that require substrates with strong reliability profiles. Aerospace and military applications, while smaller in absolute terms, contribute disproportionately to requirements for thermal endurance, dimensional stability, and long-term consistency. The "others" category captures additional niche demands, but together these application groups highlight a market where volume and value are distributed across very different qualification and performance regimes.
This diversification matters because it changes how suppliers should allocate engineering resources. A substrate designed for high-volume consumer modules must balance cost and throughput, whereas an automotive radar substrate must prioritize repeatable RF behavior and qualification evidence. An aerospace or defense program may emphasize traceability and environmental robustness more than unit-cost optimization. The ability to serve multiple demand profiles without diluting process control is increasingly a defining capability.
Supply Chain and Cost Structure Dynamics
Cost structure dynamics have been characterized by input stability and process-driven differentiation. Stable alumina feedstock pricing and the absence of force majeure events in the global supply chain through early 2026 have kept variable cost risk contained. However, LTCC substrate economics are increasingly influenced by factors beyond raw materials: layer count, via formation precision, dielectric consistency, yield management, and integration of embedded components all affects the cost-to-performance ratio. Firms that can raise performance while maintaining yield and minimizing rework will capture margin advantages, even in a stable input environment. This is why capacity expansions are often paired with product launches and material innovation rather than treated as standalone volume plays. The market rewards integrated improvements rather than isolated scaling.
Competitive Landscape and Leading Strategies
The competitive field is dominated by a dense cluster of Japanese manufacturers, complemented by notable European, U.S., and select Asian players. This geographic concentration reflects decades of accumulated expertise in ceramic materials, multilayer processing, and high-frequency component integration. The major firms have built strong positions by aligning substrate capabilities with adjacent component businesses, such as multilayer capacitors, RF modules, and precision sensors, which allows them to serve system integration requirements more holistically.
Several strategic patterns emerge among the leaders:
-
Vertical alignment with component ecosystems. Leading manufacturers often combine LTCC substrates with complementary passive and active components. This integration supports higher-density designs and reduces the customer's need to manage multiple supplier interfaces for highly interdependent functions. It also creates switching costs for end-users who value validated subsystem performance.
-
Application-specific material and process leadership. Some firms emphasize high-rigidity ceramic cores for advanced semiconductor packages, while others prioritize dielectric formulations for high-reliability RF front-end modules, antennas, and power electronics. Specialized producers focus on automotive sensors, industrial electronics, or high-frequency and power applications, building reputations around reproducible performance in targeted domains.
-
Certification and reliability as market access tools. Companies serving automotive, aerospace, and defense applications treat quality certification as a core competitive asset. Adherence to established standards is not merely a compliance activity; it is a gating factor for program participation. Firms that have institutionalized these systems can secure long-cycle contracts that smaller, less certified rivals cannot easily enter.
HTCC Ceramic Substrates Market -
Regional specialization and proximity advantages. European and U.S.-based producers often compete by offering tailored custom substrates, turnkey fabrication up to high layer counts, and close collaboration with customers in defense, medical, and high-reliability industrial sectors. Chinese and Taiwanese manufacturers participate in the consumer and telecom supply chains, leveraging scale and proximity to volume-driven programs.
Recent corporate activity reinforces these strategies. The April 2026 commercialization of a high-rigidity multilayer ceramic core substrate for advanced AI semiconductors illustrates how incumbents are extending their technology into next-generation packaging requirements. The July 2025 capacity expansion for multilayer ceramic capacitors tied to LTCC performance, and the May 2025 launch of a substrate optimized for 5G and automotive radar, both demonstrate a pattern of synchronized product and capacity moves aimed at capturing demand in high-growth connectivity and mobility segments.
Looking forward, the market structure is likely to evolve along three lines. First, consolidation pressure will persist among smaller players who lack the scale or certification depth to compete across multiple applications, potentially leading to selective acquisitions or capacity partnerships. Second, differentiation will increasingly hinge on architectural innovation—layer count, via precision, thermal-mechanical performance, and embedded component integration—rather than on basic substrate supply. Third, new entrants and regional specialists may find opportunities in high-mix, lower-volume niches, especially where proximity, customization speed, or domain-specific expertise outweighs the advantages of the largest incumbents. The overall trajectory suggests a market that is consolidating at the top while remaining open to specialized value creation below the leading tier.
Future Trends and Commercial Implications (2026–2032)
Expansion into Advanced Packaging and AI-Enabled Semiconductor Systems
One of the most significant trends is the extension of LTCC substrates into advanced packaging domains associated with AI and high-performance computing. The commercialization of high-rigidity ceramic core substrates with circuit miniaturization indicates that LTCC is being evaluated for structural and interconnect roles beyond conventional RF modules. As semiconductor architectures continue to push thermal and dimensional requirements, LTCC's combination of stability and integration density can create opportunities in packages that demand precise alignment, mechanical robustness, and embedded functionality. For suppliers, this is a route to higher value-add and longer program lifecycles; for end-users, it may offer a pathway to consolidate interconnect functions and reduce packaging complexity.
Continued Growth in Automotive and High-Frequency Connectivity Applications
Automotive electronics and high-frequency connectivity are expected to remain central growth engines. The expansion of radar-based sensing, 5G-related RF modules, and power electronics in vehicles supports steady demand for substrates with consistent RF behavior and strong reliability credentials. At the same time, consumer electronics will continue to provide volume, though margin profiles may differ. The commercial implication is that suppliers must be able to straddle both high-volume cost sensitivity and high-reliability performance requirements without compromising quality. Companies that can manage these dual demands with disciplined process control and application-specific engineering will be better positioned to capture share.
Stabilization of Input Conditions Likely to Shift Competition Toward Process and Integration Capability
With alumina feedstock prices stable, no reported force majeure events in the supply chain, and no new tariffs or export controls targeting LTCC materials, the immediate cost environment is unlikely to be a differentiating shock factor. This shifts the source of advantage toward manufacturing precision, yield management, material formulation, and integration capability. Firms that can deliver higher performance per layer, reduce defect rates, and offer validated subsystem-level solutions will capture more value than those competing primarily on price. For procurement teams, this means that supplier selection should weigh process maturity and qualification depth as heavily as unit economics.
Potential Risks and Uncertainties
Several uncertainties warrant attention. First, while the input environment has been calm, any future disruption in alumina availability or precursor logistics could quickly alter cost dynamics and lead-time reliability, particularly for high-volume programs. Second, the trajectory of automotive and telecom demand is subject to broader macroeconomic and cycle risks; a slowdown in vehicle production or a shift in telecom capex could temporarily soften demand in specific segments. Third, as LTCC substrates extend into advanced packaging and higher-performance domains, qualification and technical validation requirements may intensify, increasing time-to-revenue and raising the cost of failure. Firms should plan for scenario variability in both demand and validation timelines.
Strategic Actions for Decision-Makers
For Manufacturers and Substrate Suppliers
-
Invest in differentiated architectural capabilities. Prioritize improvements that raise performance without sacrificing yield, such as advanced dielectric control, via precision, layer integration, and thermal-mechanical robustness. Product launches paired with targeted capacity expansion, as seen in recent 5G and automotive radar moves, are more effective than undifferentiated volume increases.
-
Deepen application-specific qualification and documentation. Strengthen ISO 9001 and AEC-Q200-aligned processes where relevant, and build evidence packages that support automotive, aerospace, and defense participation. Reliable certification infrastructure is a market-access advantage in high-reliability segments.
-
Align capacity with high-growth demand clusters. Use demand signals from consumer, automotive, and connectivity segments to calibrate expansions. Synchronizing substrate capacity with complementary component availability can improve system-level value and reduce customer integration friction.
For Investors and Strategic Partners
-
Focus on firms with material and process differentiation rather than pure scale plays. In a stable input environment, the companies most likely to capture margin and share are those with proprietary ceramic formulations, high layer-count capability, and proven high-reliability qualification. Evaluate pipeline activity, such as advanced packaging substrate development, as an indicator of future value creation.
-
Monitor integration and geographic diversification. Track how leading players extend into adjacent component businesses and how regional specialists position around customization and proximity. Consolidation among smaller firms and selective partnerships may create opportunities for entry at favorable valuations or with strengthened capability sets.
For Procurement and Engineering Leaders
-
Prioritize supplier capability depth over headline price. In LTCC substrates, process consistency, qualification evidence, and integration support often determine long-term total cost more than initial unit price. Assess suppliers on yield stability, layer-count capability, RF and thermal performance consistency, and ability to support custom requirements.
-
Plan for multi-application supply strategies. Because demand spans consumer, automotive, and high-reliability segments, consider dual-sourcing or application-specific supplier assignments to balance volume needs with qualification requirements. Engage suppliers early in design cycles to align material and process choices with end-system performance goals.
The LTCC ceramic substrates market is entering a phase where growth is sustained, but the nature of competition is becoming more refined. Stable input conditions, predictable regulatory expectations, and a concentrated but still diversified supplier base create a setting in which process excellence, application-specific engineering, and integration capability will determine who captures durable advantage. The companies and organizations that prepare for these dynamics now—by investing in differentiated capabilities, strengthening qualification infrastructure, and aligning supply strategies with application realities—will be better positioned to convert market growth into commercial value through 2032 and beyond.
For teams seeking a deeper, segment-specific view of regional demand distribution, application splits, type-based revenue patterns, concentration benchmarks, and detailed company profiles, a comprehensive research report provides the structured data and tailored scenarios needed to support precise planning. Detailed breakdowns and customized recommendations can help translate these strategic trends into concrete operating decisions.
For detailed analysis of this topic, please visit the official page: LTCC Ceramic Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


