



Aseptic Packaging Market: Why 10.5% CAGR and 156 Billion Scale Redefine Growth

Aseptic Packaging Market: Strategic Trends and Commercial Opportunities Through 2032
The global aseptic packaging sector has cemented its status as a critical infrastructure layer across food, beverage, and pharmaceutical value chains. Between 2020 and 2025, the market expanded from approximately $45.7 billion to $78.3 billion, reflecting sustained demand for shelf-stable, contamination-resistant containment solutions. Forward-looking estimates project the market to surpass $156 billion by 2032, underpinned by a compound annual growth rate of 10.5 percent. This trajectory signals more than incremental growth; it reflects a structural reconfiguration of how liquids and sensitive goods are preserved, distributed, and consumed across geographies.
Yet the figures only sketch the surface. Beneath the headline expansion lies a sector navigating material science transitions, regulatory realignments, and shifting distribution economics. Decision-makers who treat aseptic packaging as a static commodity risk missing both margin compression and strategic positioning opportunities. Understanding the forces reshaping the market is essential for aligning capital allocation, product development, and supply chain strategy with the next phase of industry evolution.
Market Snapshot and Core Challenges
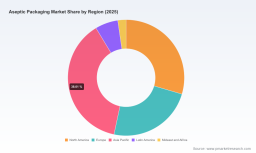
The aseptic packaging market operates at the intersection of food safety, pharmaceutical integrity, and logistical efficiency. Cartons and bags/pouches collectively represent the dominant format categories, while food and beverage applications account for the majority of end-use demand. Regional demand is distributed across developed and emerging markets, with Asia Pacific and North America capturing substantial share, supported by mature dairy and juice ecosystems as well as expanding ready-to-drink and nutritional supplement segments.
Despite robust top-line growth, the industry is approaching several inflection points that warrant strategic attention.
Material Compliance and Recyclability Pressures
Regulators and brand owners are increasingly treating end-of-life performance as a design constraint rather than an afterthought. The EU Packaging and Packaging Waste Regulation entered into force in February 2025 and establishes recyclability requirements for packaging placed on the European market, with detailed design-for-recycling criteria expected to be finalized through delegated acts by 2028. For aseptic packaging specifically, compliance pathways are pushing manufacturers toward aluminum layer minimization and mono-material component architectures. This shifts the competitive basis from mere barrier performance to total recyclability yield and compliance documentation.
Material Substitution and Barrier Technology Race
Traditional aseptic structures have long relied on multi-layer laminates incorporating aluminum foil to achieve microbial barrier and extended shelf life. The push toward recyclable mono-material systems is intensifying investment in paper-based barriers, polymer alternatives, and advanced sealing technologies. Companies pioneering aluminum-free or low-aluminum solutions are betting that recyclability, brand owner ESG commitments, and potential extended producer responsibility cost structures will reward early movers. However, the technical challenge remains substantial: maintaining sterility, oxygen and light barrier properties, and seal integrity without compromising recyclability.
Capacity Realignment and Regional Demand Divergence
Investment patterns indicate a deliberate expansion of aseptic carton and filling capacity in markets serving dairy, shelf-stable beverages, and emerging consumer categories. Simultaneously, pharmaceutical-grade vial, ampoule, and sterile transit packaging demand is being shaped by biologics growth, cold-chain complexity, and regulatory scrutiny. The divergence between high-volume food-grade aseptic systems and precision pharma packaging creates different capital intensity profiles, lead-time expectations, and quality assurance requirements, complicating one-size-fits-all capacity planning.
Key Drivers Shaping Market Trajectory
Several interlocking forces explain why the market is advancing at a double-digit growth cadence while simultaneously restructuring around compliance and material innovation.
Technological Innovation in Barrier and Filling Systems
The most consequential technical shift is the transition from conventional aluminum-dependent aseptic structures to recyclable mono-material and aluminum-minimized designs. Tetra Pak’s EUR 60 million investment in a new pilot plant in Lund, Sweden, focused on paper-based barrier technology to replace aluminum foil in aseptic cartons illustrates how incumbents are reallocating R&D toward recyclable architectures. SIG has similarly rolled out aluminum-free aseptic carton solutions in select European markets, targeting improved recycling yield for dairy and juice applications. On the equipment side, aseptic filler and bottling line providers are refining PET and flexible format lines to handle new material specifications without sacrificing throughput or sterility assurance. The implication is clear: aseptic packaging is becoming a materials-and-engineering problem as much as a containment problem, and differentiation will increasingly derive from demonstrable recyclability, performance consistency, and line compatibility.
Regulatory Environment Reshaping Design and Sourcing
Regulatory momentum is no longer confined to safety and labeling; it now directly influences structural design and procurement strategies. The EU PPWR’s phased application timeline creates a near-term compliance window that favors firms able to redesign structures, validate recycling streams, and document design-for-recycling criteria ahead of delegated act finalization. For multinational manufacturers and brand owners, this regulatory environment introduces both cost and opportunity: early alignment can reduce future redesign fatigue, mitigate potential compliance penalties, and strengthen sustainability claims in markets where packaging performance is scrutinized by retailers and consumers alike. Conversely, lagging players may face restructuring costs, stranded assets in non-compliant formats, and slower market access in regulated regions.
Sterile Medical Packaging Market
Demand-Side Evolution in Food and Beverage
Consumer and retail behavior continues to reinforce demand for shelf-stable, portable, and clean-label compatible packaging. Aseptic cartons and pouches remain attractive for dairy, juices, plant-based beverages, and liquid foods because they combine protection with supply chain flexibility. Recent product category expansions, such as SIG’s entry into camel milk with new aseptic carton solutions, highlight how format adaptability enables penetration into niche and regional dairy segments that demand both sterility and cultural product specificity. Beyond traditional categories, the broader trend toward functional beverages, premium juices, and ready-to-consume nutrition products is expanding the addressable space for aseptic systems that can preserve product quality without preservatives or continuous refrigeration.
Supply Chain and Cost Structure Realignment
Aseptic packaging economics are being reshaped by raw material dynamics, regionalized production, and the cost of compliance. The emergence of large-scale carton manufacturers in Asia, including publicly listed players now ranking among the world’s largest aseptic carton producers, adds scale competition and regional sourcing alternatives. At the same time, investments in Mexico and other nearshore locations, such as SIG’s additional US$ 35 million expansion of its Querétaro aseptic carton plant, reflect a strategic emphasis on serving regional demand with localized capacity, shorter logistics routes, and tariff or trade-flow optimization. For converters and brand owners, the result is a more distributed supply base that can improve resilience but also requires tighter quality governance, specification alignment, and vendor qualification discipline.
Competitive Landscape and Leadership Strategies
The competitive field is shaped by a mix of global incumbents with integrated packaging and filling capabilities, specialized format providers, and equipment manufacturers whose technology choices influence downstream material adoption. Market concentration remains moderate, with the top three firms holding a substantial share and the top five collectively representing just over forty percent of the market. This structure suggests room for both differentiated positioning and consolidation, particularly where scale, regional presence, and technology licensing create advantages.
Differentiated Positioning Among Leading Players
Several strategic archetypes are visible across the leadership group. One focuses on integrated aseptic systems spanning carton formation, filling, and downstream support, with strong positions in dairy and liquid foods. Another emphasizes extended shelf-life plastic bottles and specialized barrier features, including UV protection and longer durability windows for specific beverage applications. A third centers on flexible bag-in-box and spouted bulk systems tailored for industrial and liquid handling use cases. A fourth stream involves sterilized transit packaging and pharma-oriented solutions, where the value proposition rests on contamination control, regulatory alignment, and handling precision rather than mass-market retail volume. Equipment specialists further shape the ecosystem by determining which packaging formats can be manufactured efficiently at scale, effectively acting as adoption accelerators for new materials and structures.
Strategic Moves and Recent Developments
Recent activity underscores how companies are translating strategy into capacity and product decisions. Tetra Pak’s Lund pilot plant investment targets paper-based barrier replacement for aluminum foil, an explicit bet on recyclable carton architecture. SIG’s aluminum-free aseptic carton rollout in Europe and its camel milk category entry show simultaneous focus on structural compliance and category diversification. SIG’s Querétaro expansion reflects a regional capacity build to support dairy and shelf-stable beverage demand closer to end markets. On the exhibition and ecosystem side, companies such as ASEPTO and Steriline have showcased aseptic liquid packaging innovations and advanced filling lines at major industry events, signaling continued emphasis on technology visibility, customer engagement, and solution-level selling. These moves collectively indicate that leadership is increasingly defined by the ability to combine material innovation, regional capacity alignment, and application-specific portfolio breadth.
Market Structure Evolution: Consolidation, Fragmentation, and New Entrants
The market is likely to evolve along two concurrent paths. In mature format segments, scale advantages, integrated service models, and compliance readiness may encourage consolidation or strategic partnerships, particularly where recyclability mandates increase the cost of lagging behind. In parallel, specialized niches and emerging regions may see continued fragmentation, with new entrants targeting specific applications, local material supply chains, or cost-competitive manufacturing models. The presence of large Asian carton producers and regional capacity investments suggests that price competition and localized service will matter alongside technology leadership. For customers, this means the supplier base is becoming more varied in terms of risk-return profiles, and procurement strategies will need to balance scale, compliance assurance, and regional responsiveness rather than defaulting to a single incumbent.
Future Outlook: Three Trends to Watch
Looking toward 2027 and beyond, the market appears headed toward a period in which recyclability, material substitution, and regional capacity alignment become central to commercial performance. Three trends are especially salient.
Bulk Aseptic Packaging Market
Trend 1: Recyclability-Driven Format Redesign Becomes Commercial Mainstream
As delegated design-for-recycling criteria crystallize and brand owners face mounting expectations from retailers, consumers, and regulators, recyclable mono-material and aluminum-minimized aseptic structures are likely to move from pilot and select-market usage to broader commercial deployment. This trend creates opportunities for providers that can prove equivalent barrier performance, reliable seal integrity, and compatible recycling streams. It also introduces risk for formats that cannot meet recyclability thresholds without significant redesign or process changes. Companies that establish validated recycling pathways and transparent compliance documentation will be better positioned to secure long-term brand owner contracts, particularly in Europe and other regulated markets.
Trend 2: Regionalized Capacity and Category-Specific Portfolio Expansion
Investments in localized production and category-focused solutions are expected to continue as firms seek to reduce logistics exposure, serve emerging dairy and beverage segments, and respond to trade and tariff dynamics. This regionalization will likely coincide with more targeted product development, such as carton solutions tailored to specialty milks, plant-based beverages, and nutrition liquids. The commercial opportunity lies in pairing capacity proximity with format flexibility, enabling faster response to regional demand shifts. The uncertainty is whether regional capacity builds will generate sufficient scale to offset higher unit costs in smaller markets, or whether demand concentration will remain uneven across geographies.
Trend 3: Integration of Equipment, Materials, and Service as a Competitive Moat
As material specifications become more complex and regulatory expectations rise, the ability to offer compatible filling equipment, technical support, and compliance assistance will matter more than ever. Equipment providers and packaging suppliers that coordinate material behavior with line performance, sterility assurance, and changeover efficiency can reduce customer adoption friction for new formats. This creates a strategic path for incumbents and enables differentiated service models. One risk is that integration complexity may raise barriers for smaller customers, potentially slowing diffusion of advanced recyclable formats in price-sensitive segments unless financing, training, and transition support evolve alongside the technology.
Strategic Guidance for Decision-Makers
For manufacturers, brand owners, and investors, the current environment rewards proactive positioning across material strategy, regional capacity planning, and supplier selection.
-
Manufacturers and converters should prioritize recyclable structure readiness before regulatory deadlines tighten. Investing in material testing, recycling stream validation, and design-for-recycling documentation can reduce future redesign costs and improve negotiating leverage with brand owners. Where aluminum replacement is technically feasible, piloting should be paired with line compatibility checks to ensure that new substrates perform reliably on existing filling equipment.
-
Brand owners and procurement leaders should treat supplier evaluation as a compliance-and-performance decision, not just a cost decision. Criteria should include recyclability pathway clarity, regional capacity proximity, quality assurance discipline, and ability to support format transitions. Diversifying the supplier base across scale incumbents, regional producers, and specialized format providers can improve resilience while preserving access to advanced solutions.
PW Consulting -
Investors and strategic planners should focus on companies demonstrating coordinated moves across materials, capacity, and application breadth. The strongest positioning is likely to belong to firms that can combine recyclable format leadership with regional production alignment and supportive equipment or service ecosystems. Monitoring capacity announcements, pilot plant outcomes, and regulatory milestone progress will provide early signals of which players are converting innovation into commercially scalable advantage.
The aseptic packaging market is entering a phase where growth and restructuring occur simultaneously. Demand expansion provides a favorable backdrop, but the real strategic value will be captured by those who anticipate material compliance requirements, align capacity with regional demand realities, and select partners capable of delivering both performance and transition support. Detailed segmentation data, regional nuances, and tailored scenario planning can sharpen these choices further for organizations preparing investments or portfolio decisions.
For detailed analysis of this topic, please visit the official page: Aseptic Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


