



First Aid Kits Market: Why 4.2% CAGR and $284M in 2032 Redefine Growth

Strategic Shifts and Commercial Opportunities in the First Aid Kits Market
The first aid kits market has evolved from a commodity-driven safety staple into a strategically differentiated segment where compliance, content innovation, and service models dictate competitive advantage. Valued at approximately $215.0 million in 2025 and projected to reach $284.0 million by 2032, the market reflects a compound annual growth rate of 4.2 percent over the 2026–2032 forecast period. This trajectory is not merely a function of population growth or baseline safety demand; it is being reshaped by regulatory realignment, supply chain pressures, and a structural shift toward specialized, application-specific kits. For executives, investors, and procurement leaders, the current environment presents both operational complexity and clear avenues for margin expansion if positioned correctly.
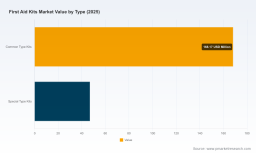
Understanding where value is created requires looking beyond headline revenue figures. The market's expansion is uneven across types and applications, with common-type kits continuing to anchor volume while special-type kits capture higher unit margins through specialized content and targeted use cases. Application-wise, industrial and commercial environments remain central demand centers, but home care and sports-related deployments are gaining relevance as safety awareness broadens beyond traditional workplaces. Regionally, mature markets continue to set compliance benchmarks, while emerging regions are expanding at a faster pace as regulatory frameworks and workplace safety cultures mature. This fragmentation is not a weakness; it is the structural basis for differentiated go-to-market strategies.
Market Snapshot and Structural Realities
The growth path from 2020 through 2025 demonstrates steady accumulation, with revenue moving from $163.15 million to $215.0 million. The forecast window extends that momentum, reaching $227.94 million in 2026 and climbing toward $284.0 million by 2032. While the overall CAGR of 4.2 percent suggests a mature, predictable market, the underlying pattern reveals inflection points. Growth is not linear; it is being accelerated in segments where regulatory mandates, specialized content, and managed replenishment models intersect. This is why the market's midpoint values matter less than the rate of change within specific applications and kit types.
The industry structure also reflects a moderate degree of concentration. The top three players account for roughly 42.5 percent of market share, while the top five reach approximately 58.7 percent. This concentration indicates that scale, distribution reach, and compliance expertise provide meaningful defensive moats. At the same time, the remaining share distribution leaves room for specialized entrants, private-label partners, and service-led models to compete on differentiation rather than price alone. For decision-makers, the implication is clear: the market rewards players who can align product content, regulatory readiness, and replenishment reliability rather than those who compete purely on kit count or unit cost.
Key Challenges and Inflection Points
The first aid kits market is navigating a set of interdependent challenges that will determine which players gain share and which are squeezed into low-margin commoditization. These challenges are not transient; they are structural and require strategic responses.
- Regulatory and standards realignment is raising the compliance floor. Recent revisions to first-aid kit specifications and quality management expectations are reshaping what qualifies as an acceptable kit in workplace and industrial settings. Compliance is shifting from a static checkmark to an ongoing operational requirement, increasing the importance of documentation, content consistency, and manufacturing discipline.
- Input cost volatility is compressing margins for undifferentiated products. Prices for medical-grade gloves, antiseptic consumables, and trauma care materials rose by nearly 18 percent between 2023 and 2025, driven by supply concentration in Asia and elevated freight costs. Manufacturers and distributors that rely on generic content structures or reactive sourcing are facing margin pressure that cannot be fully passed through to price-sensitive buyers.
- Demand fragmentation is making one-size-fits-all kits less defensible. Buyers increasingly expect kits aligned to specific risk profiles, occupancy types, and operational environments. The broad-volume play is losing differentiation value, while application-tailored kits, replenishment services, and rental or managed stock models are gaining relevance.
Together, these dynamics create a market where compliance readiness, content precision, and service integration are becoming the primary levers of competitive advantage. Companies that treat first aid kits as a simple resell or assembly business will face intensifying pressure, while those that embed quality systems, tailored content, and replenishment reliability into their offering will be better positioned to defend pricing and expand share.
Key Drivers Reshaping the First Aid Kits Market
The market's direction is being shaped by four interlocking drivers: regulatory and standards evolution, input cost and supply chain dynamics, demand-side behavior changes, and product and service innovation. Each driver influences not only volume but also the economics of competition.
Regulatory and Standards Evolution as a Structural Driver
Regulatory developments are no longer peripheral; they are actively redefining product eligibility and manufacturing expectations. The Quality Management System Regulation (QMSR) became effective in February 2026, aligning FDA CGMP requirements with ISO 13485:2016 for medical devices, including first aid kits. This shift matters because it connects first aid kit production more directly to internationally recognized quality management expectations. For manufacturers, the change raises the importance of documented processes, traceability, and consistent quality control. For buyers, it increases confidence in supplier reliability but also raises the bar for supplier qualification.
At the same time, state-level standards activity is pushing kit specifications toward more defined performance expectations. Recent proposals to revise first-aid kit requirements in California have pointed toward alignment with ANSI/ISEA Z308.1-2021 Class A specifications for 2026 compliance. Even where such revisions are still evolving, they signal a broader direction: kit content is being evaluated against more explicit benchmarks rather than generic notions of adequacy. This creates a dual effect. It rewards manufacturers that can demonstrate specification alignment and documented quality systems, while increasing the cost of remaining in the low-compliance segment.
Worldwide Antiseptic First Aid Liquid Market
For commercial strategy, the regulatory driver is best understood as a filter. It does not automatically expand the market, but it accelerates consolidation among suppliers that can meet higher compliance expectations and squeezes out marginal players that cannot sustain the required documentation and process discipline.
Input Cost Dynamics and Supply Chain Realities
Cost structure is becoming a strategic variable rather than a background assumption. The nearly 18 percent increase in prices for medical-grade gloves, antiseptic consumables, and trauma care materials between 2023 and 2025 reflects a combination of supply concentration and freight pressure. This is not simply a purchasing challenge; it influences product architecture, pricing strategies, and the viability of low-differentiation kits.
The most exposed players are those with limited sourcing flexibility and minimal content optimization. When input prices rise, the temptation is to pass costs downstream, but in price-sensitive segments that approach can erode demand or trigger substitution. More resilient players are managing the pressure through a combination of supplier diversification, content rationalization, and value-based packaging. In practice, this means rethinking what goes into a kit, how consumables are replenished, and whether certain items can be sourced or configured in ways that reduce volatility without compromising compliance or functionality.
Supply chain concentration also increases the strategic value of inventory planning and replenishment design. Kits that depend on fragile sourcing paths are vulnerable not only to cost shocks but also to availability disruptions. This is one reason managed replenishment, rental systems, and private-label partnerships are gaining attention: they shift part of the burden of continuity from the end buyer to the supplier, creating a more predictable operating model and a stronger customer relationship.
Demand-Side Shifts in Behavior and Expectations
Demand is changing in ways that favor application specificity and service reliability. Workplace safety expectations are rising, and buyers are increasingly aware that compliance alone is not the same as operational readiness. In industrial and commercial environments, the question is no longer just whether a kit is present, but whether its content matches the actual risk profile of the site, whether it is maintained, and whether replenishment happens without delay.
Home care and sports-related applications are also contributing to broader demand diversification. These segments may not carry the same regulatory weight as industrial settings, but they are expanding the addressable market and encouraging product designs that are easier to use, easier to store, and more intuitive for non-specialist users. The common thread across these demand shifts is that buyers are paying more attention to usability, maintenance, and relevance. Kits that are difficult to restock, poorly matched to real-world use, or opaque in their replenishment process lose credibility quickly.
This demand evolution also affects purchasing behavior. In some contexts, buyers are moving from one-time purchases toward ongoing service relationships. Managed restocking, cabinet solutions, and rental or replenishment programs reduce the administrative burden on buyers and create recurring revenue streams for suppliers. The shift is incremental but meaningful because it changes the economic logic of the market from transactional volume to relationship-based continuity.
Product and Service Innovation as a Competitive Lever
Innovation in this market is less about radical product reinvention and more about precision, usability, and service integration. Special-type kits illustrate this trend by targeting specific scenarios with content designed for higher-acuity needs. Trauma-oriented kits, bleeding control kits, and other specialized configurations are gaining attention because they address use cases where generic kits are insufficient. This does not replace the role of common-type kits, but it creates a higher-value layer in the market where differentiation is easier to sustain.
PW Consulting Health Care Research Center
Service models are also evolving. Wholesale distribution, private-label and contract manufacturing, and managed rental or restocking systems reflect a broader move toward integrated offerings. These models matter because they address multiple buyer pain points at once: compliance, content relevance, replenishment reliability, and administrative burden. Where successful, they create stickier customer relationships and more predictable revenue than standalone kit sales.
Innovation is also visible in how suppliers position themselves for different buyer types. Some players emphasize cost-effective OSHA-compliant workplace kits and refills, which appeal to buyers focused on baseline compliance and operational efficiency. Others prioritize ANSI/OSHA-compliant workplace, industrial, and construction kits, signaling a more specification-driven approach. A further group concentrates on trauma and public-access bleeding control kits, targeting higher-risk environments and first-response needs. Another set of suppliers focuses on premium kits selected by first responders and medical professionals, using clinical credibility as a differentiator. Taken together, these positions show that the market is no longer competing on a single value proposition; it is fragmenting into multiple value pools, each with its own buyer expectations and pricing logic.
Competitive Landscape and Winning Strategies
The competitive field is marked by a mix of scale players, compliance-focused suppliers, specialized trauma-oriented providers, and service-oriented distributors. The presence of established names alongside niche specialists suggests a market where different competitive models can coexist, but only if each is clearly aligned to a defensible position.
Strategic Positioning Among Leading Players
A closer look at leading players shows that competitive advantage is being built through distinct positioning rather than uniform product offerings.
- First Aid Only has leaned into cost-effective, OSHA-compliant workplace kits and refills. This positions the company around baseline compliance, operational simplicity, and replenishment continuity for workplace environments. The strategic value lies in serving buyers who need dependable, specification-aligned kits without unnecessary complexity.
- The American Red Cross emphasizes ANSI/OSHA-compliant workplace, industrial, and construction kits. Its positioning benefits from institutional credibility and a strong association with safety and preparedness. In markets where trust and recognized authority matter, this is a meaningful advantage.
- North American Rescue focuses on trauma and first aid kits, including lumbar first aid kits and public access bleeding control kits. This places the company in a higher-specialization segment where content precision and mission-relevant design can support premium positioning.
- Aero Healthcare operates across wholesale kits, private-label and contract manufacturing, and managed rental or restocking systems. This multi-track model is strategically important because it combines distribution reach with service-based revenue and custom branding opportunities.
- My Medic emphasizes premium first aid kits and supplies selected by first responders and medical professionals. Its differentiation rests on clinical credibility and curated content, appealing to buyers who value expert selection and higher-performance configurations.
- Cintas Corporation offers first aid kits, cabinets, and replenishment services for workplace use. The strength of this model is integration: by combining hardware, kits, and replenishment, it reduces fragmentation for buyers and creates recurring service relationships.
- JumpMedic concentrates on premium first aid kits and supplies designed for emergency needs. Its positioning targets urgent-use scenarios where readiness, usability, and content reliability are especially important.
The pattern across these players is not random. Each is pursuing a distinct value pool: compliance and efficiency, institutional trust, trauma specialization, service integration, clinical credibility, or emergency readiness. The market supports multiple models because buyer needs differ by environment, risk profile, and procurement style. What separates stronger performers from weaker ones is the ability to deliver consistently on the chosen position without diluting it through unrelated expansion.
How the Landscape Is Evolving
The competitive landscape is evolving along three axes: consolidation among scaled players, differentiation among specialists, and new entry through service-led and private-label models.
Consolidation remains plausible where scale, distribution reach, and compliance infrastructure create advantages in procurement, qualification, and ongoing account management. In a market where the top five players already account for a majority share, further consolidation would likely be driven by the need to strengthen replenishment networks, broaden application coverage, and absorb regulatory and quality-system requirements more efficiently.
At the same time, differentiation is intensifying among specialists. Trauma kits, bleeding control kits, premium responder-selected kits, and application-specific configurations are creating spaces where performance and credibility matter more than sheer volume. These segments are smaller in absolute terms but can support stronger margins and more loyal customer bases when executed well.
New entry is also emerging through service-oriented models and private-label partnerships. Buyers that want compliance, replenishment, and brand alignment without building internal complexity are natural candidates for rental, restocking, and contract manufacturing arrangements. This creates opportunities for suppliers that can combine operational reliability with flexible commercial terms, even if they do not lead in raw brand recognition.
The overall trend is toward a market where success depends less on being everywhere and more on being unambiguously strong in a chosen segment. Players that attempt to compete across all applications, all kit types, and all service models without clear prioritization risk being outflanked by more focused competitors.
Forward Outlook: Three Trends to Watch Over the Next 3–5 Years
Looking ahead, the market is likely to be shaped by the interaction of compliance, cost, and demand specificity. Three trends are especially relevant for strategic planning.
Trend 1: Compliance and Quality Systems Will Become Table Stakes, Not Differentiators Alone
As quality management expectations align more closely with recognized international standards and kit specifications continue to be refined, the baseline for market participation will rise. This does not automatically create growth, but it does change the competitive filter. Suppliers that can demonstrate consistent quality, documentation discipline, and specification alignment will face lower qualification friction and stronger buyer confidence. Those that cannot will find it increasingly difficult to remain viable in regulated workplace and industrial channels. The commercial implication is that compliance capability should be treated as core infrastructure, while differentiation will need to come from content relevance, service design, and segment focus.
Worldwide Home Safety Test Kits Market
Trend 2: Application-Tailored Kits and Managed Replenishment Will Capture More Value
Demand is moving toward kits that match real-world risk profiles and toward purchasing models that reduce maintenance burden. This favors suppliers that can design for specific environments, maintain stock reliability, and offer replenishment, rental, or cabinet-plus-service solutions. The opportunity is not only in selling more kits, but in shifting the relationship from transactional purchase to ongoing readiness. For manufacturers and distributors, this trend opens a path to recurring revenue and stronger account retention, provided the operational backbone can support reliable restocking and service execution.
Trend 3: Cost and Sourcing Strategy Will Separate Resilient Players from Marginal Ones
Input cost pressure is unlikely to disappear quickly, especially where supply concentration and freight exposure remain factors. The strategic response will matter more than the headline cost itself. Players that diversify sourcing, optimize content without sacrificing compliance, and build replenishment models that smooth volatility will be better positioned to protect margins. Those that rely on rigid supply paths or undifferentiated kit architectures will be more exposed to price competition and availability risk. Over the next few years, sourcing resilience and content architecture will increasingly determine who can sustain pricing power.
Risks and Uncertainties
These trends are directionally clear, but several uncertainties could alter the pace or shape of market development. Regulatory specifications may evolve unevenly across regions, creating compliance complexity for suppliers operating in multiple jurisdictions. Input cost volatility could intensify if supply concentration persists or if logistics costs rise again. Demand may also shift faster than expected in certain applications, particularly where safety awareness grows or where workplace and public-access preparedness requirements become more stringent. Finally, competitive intensity could increase if new entrants successfully use private-label, rental, or replenishment models to bypass traditional distribution barriers. Each of these risks can be managed, but only if they are anticipated rather than treated as external shocks.
Strategic Actions for Decision-Makers
The first aid kits market rewards clarity of position, operational discipline, and readiness to align product content with real-world use. The following actions are most relevant for different audience types.
For Manufacturers and Brand Owners
- Strengthen quality management and specification alignment as a foundation, not a side initiative. With regulatory expectations moving toward more formalized quality frameworks, the ability to document processes and demonstrate consistent compliance is becoming a market-access requirement.
- Reassess kit content architecture against input cost realities. Where possible, optimize consumables, diversify sourcing, and differentiate through application-specific configurations rather than relying on generic volume plays.
- Choose a defensible value pool and execute against it. Whether the focus is workplace compliance, trauma specialization, responder-selected premium kits, or service-led replenishment, clarity of positioning will matter more than broad but shallow coverage.
For Investors and Strategic Buyers
- Evaluate exposure to compliance-dependent channels and service-based revenue. Businesses with recurring replenishment, rental, or managed stock models may offer more predictable economics than pure transactional kit sales, especially if they can demonstrate reliable execution.
- Look for sourcing and content strategies that signal resilience. Suppliers with diversified supply paths, disciplined cost management, and clear segment focus are better positioned to withstand input price volatility and competitive pressure.
- Assess whether a target's differentiation is real or aspirational. In this market, credibility in specific applications and the ability to maintain specification alignment over time are stronger signals than broad brand claims.
For Procurement and Safety Leaders
- Shift evaluation criteria beyond unit price to include replenishment reliability, compliance documentation, and content relevance. The total cost of an inadequate or poorly maintained kit can exceed the apparent savings from a cheaper purchase.
- Align kit selection to actual site risk profiles and usage patterns. Over-specified kits can waste resources, while under-specified kits can create readiness gaps; the goal is fit, not maximum content.
- Consider service models where administrative burden and restocking risk are significant. Managed replenishment, cabinets, and rental or contract arrangements can improve continuity if the provider demonstrates reliable execution and clear compliance support.
The first aid kits market is entering a phase where strategy matters more than scale alone. Compliance expectations are rising, input costs are reshaping margins, and buyers are increasingly focused on readiness, relevance, and continuity. In that environment, the winners are likely to be those who combine quality discipline with clear segmentation, reliable replenishment, and content designed for real-world use. For organizations seeking a more detailed view of segment dynamics, regional variation, and tailored commercial options, a comprehensive research report can provide the deeper segmentation and scenario detail needed to translate these strategic signals into actionable plans.
For detailed analysis of this topic, please visit the official page: First Aid Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


