



Data Diodes Market: Why Secure Unidirectional Flow Drives 7.15% CAGR Toward $349M in Revenue

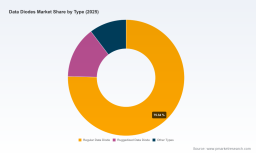
The Data Diodes Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Landscape: Size, Trajectory, and Structural Challenges
Data diodes have moved from niche secure-transfer tools into mainstream components of enterprise and critical infrastructure security postures. The market reached USD 215.75 million in 2025, having grown steadily from 160.25 million in 2020. Forward projections indicate a compound annual growth rate of 7.15 percent through 2032, with revenue expanding to USD 349.05 million by the end of the forecast period. This trajectory reflects a structural shift: organizations are no longer treating unidirectional transfer as an edge-case compliance requirement, but as a foundational layer for cross-domain data exchange, operational technology isolation, and forensic integrity.
The growth curve is not uniform. Historical momentum from 2020 to 2025 was supported by defense modernization programs, energy sector cybersecurity mandates, and early industrial automation deployments. From 2026 onward, the pace accelerates as data diodes embed into broader security architectures, not as standalone hardware purchases but as integrated safeguards within OT/IT bridging, cloud replication, and incident response workflows. The market’s resilience across economic cycles underscores a key insight: data diodes solve a persistent, non-negotiable problem—secure one-way movement of information between networks with differing trust levels—and that problem is only expanding as connectivity widens.
Key Challenges and Inflection Points
Three structural challenges are shaping how the market evolves and where commercial value concentrates.
First, the tension between assurance and usability. Customers increasingly demand diodes that deliver hardware-enforced one-way transfer without imposing heavy operational burdens. Traditional deployments required meticulous protocol matching, manual rule sets, and specialized integration expertise. Newer solutions are compressing that complexity, but the bar for "plug-and-play" assurance remains high, especially in defense, rail, water, and industrial control environments where failure is not an option. The inflection point is arriving as vendors pair physical unidirectionality with protocol-level intelligence, allowing organizations to preserve security while reducing deployment friction.
Second, the labor and process cost of legacy data handling. Manual transport and retrieval of physical media for data movement carries annual costs ranging from USD 2,100 to USD 10,000 per workflow, with labor-intensive processes that are error-prone and difficult to scale. As organizations digitize operations and expand cross-domain data sharing, these manual workarounds become unsustainable. The challenge for buyers is not only switching to automated unidirectional transfer, but doing so in a way that integrates with existing SCADA, historian, and cloud replication pipelines without creating new operational silos.
PW Consulting Information & Electronics Research Center
Third, certification and regulatory alignment as both enabler and gatekeeper. Data diodes align with guidance such as NIST 800-82 for unidirectional gateways in OT/ICS environments, helping prevent lateral movement in critical infrastructure. At the same time, government and defense buyers require validated, often certified, assurance levels that vary by jurisdiction and classification. This creates a dual dynamic: regulation expands the addressable market by mandating stronger isolation, while certification requirements raise the entry threshold for new suppliers and slow procurement in highly regulated segments. The market is therefore bifurcating between high-assurance, certified solutions for government and defense, and more agile, lower-friction offerings for commercial OT and enterprise IT.
Core Drivers Shaping the Market
Technological Innovation and Breakthroughs
The most consequential technical shift is the fusion of hardware-enforced unidirectionality with protocol filtering and software-defined integration. Early data diodes prioritized raw one-way transfer, often at the cost of protocol compatibility and operational visibility. Recent product moves show a clear pivot toward intelligent unidirectional gateways that understand specific protocols, filter traffic at the hardware or firmware level, and interoperate with operational software stacks. This reduces the need for custom middleware and allows organizations to move operational data from OT to IT or cloud environments with assurance intact.
A second innovation vector is form factor and deployment flexibility. Pocket-sized incident response diodes for forensic evidence collection, card modules for embedded applications, and DIN-rail appliances for industrial networks illustrate how vendors are tailoring hardware to specific use cases rather than offering one-size-fits-all appliances. This modularity is expanding adoption beyond large, centralized security projects into edge, trackside, and distributed industrial settings where space, ruggedness, and rapid deployment matter.
A third vector is assurance certification paired with performance. Solutions validated for high-assurance one-way transfer at speeds up to 100 Gbps demonstrate that security and throughput are no longer traded off. For buyers, this matters because high-speed cross-domain replication is increasingly required for real-time operational monitoring, centralized analytics, and disaster recovery workflows that cannot tolerate latency or manual handoffs.
Policy and Regulatory Environment
Policy is a primary demand accelerator. In OT and ICS environments, guidance that emphasizes unidirectional gateways to prevent lateral movement directly supports data diode adoption. In government and defense, validated protocol filtering and classification-grade certifications create procurement pathways for suppliers that meet stringent assurance requirements. The practical effect is twofold: regulators and standards bodies are normalizing unidirectional transfer as a best practice, and certified products are gaining preferential access to high-value public sector and critical infrastructure contracts.
At the same time, regulatory diversity creates fragmentation. Different jurisdictions and program offices emphasize different certification regimes, from national armed forces standards to common criteria evaluation assurance levels and sector-specific OT guidance. Suppliers that can navigate this mosaic—and articulate how their hardware and software stack maps to each requirement—are gaining trust and shortening sales cycles in regulated segments. Buyers, conversely, are increasingly specifying assurance requirements up front, which rewards suppliers with transparent certification posture and documented integration paths.
Demand-Side Shifts in Enterprise and Industrial Behavior
Demand is expanding beyond defense and government into commercial OT, energy, water, manufacturing, and rail. Several behavioral shifts are driving this. Organizations are moving from periodic, manual data exchange to continuous, automated operational data replication for monitoring, analytics, and cloud integration. They are also treating cross-domain transfer as a design-time requirement rather than a retrofit, embedding unidirectional safeguards into network segmentation strategies from the outset.
In industrial settings, the rise of protocol-aware appliances that support OPC UA and MQTT reflects a demand for secure, standards-based connectivity between operational networks and higher-level IT or cloud systems. In water and wastewater, integrations with SCADA software illustrate demand for reliable one-way transfer that preserves operational integrity while enabling centralized visibility. In rail, trackside-specific diodes compliant with sector standards show demand for rugged, low-maintenance solutions in harsh, distributed environments. Across these cases, the common thread is trust: organizations want to share data outward without exposing inward paths, and they want to do so without rebuilding operational workflows.
Supply Chain and Cost Structure Dynamics
Cost dynamics are shifting from pure hardware price to total cost of ownership and operational efficiency. Manual data transport workflows carry hidden costs in labor, error risk, and scheduling overhead, which makes automated unidirectional transfer attractive even before considering security benefits. Suppliers that reduce deployment complexity, minimize software dependencies, and integrate with existing operational tools are lowering the practical cost of adoption.
On the supply side, ruggedized hardware and certified components introduce procurement complexity, but they also create differentiation. Vendors that combine TEMPEST and RÖS-grade rugged data diodes, card modules, and tamper-proof hardware with clear certification documentation are positioning themselves for segments where assurance outweighs cost sensitivity. Meanwhile, commercial OT and enterprise buyers are increasingly weighing ease of deployment, protocol compatibility, and integration support alongside raw assurance, creating room for differentiated offerings that optimize for different buyer priorities.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the top three players holding roughly 26.5 percent of revenue and the top five approaching 32.8 percent. This concentration indicates a fragmented but maturing field: established specialists hold meaningful share in high-assurance segments, while a broader set of entrants competes on integration, usability, and vertical-specific fit. The strategic question for buyers and investors is not who leads today, but which differentiation paths will compound over the next several years.
Strategic Positioning and Differentiation Among Leading Players
Owl Cyber Defense has built a strong U.S. government-aligned position around protocol filtering diodes and incident response diodes for high-assurance one-way transfer. Its February 2026 validation of the Talon Torrent as an approved protocol filtering diode for reliable one-way transfer up to 100 Gbps signals that throughput and assured filtering can coexist. The May 2026 launch of a pocket-sized incident response diode for forensic evidence collection from compromised endpoints using USB with hardware-enforced one-way protocol filtering shows a move toward portable, task-specific assurance. The June 2026 integration of VTScada SCADA software with data diodes for secure one-way operational data transfer from OT to IT/cloud in water and wastewater deployments in Houston and Nashville illustrates a push into vertical-specific, software-integrated deployments.
OPSWAT positions around unidirectional gateways that couple data diode hardware with file sanitization and cross-domain secure data replication for IT/OT isolation. Its MetaDefender Optical Diode and related offerings emphasize content-aware protection at the transfer boundary, which appeals to buyers who want assurance plus malware handling and content control in one workflow. This strategy broadens the use case beyond pure unidirectionality into content security, which can reduce the number of discrete tools an organization must integrate.
Rectifier Diode Market
Fibersystem AB and Advenica represent the high-assurance, ruggedized flank of the market. Fibersystem focuses on TEMPEST Level A+ and RÖS U1 rugged data diodes and card modules for secure, high-assurance one-way transfer, targeting environments where electromagnetic emissions and physical hardening matter. Advenica offers a family of data diodes with N3 Swedish Armed Forces certification for top-secret to qualified secret levels, signaling deep government-grade assurance. Advenica’s March 2026 launch of a data diode engineered for railway trackside applications, compliant with EN railway standards and requiring no additional security software, shows how assurance players can expand into vertical-specific, low-maintenance deployments without sacrificing certification posture.
Patton Electronics emphasizes industrial network fit with the FiberPlex FP-DD100 DIN-rail ultra-secure data diode, supporting OPC UA and MQTT protocols. Its October 2025 launch reflects a strategy of embedding unidirectional transfer into industrial automation infrastructures where protocol compatibility and form factor are decisive. BAE Systems brings Common Criteria EAL 7+ certified data diode solutions for secure cross-domain transfer between networks of differing trust levels, leveraging defense-scale credibility and high assurance evaluation. Waterfall Security Solutions combines hardware diodes with software for industrial OT/ICS environments, operationalizing unidirectional transfer within broader industrial security architectures.
ST Engineering offers endpoint data diodes certified with CC EAL 4+ and NITES for industrial and defense use, balancing assurance with accessibility. Nexor provides tamper-proof hardware data diodes for secure classified information transfer between trusted and untrusted networks, reinforcing a classified-transfer niche. Garland Technology contributes data diode TAPs for one-way raw data flow in industrial and network monitoring applications, extending unidirectional concepts into visibility and segmentation infrastructure. Valiant Communications supplies hardware data diodes for secure one-way network communication in cybersecurity environments, while Everfox focuses on unidirectional data diode solutions for cross-domain secure transfers with reduced TCO and easy deployment, explicitly targeting cost and operational simplicity.
Market Evolution: Integration, Specialization, and New Entrants
The competitive landscape is evolving along three vectors. First, integration is becoming a primary differentiator. Suppliers that pair hardware unidirectionality with protocol intelligence, SCADA or historian integration, and content security are capturing buyers who want fewer integration points and clearer operational outcomes. Second, specialization by vertical and environment is sharpening. Rail, water, industrial automation, and defense each impose distinct standards, environmental constraints, and assurance expectations, rewarding vendors that engineer for those contexts rather than offering generic appliances. Third, new entrants and adjacent players are competing on usability and TCO, particularly in commercial OT and enterprise settings where deployment speed and integration effort matter as much as certification.
ESD Protection Diode Market
Consolidation pressure is likely to increase as larger security and industrial technology firms seek to own the cross-domain transfer layer within broader platforms. At the same time, fragmentation will persist because assurance requirements, environmental ruggedness, and vertical standards create niche moats. The practical implication is that buyers will encounter both platform plays and specialist solutions, and the right choice will depend on whether the priority is high-assurance certification, vertical fit, or rapid integration with existing operational tooling.
Forward Outlook: Three Trends to Watch (2026–2032)
Trend 1: From Point Solutions to Embedded Cross-Domain Architectures
Data diodes are shifting from standalone appliances to embedded components within cross-domain architectures. Buyers increasingly expect unidirectional transfer to interoperate with operational software, cloud replication, and network segmentation frameworks. This trend expands the addressable need because it turns data diodes from a compliance checkbox into a design element for secure data movement across OT, IT, and cloud domains. Commercial opportunities will accrue to suppliers that offer validated integration paths, reference architectures, and vertical-specific templates that reduce deployment risk. The risk is that integration breadth can outpaced assurance depth if vendors overpromise compatibility without rigorous validation.
Trend 2: Protocol-Aware, High-Throughput Assurance Becomes Table Stakes in Regulated Segments
High-assurance one-way transfer at speeds up to 100 Gbps, combined with hardware-enforced protocol filtering, is becoming a baseline expectation in defense and critical infrastructure. As operational data volumes grow and real-time monitoring becomes standard, organizations cannot afford latency or manual handoffs. The opportunity lies in solutions that preserve assured unidirectionality while supporting the protocols and throughput that modern operations demand. The uncertainty is regulatory: as standards evolve, certification requirements may tighten or diversify, affecting which products qualify for high-value contracts and how quickly procurement cycles move.
Trend 3: Vertical-Specific, Ruggedized, and Low-Maintenance Deployments Expand the Addressable Market
Trackside rail diodes, DIN-rail industrial appliances, pocket-sized forensic diodes, and rugged card modules illustrate a broader move toward environment-specific, low-maintenance deployments. This trend opens markets that were previously underserved by high-end, centralized appliances, including distributed industrial sites, remote operational environments, and incident response scenarios that require rapid, portable evidence collection. The commercial upside is volume growth in verticals that value ruggedness, standards compliance, and minimal software dependency. The downside risk is supply complexity: ruggedized and certified variants can raise manufacturing and procurement overhead, and vertical standards may differ enough to fragment product lines.
Strategic Recommendations for Decision-Makers
For Manufacturers and Technology Providers
- Align product roadmaps with protocol-aware, high-throughput assurance and vertical-specific form factors. Customers in OT, rail, water, and industrial automation are prioritizing deployment fit and integration readiness alongside assurance, so differentiated value will come from validated protocol support, ruggedized options, and reference integrations.
- Invest in certification transparency and integration documentation. In regulated segments, the ability to map hardware and software to relevant assurance frameworks shortens evaluation cycles and builds trust. Clear documentation of how a solution supports unidirectional gateways in OT/ICS contexts and meets sector-specific standards reduces buyer risk.
- Balance platform breadth with niche moats. Consider whether to pursue integrated cross-domain platforms or deepen vertical and environmental specialization. Both paths can work, but clarity of positioning matters more than breadth alone.
For Investors
- Focus on suppliers that combine assurance with usability and vertical fit. The market’s growth is increasingly driven by integration, protocol intelligence, and environment-specific deployments, so companies that reduce operational friction while preserving hardware-enforced security are better positioned to capture recurring and expanded deployments.
- Watch certification milestones and government-validated approvals as catalysts. Validated protocol filtering diodes and classification-grade certifications can unlock high-value segments and improve competitive positioning, making them meaningful indicators of near-term demand potential.
- Assess total cost of ownership narratives, not just hardware pricing. Solutions that lower manual process costs, simplify deployment, and reduce software dependency can win in commercial OT and enterprise settings where buyers weigh operational efficiency alongside security.
For Procurement and Security Leaders
- Define assurance requirements and integration needs up front. Specify the trust levels, certification expectations, protocols, and operational software interfaces that matter for your environment. This reduces evaluation risk and helps suppliers propose solutions that fit rather than forcing generic compromises.
- Treat unidirectional transfer as part of network segmentation strategy, not an isolated purchase. Data diode TAPs and unidirectional gateways can support raw data flow and lateral movement prevention when embedded thoughtfully into segmentation designs, improving both security and operational visibility.
- Evaluate total cost and operational impact, including legacy manual processes. Automated one-way transfer can reduce labor-intensive handling and error risk, so consider the full workflow cost when comparing solutions. Solutions that minimize additional security software dependencies may be preferable in rugged or distributed environments where maintenance overhead is a concern.
Closing Perspective
The data diodes market is entering a phase where growth is driven less by isolated security purchases and more by the embedding of unidirectional transfer into cross-domain, vertical-specific, and operationally integrated architectures. The numbers tell a clear story of expansion, but the strategic story is about fit: assurance that matches the environment, protocol intelligence that matches the workflow, and deployment models that match the operational reality. As certification requirements evolve, vertical standards tighten, and integration expectations rise, the suppliers and buyers who succeed will be those who treat unidirectional transfer as a design principle rather than a point solution. For decision-makers seeking detailed segmentation data, regional nuances, and tailored recommendations, the full research report provides the deeper breakdown needed to align investment and procurement decisions with the market’s direction.
For detailed analysis of this topic, please visit the official page: Data Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


