



Spray Dryer Market 2026: Why 6.51% CAGR and Food & Dairy Applications Reshape Competition

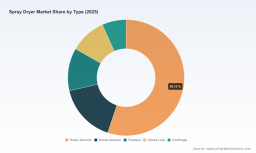
The Spray Dryer Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
The global spray dryer market has transitioned from a mature, steady-growth segment into a strategically contested space where capital intensity, regulatory tightening, and end-market demand shifts are reshaping competitive dynamics. Between 2020 and 2025, total market revenue expanded from approximately USD 4.6 billion to USD 6.6 billion, reflecting a compound annual growth rate of roughly 6.5 percent. Forward projections indicate that the segment will approach USD 8.3 billion by the end of the decade and surpass USD 10.2 billion by 2032. This trajectory is not merely a function of incremental capacity additions; it signals a structural revaluation of spray drying as a critical enabling technology across food, pharmaceutical, and specialty chemical production. For executives and investors, the central question is no longer whether demand will grow, but where margin pools will form, which technological pathways will win, and how regulatory and cost pressures will filter the competitive field.
Market Size, Growth Profile, and Structural Constraints
The revenue expansion observed over the past half-decade has been uneven, with a pronounced acceleration in the most recent years followed by a continued upward slope into the forecast window. The 2025 baseline of USD 6.59 billion anchors a forecast period that projects sustained mid-single-digit to high-single-digit growth through 2032. This scale places the market in a position where individual flagship installations can move the needle for equipment vendors, while recurring demand for retrofits, capacity expansions, and process upgrades creates a multi-layered revenue stream. The growth is broad-based across application areas, but the composition matters: food and dairy applications remain the largest revenue pool, pharmaceutical spray drying represents a high-value, compliance-intensive segment, and chemical and specialty applications contribute a smaller but strategically important share tied to ingredient engineering and material science.
Despite the favorable top-line trajectory, the industry faces structural friction that will define investment returns over the next several years. First, spray drying remains an energy-intensive process, and large-scale equipment often carries capital and operating costs that run into multiple millions of dollars. In an environment where industrial energy prices, carbon compliance, and total cost of ownership are scrutinized more closely, buyers are increasingly evaluating not just throughput but lifecycle economics. Second, effective operation demands trained personnel for maintenance, cleaning, and sanitation to preserve product quality and safety. As labor availability and skill constraints tighten in several industrial markets, the operational burden of complex drying lines becomes a hidden cost driver that influences procurement decisions and vendor selection. Third, the market exhibits meaningful concentration, with a small group of established players commanding a substantial share of revenue. This concentration creates both stability and friction: incumbents benefit from installed bases, service relationships, and scale, while newer or smaller entrants face higher barriers to displace them without a clear technology or cost advantage.
Food Dryer Market
Key Challenges and Turning Points
The market is currently navigating three interrelated turning points that will separate resilient operators from those left behind. The first is the growing tension between throughput ambition and sustainability expectations. Buyers are expanding production to capture demand in dairy powders, instant coffee, and emerging plant-based ingredients, yet they are simultaneously pressured to reduce energy intensity, water consumption, and waste. Equipment that cannot demonstrate measurable efficiency gains or that complicates compliance with environmental and quality standards risks becoming a liability rather than an asset. The second turning point is regulatory harmonization and its operational implications. Recent rule changes that align quality management expectations with recognized international standards for medical device and pharmaceutical manufacturing have raised the bar for documentation, validation, and process control. For spray dryer vendors and end-users alike, this means that engineering excellence alone is insufficient; systems must be designed, qualified, and operated within validated design spaces that satisfy increasingly rigorous oversight. The third turning point is the shift from standardized equipment purchases toward integrated, application-specific solutions. End-users are less interested in commoditized drying capacity and more focused on achieving consistent particle morphology, moisture control, and throughput stability tailored to their formulations. This shift rewards vendors who can combine atomization precision, automation, and process analytics into a coherent solution, while penalizing those who compete primarily on baseline specifications.
Key Drivers Shaping the Spray Dryer Market
Technological Innovation and Process Control
Technology differentiation is becoming the primary lever for margin protection and competitive separation. Advanced atomization methods, improved heat recovery, and tighter integration of process analytics are redefining what a spray dryer can deliver beyond simple drying. In pharmaceutical and high-value food applications, particle size distribution, bulk density, and reconstitution behavior are decisive quality attributes, and equipment that can hold these parameters within narrow tolerances commands a premium. The rise of automated control architectures and real-time monitoring is reducing variability and shortening qualification cycles, which matters enormously in regulated environments where design space optimization and process validation are mandatory. Recent equipment activity underscores this direction: a major supplier introduced an advanced pharmaceutical spray dryer to a prominent biologics manufacturer to strengthen product development and manufacturing capabilities, signaling how targeted technology deployment can open high-value account relationships. At the same time, laboratory and pilot-scale installations continue to play a strategic role, with research institutions and advanced materials groups commissioning new drying units to separate solids from liquids or suspensions into powder with greater efficiency and reproducibility. These smaller-scale deployments are not merely academic; they feed the innovation pipeline that later scales into commercial lines, making pilot equipment a leading indicator of where application technology will move next.
Policy, Regulatory Environment, and Quality Expectations
The regulatory backdrop is reshaping procurement criteria and vendor qualification processes. The effective integration of recognized quality management system standards for medical device manufacturers, including spray dryers used in pharmaceutical production, has elevated expectations for documentation, traceability, and validated operating envelopes. In parallel, guidelines emphasizing process validation and design space optimization for pharmaceutical spray drying require vendors and operators to demonstrate that their processes can consistently deliver quality outcomes within defined parameters. These requirements are not isolated compliance exercises; they influence capital planning, installation timelines, and the total cost of ownership. Buyers are increasingly factoring in the cost of qualification, the risk of rework, and the operational burden of maintaining auditable records. For equipment makers, this environment favors organizations that can embed quality-by-design principles into their hardware and software, provide robust validation support, and maintain long-term service relationships that help clients sustain compliance over multi-year lifecycles. The regulatory trend also raises the stakes for cross-border sourcing, as manufacturers evaluate whether equipment and support from different regions can meet the documentation and oversight expectations of the markets they serve.
PW Consulting Automotive & Machinery Research Center
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand is being reshaped by both consumer-facing trends and enterprise formulation strategies. In food and dairy, the continued expansion of shelf-stable powders, instant formats, and functional ingredients sustains core demand, while the emergence of plant-based and alternative protein ingredients adds new complexity to drying requirements. Formulators are seeking powders with specific solubility, dispersibility, and sensory profiles, which pushes equipment selection toward systems that can handle sensitive materials without thermal degradation and that can be cleaned and reconfigured efficiently. In pharmaceuticals, the drive toward more complex biologics, specialized intermediates, and precise delivery forms increases the value of drying processes that preserve activity and deliver repeatable quality. Enterprises are also placing greater emphasis on supply chain resilience and regional production footprints, a shift that encourages capacity additions closer to end markets and favors vendors who can deliver localized engineering support, spare parts availability, and service responsiveness. The combined effect is a demand environment that values reliability, flexibility, and application expertise as much as raw capacity.
Supply Chain, Cost Structure, and Operational Realities
Cost structure is increasingly a strategic variable rather than a background condition. Because large-scale spray drying systems involve significant capital outlay and ongoing energy consumption, buyers are extending their evaluation windows to include installation risk, commissioning complexity, and long-term operating expense. Trained operators and maintenance teams are essential for regular cleaning, sanitation, and performance upkeep, which means labor skill constraints can directly affect availability and throughput. In this context, vendors that offer integrated automation, straightforward cleaning protocols, and predictable maintenance cycles can reduce hidden costs and improve customer economics. The supply side is also influenced by the geography of manufacturing and service networks. Established suppliers with strong regional presence can shorten lead times and improve responsiveness, while emerging manufacturers may compete on price or specialized features but must demonstrate reliability in execution and support to win and retain large accounts. Cost pressure does not necessarily compress the entire market uniformly; instead, it tends to bifurcate purchasing behavior, with some buyers optimizing for upfront price and others prioritizing total lifecycle value and risk reduction.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The market is anchored by a set of established companies that combine engineering heritage, application knowledge, and service infrastructure. A German-based group provides specialized spray drying solutions for dairy, food ingredients, pharmaceutical, and instant coffee production, emphasizing integrated plant designs and process know-how that extend beyond the dryer itself. A major U.S.-headquartered flow control and processing company offers spray dryer systems under a well-recognized brand for food, dairy, and pharmaceutical powders, with a focus on advanced atomization and process technology. A Swiss laboratory technology manufacturer manufactures laboratory and pilot-scale units for research, quality control, and small-scale pharmaceutical and chemical applications, positioning itself at the upstream end of the innovation and validation chain. A German engineering firm supplies customized industrial spray dryers for food, chemical, and starch industries, offering pilot to full-scale units built on decades of experience and a customization-first philosophy. A U.S.-based developer focuses on pulse atomization spray dryers aimed at energy-efficient drying across food, chemical, mineral, and pharmaceutical powders, differentiating through a specific energy-saving technology pathway. A Swiss packaging and processing solutions provider delivers automated spray drying systems for dairy, whey, and plant-based powders using wide-body technology, aligning drying equipment with broader integrated processing lines. A Chinese manufacturer produces milk and food spray dryers with precision engineering and automation tailored to dairy applications, reflecting the growing capability and regional demand base in Asia. A U.S. manufacturer supplies domestically produced spray dryers for starch, food, and industrial powder production, catering to customers that prioritize local engineering and supply chain continuity.
These companies are not competing on a single axis. Incumbents with broad application portfolios leverage installed bases, service networks, and cross-selling into upgrades and retrofits. Technology specialists compete by proving measurable advantages in energy efficiency, particle control, or process robustness. Laboratory and pilot-scale providers maintain a strategic foothold by supporting qualification, method development, and scale-up, which positions them as trusted partners when commercial projects move forward. The differentiation that matters most in the current environment is the ability to reduce variability, accelerate qualification, and support compliance over the life of the equipment, rather than simply offering competitive baseline pricing.
Worldwide Freeze Drier Market
Evolution of Market Structure
The competitive structure is evolving along two parallel tracks: consolidation of advantage among well-positioned incumbents, and selective entry by specialists targeting high-value niches. Concentration in the market remains significant, which means that large accounts often engage with a limited set of trusted suppliers for major capital projects. This dynamic reinforces the importance of reputation, reference installations, and the ability to deliver complex projects on schedule. At the same time, the demand for application-specific solutions and energy-efficient designs creates openings for companies that can demonstrate a clear performance edge or a compelling total cost proposition. Newer entrants and regional manufacturers are most likely to succeed where they can pair technical differentiation with reliable execution and after-sales support, rather than competing solely on hardware price. Over time, the market is likely to see further rationalization, with stronger players capturing share through integrated offerings and service-led relationships, while smaller players either niche down into specific applications or exit segments where scale and compliance costs are prohibitive.
Future Trends and Commercial Implications (2026–2032)
Trend One: Efficiency as a Default Requirement, Not a Bonus Feature
Energy intensity will move from a cost consideration to a design requirement. As buyers confront both operating expense pressure and sustainability expectations, spray drying systems that incorporate efficient heat recovery, optimized atomization, and lower standby losses will gain preference. This trend favors vendors that can quantify efficiency gains in operational terms and integrate those claims into a credible total cost narrative. Commercially, this creates opportunities for retrofits, control upgrades, and selective replacements that improve throughput per unit of energy, particularly in mature dairy and food ingredient facilities where marginal efficiency improvements translate directly into margin. The risk is that efficiency claims become a crowded field; differentiation will depend on verifiable performance data, installation reality, and the ability to maintain efficiency over time rather than only at commissioning.
Trend Two: Compliance-Integrated Equipment and Service Models
Regulatory expectations will continue to pull quality management deeper into equipment selection and operation. As pharmaceutical and related applications require validated design spaces, rigorous documentation, and consistent process control, the economic value of equipment that supports these requirements will rise. Vendors that can provide structured qualification support, auditable configuration management, and long-term service that helps clients sustain compliance will strengthen customer stickiness. This trend also encourages broader service and lifecycle contracts, where revenue is tied not only to hardware sales but to ongoing performance assurance and regulatory readiness. The uncertainty lies in the pace and specifics of regulatory evolution across regions, which can shift qualification burdens and affect project timelines. Companies that maintain regulatory flexibility and invest in documentation and validation capabilities will be better positioned to adapt.
Trend Three: Application-Specific Flexibility and Regional Capacity
Demand will increasingly reward flexibility and regional responsiveness over one-size-fits-all capacity. Formulators in food, dairy, and emerging plant-based segments will require systems that can handle varied materials, support cleaning and changeover, and produce consistent powder characteristics across batches. At the same time, supply chain resilience considerations will encourage capacity additions closer to end markets, particularly where regional production reduces logistics risk and improves service proximity. Commercially, this trend opens opportunities for modular designs, pilot-to-production pathways, and vendors that can deliver localized engineering and maintenance support. The principal risk is that excessive customization can raise cost and complexity; the winning approach will balance flexibility with standardized core architectures that keep qualification and maintenance manageable.
Strategic Actions for Decision Makers
For Manufacturers and Equipment Vendors
Invest in efficiency and compliance as core product attributes. Differentiation based solely on capacity or baseline features is increasingly insufficient; instead, develop demonstrable advantages in energy performance, particle control, automation, and validation support. Build service-led revenue streams that help customers sustain quality and efficiency over the lifecycle of the equipment, because recurring support relationships often determine long-term share more than the initial sale. Where regional demand is expanding, consider localized engineering and spare parts capabilities that reduce lead times and improve customer confidence, while retaining a standardized core platform to control cost and qualification complexity.
For Investors and Strategic Allocators
Focus on the segments and business models where regulatory and efficiency tailwinds concentrate value. Pharmaceutical and high-value food applications offer stronger pricing power for equipment and services that reduce variability and accelerate qualification, while volume-driven food and dairy segments reward efficiency improvements and lifecycle support. Evaluate companies not only by headline revenue but by their ability to win and retain complex accounts, support compliance, and convert installed bases into upgrades and service contracts. Monitor the pace of regulatory alignment and energy economics, as both will influence project timing, procurement criteria, and the relative attractiveness of technology-led versus price-led competition.
For Procurement and Operations Leaders
Extend the evaluation framework beyond purchase price to total lifecycle economics and risk. Include energy consumption, cleaning and sanitation burden, qualification and documentation requirements, spare parts availability, and service responsiveness in the decision process. Where compliance intensity is high, prioritize vendors that can provide structured validation support and predictable operating performance, because the cost of rework, downtime, or audit findings can outweigh marginal hardware savings. Consider phased adoption paths that use pilot or laboratory-scale units to de-risk formulation and process choices before committing to large-scale capital, especially when material sensitivity or particle quality is critical to the final product.
The spray dryer market is entering a period in which technical precision, regulatory readiness, and operating economics will determine competitive outcomes as clearly as capacity expansion ever did. The growth trajectory through 2032 is robust, but the distribution of value will favor organizations that can align equipment performance with the practical realities of energy cost, compliance, labor skill, and application flexibility. For leaders navigating capital allocation, vendor selection, or market entry, the most valuable intelligence is granular: segment-level demand shifts, technology adoption curves, regional service dynamics, and the evolving qualification burden in regulated applications. Detailed research that breaks down these dimensions by application, equipment type, and region can clarify where to commit capital, which vendors to qualify, and how to sequence investments for the next cycle of demand.
For detailed analysis of this topic, please visit the official page: Spray Dryer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


