



Conference System Market: How Wireless Shift and 7.6% CAGR Reshape Growth

The Conference System (Microphone) Market: Strategic Trends and Commercial Opportunities Through 2032
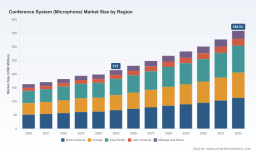
The conference system microphone market is entering a period of structural expansion, moving beyond incremental improvements in audio fidelity toward comprehensive integration of digital infrastructure, hybrid meeting capabilities, and intelligent audio processing. With total market revenue projected to grow from approximately 215.0 million USD in 2025 to 358.54 million USD by 2032, the sector is tracking a compound annual growth rate of 7.62 percent across the 2026–2032 forecast window. This trajectory reflects a fundamental shift in how organizations conceptualize meeting spaces: audio capture is no longer a peripheral accessory but a central component of collaboration infrastructure, governance workflows, and enterprise productivity ecosystems.
Historical revenue progression from 2020 through 2025 illustrates steady acceleration, with the market expanding from 163.15 million USD to 215.0 million USD. The post-pandemic normalization of hybrid work patterns, coupled with sustained capital expenditure in corporate real estate modernization and public sector digital transformation initiatives, has created a durable demand baseline. Yet the market’s growth narrative is not simply a function of volume expansion. It is increasingly defined by technology substitution, infrastructure readiness, regulatory alignment, and competitive repositioning among manufacturers that must balance performance differentiation with supply chain economics.
Market Landscape and Core Challenges
The conference microphone market operates at the intersection of professional audio engineering, networked IT infrastructure, and organizational behavior. Revenue expansion is being driven by installations that treat microphone arrays, discussion units, and ceiling-mounted capture systems as integral components of unified meeting environments. However, several structural challenges are shaping how manufacturers, integrators, and end users navigate the next phase of market development.
Infrastructure Alignment and Installation Complexity
Networked conference systems increasingly depend on robust cabling standards and centralized audio processing architectures. Ethernet infrastructure upgrades for simultaneous interpretation in large assembly spaces require Cat 6A cabling to maintain signal integrity and latency thresholds. This infrastructure dependency creates a practical bottleneck: facilities that upgrade meeting rooms often discover that audio hardware deployment cannot outpace network modernization. For manufacturers and solution providers, this means product roadmaps must account for installation environments that vary widely in readiness, from greenfield corporate campuses to retrofitted legacy government buildings.
Cost Structures and Component Sensitivity
Wireless conference microphone designs face material cost pressures that influence pricing strategy and margin management. Polymer housings and rare-earth magnets in wireless conference microphones contribute approximately 18 percent to total unit cost in 2026 supply chains. This cost composition matters because it ties product economics to commodity markets and manufacturing geography. Companies that rely heavily on wireless form factors must navigate input cost volatility while still delivering the mobility and deployment flexibility that enterprise buyers increasingly expect. The result is a market where supply chain optimization is becoming as strategically relevant as acoustic performance.
Regulatory Compliance and Procurement Pathways
Standardization and public procurement dynamics are shaping market access. Digital infrared conference systems must comply with IEC 60914 for electromagnetic compatibility and safety in public meeting spaces. At the same time, conference microphone systems in government facilities are eligible for public procurement funding under digital government modernization programs. These two forces create a dual dynamic: compliance requirements raise the barrier for entrants that cannot meet certification expectations, while modernization funding expands the addressable base in public sector settings. Manufacturers that align product certification and procurement positioning with these frameworks gain a structural advantage in segments where purchasing decisions are less price-sensitive and more specification-driven.
Key Demand Drivers
The market’s expansion is being propelled by a combination of technological, regulatory, behavioral, and supply-side developments. Each driver reinforces the others, creating a landscape where audio capture is becoming more networked, more automated, and more tightly integrated with broader collaboration workflows.
Technology Innovation and Intelligent Audio Processing
One of the most significant shifts is the move from standalone microphone hardware toward integrated audio processing chains. Ceiling and table array microphones, wireless discussion systems, and all-in-one audio bars are increasingly paired with digital signal processing that handles noise suppression, beamforming, automatic mixing, and speaker tracking. This evolution reduces the burden on end users to tune audio environments manually and supports consistent capture quality across varied room configurations. The practical implication is that manufacturers are competing not only on microphone sensitivity or form factor, but on the intelligence embedded in the acoustic pipeline. Companies that can deliver predictable audio performance across hybrid and in-room scenarios are gaining traction with IT and facilities teams that need to manage many meeting spaces without specialized audio engineering support.
Hybrid Meeting Behavior and Coverage Demand
Hybrid meeting adoption has increased demand for wireless conference microphone coverage by 45 percent in enterprise environments since 2024. This behavioral shift reflects a durable change in how organizations operate: meetings are no longer confined to a single room with all participants present. Instead, distributed participation has become routine, and audio capture must serve both in-room clarity and remote intelligibility. Wireless coverage expansion is not simply about adding more devices; it is about ensuring that discussion systems can accommodate mobile participants, flexible seating arrangements, and multi-site integration. For solution providers, this means product portfolios must support rapid redeployment, simplified pairing, and seamless integration with video and collaboration platforms. The enterprise buyer is increasingly evaluating microphones not as isolated audio tools, but as components of a broader hybrid collaboration architecture.
Public Sector Modernization and Formal Gathering Requirements
Government facilities, legislative bodies, and large institutional meeting spaces continue to represent a meaningful demand base for formal conference systems. Digital wired and wireless conference systems, paperless solutions, and hybrid meeting technologies for formal gatherings are particularly relevant where voting, simultaneous interpretation, and recorded proceedings are part of the operational workflow. Public procurement funding tied to digital government modernization programs further supports adoption in these environments. At the same time, compliance expectations around electromagnetic compatibility and safety reinforce the importance of certified, proven systems. This segment rewards manufacturers that can offer durable, specification-aligned solutions with clear support for formal meeting processes rather than purely casual collaboration use cases.
Supply Chain and Cost Architecture Realignment
Beyond component cost sensitivity, the broader supply chain environment is influencing product strategy. Manufacturers are reassessing how much functionality is integrated into a single device versus distributed across networked endpoints. Ethernet-based networked conference systems introduce different cost and deployment considerations compared with standalone infrared or wired discussion units. Meanwhile, raw material exposure in wireless designs encourages engineering teams to explore material efficiency, modular architecture, and manufacturing footprints that can better absorb input cost fluctuations. The practical outcome is a market in which product differentiation is increasingly tied to total cost of deployment rather than unit price alone. Buyers are weighing installation labor, cabling requirements, management overhead, and long-term maintainability alongside acoustic specifications.
Competitive Positioning and Strategic Evolution
The competitive landscape is shaped by manufacturers that have built reputations across professional audio, conference systems, and integrated meeting solutions. The market remains moderately fragmented, with concentration levels indicating room for both specialization and consolidation. This environment rewards companies that can combine product reliability, deployment practicality, and clear alignment with the use cases their customers prioritize.
Differentiation Through Integrated System Design
Several established players have emphasized end-to-end discussion and audio processing ecosystems rather than isolated microphone products. For example, some manufacturers focus on ceiling and table array microphones paired with advanced audio processing for hybrid conference rooms, creating a compelling value proposition for organizations that want consistent capture without complex tuning. Others prioritize digital wired and wireless conference systems with main units and multimedia devices designed for structured meetings, which appeals to customers with formal deliberation, voting, or interpretation requirements. There are also vendors emphasizing all-in-one meeting audio solutions and ceiling microphone arrays that simplify installation in modern collaboration spaces. These approaches illustrate a broader competitive theme: differentiation is increasingly defined by how well a product portfolio addresses the full meeting workflow, from audio capture to processing to integration with room systems.
Worldwide Pro Microphone Market
Regional and Segmental Specialization
Competitive positioning also varies by market orientation. Some manufacturers have strong presence in enterprise collaboration environments where wireless flexibility and hybrid coverage are priorities. Others have built credibility in formal government and institutional settings where wired and infrared systems, certification compliance, and paperless meeting capabilities are central. Asian manufacturers, in particular, have expanded digital conference system offerings with wireless and paperless multimedia solutions, reflecting both scaling capacity and growing emphasis on feature parity with established Western brands. This diversification means that procurement teams often evaluate suppliers not just by brand familiarity, but by how well a vendor’s portfolio matches the operational profile of the facility and the expectations of the meeting participants.
Market Evolution Toward Consolidation and Capability Concentration
The market is likely to see continued pressure toward consolidation among companies that can combine audio hardware, DSP software, and integration support under a coherent portfolio. At the same time, specialized entrants may thrive by targeting narrow requirements such as ceiling array optimization, wireless discussion scalability, or AI-enhanced capture for specific room types. Recent trade show activity underscores this dynamic. VISSONIC exhibited a full line of digital conference systems, ceiling microphones, and paperless multimedia units at ISE 2026 in Barcelona. TAIDEN launched and showcased a fully digital conference main unit, a conference flex dock, and paperless multimedia terminals at the same event, and later presented additional conference solutions at InfoComm China 2026. These moves highlight how manufacturers are using major industry events to reinforce product breadth, demonstrate integration readiness, and signal momentum in both wired and wireless conference categories.
Forward Outlook: Trends and Commercial Implications
Looking ahead to the 2026–2032 period, the market’s trajectory will be shaped by the interaction of technology maturity, facility readiness, and purchasing behavior across enterprise, education, public sector, and large-event environments. Three trends appear especially consequential.
Trend One: From Device Sales to Managed Audio Environments
Meeting audio is increasingly treated as an environment to be managed rather than a device to be purchased. This shift favors solutions that can be centrally configured, monitored, and updated across multiple rooms. Manufacturers and integrators that offer repeatable deployment templates, remote diagnostics, and consistent processing performance will be better positioned to capture multi-site contracts. The commercial opportunity lies in building offerings that reduce operational friction for IT and facilities teams, because those teams are often the real gatekeepers in scaled rollouts.
Trend Two: Wireless Expansion Balanced by Infrastructure and Cost Realities
Wireless microphone coverage demand will continue to grow, especially in enterprise settings where hybrid participation is standard. However, growth will be moderated by cabling constraints, electromagnetic compliance expectations, and material cost exposure in wireless units. The practical implication is that product strategies will need to balance mobility with reliability and total deployment cost. Manufacturers that can offer wireless flexibility without creating hidden installation or maintenance burdens will gain a competitive edge. This is also where supply chain discipline becomes commercially visible: pricing stability, predictable lead times, and component efficiency will matter as much as feature lists.
Trend Three: Formal and Public Sector Demand as a Stabilizing Anchor
Government modernization funding, formal meeting requirements, and compliance-driven procurement will continue to provide a stable demand base. This segment values certification, durability, and workflow support such as voting, interpretation, and paperless operations. The opportunity for manufacturers is to align product certification, documentation, and support models with public procurement expectations while also offering enough flexibility to serve hybrid and multimedia needs. In practice, this means that solutions designed for formal gatherings can benefit from clear differentiation on reliability and procedural support, rather than competing solely on cost.
Risks and Uncertainties
Several factors could temper the market’s growth path. If enterprise real estate investment slows, meeting room upgrades may be deferred, reducing near-term procurement velocity. If wireless component costs rise further, pricing pressure could compress margins or slow adoption in cost-sensitive segments. If compliance or infrastructure requirements become more stringent without corresponding procurement support, installation timelines could lengthen, particularly in large halls and public facilities. Finally, if hybrid meeting practices stabilize into a narrower set of use cases, the demand surge for expanded wireless coverage could moderate. These uncertainties do not negate growth, but they suggest that forecast confidence will depend on how well manufacturers and buyers manage deployment complexity and total cost.
Strategic Guidance for Decision Makers
The market’s expansion creates distinct implications depending on a decision maker’s role. While the following recommendations are general in nature, they highlight where attention is likely to yield the greatest strategic value.
PW Consulting
For Manufacturers and Solution Providers
- Align product roadmaps with total deployment cost, not just unit performance. Ethernet readiness, cabling requirements, and installation labor increasingly shape purchasing decisions, so designs that simplify integration can win even when acoustic specifications are comparable.
- Invest in intelligent audio processing and repeatable room templates. Consistent capture across varied environments reduces the operational burden on end users and strengthens multi-site sales opportunities.
- Manage supply chain exposure in wireless product lines. Given the material cost contribution of polymer housings and rare-earth magnets, manufacturers should evaluate component efficiency, sourcing resilience, and pricing strategies that protect margin without sacrificing mobility features.
For Investors and Corporate Strategists
- Focus on companies that can combine hardware, processing, and integration support into coherent offerings. The market appears to reward portfolios that reduce complexity for buyers rather than those that compete on narrow hardware specs alone.
- Watch public sector modernization and compliance-aligned product positioning as indicators of durable demand. Certification readiness and procurement alignment can create stickier relationships in government and institutional segments.
- Monitor competitive moves around wireless coverage, ceiling array solutions, and paperless meeting capabilities, since these areas reflect where manufacturers are placing bets on future meeting behavior.
For Procurement and Facilities Leaders
- Evaluate conference microphone systems as part of the broader room infrastructure, including network cabling, interpretation requirements, and ongoing management. Total cost and deployment feasibility often matter more than headline device features.
- Prioritize compliance and certification where formal meetings, public spaces, or large halls are involved. Aligning procurement with recognized standards can reduce project risk and support smoother approval processes.
- Consider hybrid meeting behavior explicitly when specifying wireless coverage. Deployment plans should account for flexible seating, multi-site participation, and the practicalities of redeploying devices across spaces.
Closing Perspective
The conference system microphone market is expanding against a backdrop of hybrid work normalization, digital infrastructure upgrades, and growing expectations for consistent audio capture across meeting environments. Growth through 2032 will be shaped not only by demand volume, but by how effectively manufacturers, integrators, and buyers navigate infrastructure dependencies, cost structures, compliance requirements, and the shift toward managed audio environments. Strategic advantage will increasingly belong to those who treat conference microphones as part of an integrated collaboration architecture rather than as isolated components.
Worldwide Audio Conference System Market
For decision makers seeking deeper segmentation detail, company-level comparisons, and customized scenario planning, the full PW Consulting research report provides more granular data and targeted recommendations across region, type, and application dimensions.
For detailed analysis of this topic, please visit the official page: Conference System (Microphone) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


