



Magnetic Bead Purification Kits Market: Why 6.6% CAGR Reshapes the DNA/RNA Landscape

Strategic Trends and Commercial Opportunities in the Magnetic Bead Purification Kits Market
The magnetic bead purification kits market has evolved from a niche laboratory tool into a critical component of modern molecular diagnostics, pharmaceutical development, and genomic research. At its core, the market enables the isolation of nucleic acids and proteins with greater reproducibility, scalability, and compatibility with automation than traditional column-based methods. This shift is not merely technical; it reflects a broader transformation in how biological samples are processed across clinical, industrial, and academic settings. For decision-makers evaluating long-term positioning in life sciences reagents and consumables, understanding the trajectory of this market requires looking beyond product specifications to the structural forces shaping demand, competition, and innovation cycles.
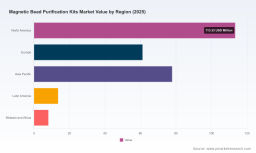
The global market for magnetic bead purification kits reached an estimated revenue base of 274.0 million in 2025, expanding from approximately 200.0 million in 2020. Growth over this period reflects sustained adoption across research and clinical workflows, with the market projected to advance at a compound annual growth rate of 6.6 percent through 2032, reaching roughly 426.49 million. The expansion is not evenly distributed across product types or end-use segments, but the overall trajectory signals a maturing market where differentiation, regulatory readiness, and workflow integration increasingly determine competitive advantage. Revenue concentration remains notable, with the top three players capturing around half of total market value and the top five holding approximately two-thirds, indicating that scale, brand trust, and established distribution channels still confer meaningful advantages. At the same time, the presence of specialized and regionally strong suppliers suggests that targeted product strategies and application-specific solutions continue to carve out defensible positions.
PW Consulting
Several structural challenges and inflection points define the current environment. First, the market is navigating a transition from broadly applicable research kits toward application-specific, regulatory-compliant solutions for clinical diagnostics and high-throughput testing. Kits that perform reliably in a research laboratory do not automatically meet the reproducibility, traceability, and clearance requirements demanded in molecular diagnostic workflows. This creates a divide between suppliers that have invested in validation, documentation, and regulatory pathways and those that remain primarily focused on research-grade offerings. Second, supply chain sensitivity around high-purity magnetic beads and specialized buffers has become a practical constraint. The performance of purification kits depends heavily on bead chemistry, surface functionalization, and buffer composition, meaning that shortages, quality inconsistencies, or cost volatility in critical inputs can disrupt both product development and customer trust. Third, the rising importance of automated platforms is reshaping purchasing logic. Laboratories and clinical operations increasingly view purification kits not as standalone consumables but as part of integrated workflows that include instrumentation, software, and throughput requirements. Suppliers that cannot align their kits with automated systems risk being bypassed in favor of more compatible solutions, even if their chemistry is competitive on a standalone basis.
The market’s expansion is being propelled by a combination of technological, regulatory, and demand-side forces that reinforce one another. Technological innovation remains the most visible driver. Magnetic bead chemistry continues to advance in ways that directly affect throughput, purity, and applicability to demanding downstream applications. High-molecular-weight DNA extraction, viral nucleic acid purification, and circulating free DNA isolation are examples where bead design and buffer systems determine whether a kit can support long-read sequencing, sensitive diagnostics, or reproducible biomarker workflows. Recent product introductions illustrate this trajectory. The launch of magnetic bead kits optimized for high-molecular-weight DNA extraction and automated workflows reflects a clear alignment between chemistry and the needs of long-read sequencing platforms, where fragment integrity and consistent yield are essential. Similarly, magnetic bead solutions designed for high-throughput viral nucleic acid purification from saliva, respiratory swabs, and wastewater demonstrate how purification kits are increasingly tailored to sample types and testing scenarios rather than generic isolation tasks. These developments matter commercially because they expand the addressable use cases for magnetic bead kits beyond conventional research workflows and into settings where performance specifications are tightly linked to downstream value.
Regulatory and policy environments are shaping the market with increasing force. For clinical applications, magnetic bead-based kits intended for viral and circulating free DNA purification increasingly require in vitro diagnostic clearance, CE marking, or regulatory submissions that document performance and safety. This does not simply add compliance costs; it changes the market’s structure by raising barriers for new entrants and rewarding established suppliers with regulatory experience, quality systems, and validated manufacturing processes. At the same time, regulatory expectations are also influencing product design in subtler ways. Features such as thermal stability, compatibility with sterilization procedures, and consistent lot-to-lot performance are becoming more important as laboratories seek to reduce contamination risk and maintain dependable results across high-volume workflows. Supplier claims around easy autoclave sterilization and thermal stability, for example, are not just technical specifications; they address operational concerns that matter in regulated or high-throughput environments. The practical effect is that regulatory dynamics are pushing the market toward more standardized, validated, and workflow-ready solutions, which favors companies that can provide both the chemistry and the evidentiary support needed for clinical adoption.
Demand-side behavior is also changing the market’s direction. Molecular diagnostics and infectious disease testing continue to drive usage of nucleic acid extraction workflows across clinical laboratories, creating steady demand for purification kits that can be deployed in routine testing and surge scenarios alike. This is not solely a function of outbreak response; it reflects the broader integration of molecular testing into standard diagnostic pathways. Academic and research institutions remain significant users, but the nature of demand is shifting as laboratories prioritize reproducibility, scalability, and compatibility with automated processing. Pharmaceutical and biotechnology companies increasingly rely on purification kits as part of complex development workflows, where consistency and documentation can influence decision-making from early discovery through clinical-stage work. The commercial implication is that demand is becoming more segmented by performance requirements and less driven by price alone. Buyers in diagnostic and industrial settings are often willing to accept premium pricing if a kit reduces variability, integrates with existing instruments, or supports regulatory documentation, while research buyers may remain more price-sensitive but increasingly value workflow efficiency and technical support.
Cost and supply chain structures are influencing competitive positioning in ways that merit close attention. Magnetic bead purification kits depend on specialized raw materials and precise manufacturing controls, which means that material costs, quality assurance, and supply resilience all affect margin stability and customer reliability. High-purity beads and purpose-built buffers are essential for consistent performance in applications such as viral RNA and circulating free DNA isolation, so any disruption in sourcing or production can have outsized consequences. Over time, this dynamic encourages consolidation among suppliers that can secure reliable input streams, standardize manufacturing, and invest in quality systems. It also creates opportunities for companies that can differentiate through manufacturing efficiency, regional supply agility, or kit designs that reduce waste and handling complexity. The broader point is that the market is increasingly rewarding operational excellence as much as product innovation, because performance claims are only valuable if they can be delivered consistently at scale.
The competitive landscape is characterized by a mix of large, diversified life sciences companies and specialized suppliers with strong application focus. Thermo Fisher Scientific maintains a prominent position through magnetic bead-based nucleic acid purification kits and automated extraction workflows, with product lines that emphasize compatibility with high-throughput processing and a range of sample types. Its recent emphasis on high-molecular-weight DNA kits and automated workflow optimization illustrates a strategy centered on aligning chemistry with instrumentation and downstream applications. Qiagen contributes a broad portfolio of magnetic bead kits for nucleic acid and protein purification, including solutions for viral RNA and circulating free DNA isolation. Its positioning reflects deep experience in sample preparation and a focus on validated workflows that can bridge research and diagnostic use. New England Biolabs has strengthened its presence through magnetic bead-based kits designed for high-throughput viral nucleic acid purification, a move that highlights the importance of sample-type specificity and workflow throughput in contemporary product strategy.
Worldwide AAV Purification Kit Market
PerkinElmer’s acquisition of Covaris illustrates a broader consolidation trend in which companies expand their capabilities by combining chemistry, instrumentation, and sample preparation technologies. The integration of magnetic bead-based extraction kits with automated platforms creates a more complete value proposition for customers seeking streamlined workflows, and it signals that competitive advantage increasingly depends on how well a supplier can connect consumables with equipment and software environments. Promega and Revvity both emphasize magnetic bead-based purification across research and diagnostic workflows, with Revvity’s technology highlighting multi-sample-type compatibility and automation readiness. These strategies reflect a shared industry direction: suppliers are seeking to reduce friction for customers by offering kits that work across platforms, sample types, and throughput requirements. Smaller and regionally focused companies such as Norgen Biotek, Bioneer, TIANGEN Biotech, Zymo Research, Geneaid, Omega Bio-tek, RayBiotech, Diagenode, Magbio Genomics, and others remain important participants by serving specialized needs, regional markets, or application niches. Their continued presence suggests that the market is not simply consolidating into a few dominant players; rather, it is stratifying into broad-platform leaders and focused specialists, each competing on different dimensions of performance, support, and accessibility.
The strategic positioning of leading companies reveals several recurring advantages. Scale and brand trust help secure adoption in regulated and high-volume settings, where switching costs and validation burden favor established suppliers. Broad product portfolios and automation compatibility broaden the addressable market and create cross-selling opportunities across kits, instruments, and service offerings. At the same time, differentiated chemistry and application-specific validation allow smaller or focused companies to compete where performance requirements are exacting or where regional support and responsiveness matter. Recent industry moves support this interpretation. Product launches that target high-molecular-weight DNA extraction, viral nucleic acid purification, and compatibility with automated particle processors show how suppliers are aligning their roadmaps with the practical needs of laboratories and diagnostic operations. Acquisitions and platform integrations further suggest that the market is moving toward bundled solutions in which purification kits are evaluated as part of a larger workflow rather than as isolated reagents. The competitive trend, then, is not simply toward larger players but toward more integrated, workflow-aware offerings that reduce operational complexity for end users.
Looking ahead, the market is likely to be shaped by a few interconnected trends over the next several years. One is the continued shift toward automation-compatible, workflow-integrated kits. As laboratories and clinical operations expand high-throughput processing, suppliers that can ensure their kits work seamlessly with common magnetic particle processors and automated extraction systems will capture a growing share of demand. This trend creates commercial opportunities for companies that design kits with automation in mind from the outset, including consistent handling characteristics, compatibility with standard instrumentation, and packaging or format choices that reduce manual intervention. It also raises the stakes for suppliers whose kits are difficult to automate or require extensive protocol adjustment. A second trend is the deepening alignment between purification kits and diagnostic regulation. As molecular testing becomes more embedded in routine clinical workflows, the importance of cleared or certifiable solutions will increase. Products that can support viral and circulating free DNA purification under appropriate regulatory frameworks are likely to benefit from stronger demand in diagnostic settings, while also facing higher development and compliance costs. This trend opens opportunities for suppliers that can provide documentation, validation support, and regulatory readiness, but it also introduces uncertainty for those that rely primarily on research-grade positioning and may face pressure to adapt if clinical adoption expands faster than expected. A third trend is the growing importance of specialized applications such as high-molecular-weight DNA, viral pathogen detection, and circulating free DNA workflows. These areas are driven by sequencing technology advancement, infectious disease testing, and liquid biopsy–related research, all of which place distinct demands on purification performance. The commercial opportunity lies in designing kits that meet the specific yield, purity, and integrity requirements of these applications while also supporting scalable processing.
Magnetic Beads Market
These trends carry both opportunity and risk. The upside is clear: workflow integration, regulatory-aligned products, and application-specific chemistry can expand margins and strengthen customer loyalty in high-value segments. The risks are equally important. Overinvestment in highly specialized kits without sufficient demand depth can leave suppliers exposed if downstream applications shift. Regulatory timelines and requirements can vary across markets, complicating global launches and creating uneven growth. Supply chain fragility for critical inputs can undermine performance claims and reduce trust if quality issues arise. In addition, automation adoption is not uniform; some laboratories continue to rely on manual or semi-automated processes, meaning that the pace of transition to fully integrated workflows may vary by region, institution type, and application. Decision-makers should therefore weigh both the direction of change and the unevenness with which it will be adopted.
For manufacturers, the strategic priority is to build differentiation that survives beyond product specifications. That means aligning chemistry, workflow compatibility, and documentation so that customers can adopt kits with confidence in both research and clinical contexts. Companies should evaluate whether their portfolios are sufficiently connected to automation platforms and whether they can support customers through validation, training, and stable supply. Where specialization is pursued, it should be tied to applications with credible demand depth and clear performance requirements, rather than to incremental variations that do not change customer outcomes. For investors, the market offers interest in companies that combine defensible chemistry with strong workflow integration, regulatory readiness, and reliable manufacturing. Attention should be paid to suppliers that are expanding platform compatibility, improving margin stability through supply chain control, or positioning themselves in higher-value diagnostic and biopharmaceutical workflows. At the same time, investment theses should account for regulatory exposure, input cost sensitivity, and the possibility that automation adoption will reshape the relative attractiveness of manual versus automated kit formats. For procurement and laboratory operations, the emphasis should be on total workflow value rather than unit price alone. This includes assessing how well a kit integrates with existing instrumentation, how consistently it performs across sample types, and whether the supplier can support regulatory or quality documentation when needed. Building relationships with suppliers that can scale with throughput requirements and reduce operational variability is likely to pay off as testing and research workloads become more complex.
The commercial picture that emerges is one of steady growth underpinned by real shifts in how nucleic acid and protein purification are performed across research, clinical, and industrial settings. The market is large enough to reward scale, but it is also segmented enough to reward focus. Successful players will be those that can couple reliable chemistry with automation compatibility, regulatory alignment, and the operational resilience needed to deliver consistent results at volume. For organizations seeking to navigate this landscape with greater precision, detailed segmentation, regional dynamics, and company-specific benchmarking can sharpen strategy further. A comprehensive research report on the Magnetic Bead Purification Kits Market can provide the deeper data and customized analysis needed to translate these strategic trends into concrete decisions.
For detailed analysis of this topic, please visit the official page: Magnetic Bead Purification Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


