



Lysine Market’s 6.45% CAGR: Animal Feed Demand and Fragmented Competition

Strategic Trends and Commercial Opportunities in the Global Lysine Market: A 2032 Outlook
The global lysine market has matured from a niche amino acid segment into a critical strategic commodity underpinning animal nutrition, food fortification, and pharmaceutical applications. Between 2020 and 2025, the industry expanded its revenue base from approximately 3.35 billion USD to 4.36 billion USD, reflecting steady demand growth across traditional and emerging application channels. Forward-looking projections indicate a compound annual growth rate of 6.45 percent through 2032, with the market expected to reach 6.7 billion USD by the end of the forecast horizon. This trajectory signals a structural shift rather than a cyclical upturn, driven by demographic pressures, feed formulation optimization, and evolving regulatory frameworks that reshape trade flows and production economics.
Despite the broadly positive growth narrative, the lysine sector sits at a complex inflection point. Supply chain volatility, regulatory friction across major import markets, and persistent raw material cost pressures are redefining competitive advantages and forcing strategic recalibration among producers and downstream users alike. Understanding how these forces interact is essential for executives, investors, and procurement leaders who must navigate capacity allocation, pricing dynamics, and supplier diversification decisions over the coming years.
Market Snapshot and the Pressures Defining the Current Cycle
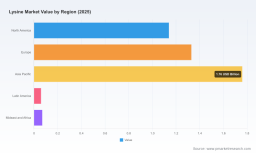
The market's expansion over the past five years has been anchored by consistent volume growth in animal feed applications, supported by rising livestock production in Asia-Pacific and Latin America, alongside steady formulation shifts in North America and Europe. The revenue progression from 2020 through 2025 reflects a compound growth path that has outpaced several adjacent agricultural input segments, underscoring lysine's entrenched role as a cost-efficiency and nutritional balance lever in feed rations.
Three structural challenges are currently shaping the operating environment. First, the market exhibits a high degree of concentration, with a small group of manufacturers commanding a dominant share of global supply. This concentration creates pricing influence and supply reliability advantages for incumbents, but it also exposes downstream buyers to concentration risk, particularly when production disruptions or trade policy shifts affect the leading facilities. Second, trade policy is introducing new friction into historically integrated supply chains. Multiple jurisdictions have escalated investigative and remedial actions targeting lysine imports from China, altering the cost and routing calculus for buyers who previously leveraged cross-border price differentials. Third, the input cost environment for fermentation-based production remains sensitive to commodity grain markets and nitrogen feedstock dynamics. Fluctuations in corn pricing and related agricultural inputs translate directly into production economics, compressing margins for producers and creating volatility for contract negotiations.
PW Consulting
Together, these forces are pushing the market from a relatively stable growth phase into a period where geopolitical, regulatory, and cost variables carry disproportionate weight in strategic planning. For decision-makers, the implication is that historical supply relationships and price assumptions require continuous revalidation rather than reliance on legacy benchmarks.
Core Drivers Shaping the Market Trajectory
Technological Innovation and Fermentation Efficiency
The lysine industry's competitive edge has increasingly depended on fermentation process optimization, strain efficiency, and scale economics. Leading producers have invested in large-capacity facilities across multiple geographies to capture cost advantages, improve throughput consistency, and reduce exposure to localized operational risk. Process improvements that increase yield per unit of feedstock, lower energy intensity, and enhance purification quality are not merely operational upgrades; they directly influence margin resilience in periods when corn and nitrogen-related inputs become more expensive.
Recent market signals reinforce the importance of cost-efficient production. Corn price levels have placed upward pressure on input costs for lysine manufacturers, highlighting how feedstock sensitivity remains a central factor in profitability. In this environment, producers with diversified feedstock strategies, integrated agricultural exposure, or access to lower-cost production basins are better positioned to absorb cost shocks without eroding competitive positioning. The broader lesson is that fermentation scale alone does not guarantee resilience; it must be paired with input management, logistics optimization, and geographic diversification to sustain advantage through commodity cycles.
Policy and Regulatory Dynamics Reshaping Trade Flows
Regulatory developments are now a defining driver of lysine market structure. The pattern of anti-dumping investigations and duty actions across major Western markets has introduced a new layer of complexity for global sourcing strategies. The European Commission's formal imposition of duties on Chinese lysine imports in the mid-2020s, alongside continuing investigative activity, signals a shift toward heightened scrutiny of pricing practices and import competition in mature markets. In parallel, U.S. trade actions affecting related agricultural inputs have created broader ripple effects across nitrogen supply chains that feed into lysine production economics.
For commercial strategies, these regulatory developments do more than alter unit costs at the border. They reorganize supplier selection criteria, encourage nearshoring and regional supply diversification, and increase the premium placed on documentation, traceability, and compliance readiness. Buyers that previously optimized primarily around spot price differentials are now weighing tariff exposure, lead-time reliability, and source-region resilience as equally important variables. Producers, in turn, are adjusting capacity deployment, export orientation, and market prioritization to align with the evolving duty landscape.
Demand-Side Shifts in Feed, Food, and Pharmaceutical Applications
Demand growth continues to be anchored most strongly by animal nutrition, where lysine remains a foundational amino acid for balancing swine and poultry diets. The scale of this application channel means that even modest formulation intensity improvements or incremental livestock production gains can translate into meaningful volume movement. This demand base has also been reinforced by ongoing efforts to improve feed conversion efficiency and reduce dependency on higher-cost protein sources, positioning lysine as a strategic formulation input rather than a simple commodity additive.
Beyond animal feed, food and dietary supplement applications as well as pharmaceutical uses represent smaller but strategically significant demand pillars. These segments often carry different margin profiles, quality requirements, and customer stickiness. In food and supplement channels, consumer interest in fortified products and protein-supportive formulations can create higher-value demand opportunities for producers able to meet specific purity and quality standards. In pharmaceutical applications, the requirements around consistency, regulatory documentation, and grade specification elevate the importance of supply reliability and technical support. As these channels mature, the ability to serve differentiated quality tiers becomes a clear source of competitive differentiation.
Supply Chain Reconfiguration and Cost Structure Evolution
The lysine supply chain is undergoing a gradual reconfiguration as companies reassess where to concentrate production relative to demand centers and trade risk. The combination of tariff exposure, commodity input volatility, and geopolitical uncertainty has encouraged a more deliberate approach to plant placement, export routing, and inventory strategy. Some producers are expanding in regions that offer feedstock proximity, logistics efficiency, and favorable market access, while others are recalibrating export plans to prioritize destinations with lower trade friction.
This restructuring also affects the cost structure beyond raw materials. Freight volatility, port and logistics bottlenecks, and the cost of maintaining compliance across multiple regulatory regimes all influence total landed cost. For large-scale producers, the ability to manage these layered costs while maintaining service levels is increasingly part of the value proposition offered to downstream customers. For buyers, the consequence is that procurement decisions must account for the full supply chain cost envelope rather than focusing narrowly on production-side pricing.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive environment in lysine remains shaped by a concentrated group of globally active producers with different geographic footprints, product portfolios, and strategic emphases. Their positioning reflects long-term investments in fermentation capacity, regional market access, and application-specific product offerings, and it continues to evolve in response to the regulatory and cost pressures described above.
Ajinomoto has built a strong global profile in amino acid production, with feed-grade lysine hydrochloride and sulfate supported by large-scale fermentation facilities in Brazil, Thailand, and the United States. Its multinational footprint provides exposure to multiple demand regions and offers a degree of supply diversification that can be advantageous in a trade-friction environment. Archer Daniels Midland is another major force in feed-grade lysine hydrochloride and acetate, with fermentation plants oriented toward high-capacity production for animal nutrition across North America and Asia. Its integration into broader agricultural and nutrition operations supports operational scale and supply chain coordination.
Evonik occupies a differentiated position through its branded Biolys offering for animal feed, with fermentation capacity in the United States and Brazil and a clear emphasis on animal nutrition applications. This branded approach and application focus can support value-based positioning where customers prioritize consistency, technical support, and specification reliability. CJ CheilJedang stands among the world's largest lysine producers, supplying feed-grade hydrochloride and sulfate through fermentation facilities in Indonesia, China, Brazil, and the United States. Its multi-region production base reflects a strategy designed to balance scale with geographic flexibility.
On the Chinese side, several producers have expanded fermentation capacity to serve poultry and swine feed markets and broader animal nutrition demand. Meihua Holdings is a leading domestic producer expanding capacity for hydrochloride and sulfate aimed at poultry and swine feed. COFCO Biochemical remains a major amino acid manufacturer with lysine sulfate and hydrochloride production focused on large-scale fermentation in China. Ningxia Eppen Biotech specializes in hydrochloride production for feed and food-grade applications, operating large-scale fermentation facilities domestically. Global Bio-Chem Technology Group produces hydrochloride and sulfate for animal nutrition and maintains fermentation operations in Asia. Collectively, these producers underscore the importance of China as both a production hub and a source of competitive pricing pressure, which in turn has contributed to the trade policy responses seen in several import markets.
ε-Polylysine Market
The strategic differentiation among these players often comes down to scale, geographic reach, product-grade capability, and the ability to manage regulatory and cost complexity. Larger multinational producers leverage diversified facilities and integrated supply chains to reduce concentration risk and serve multiple regions. Branded and application-focused suppliers seek to compete on quality assurance, formulation support, and specification consistency rather than price alone. Chinese producers with extensive fermentation capacity emphasize scale efficiency and regional demand coverage, while also navigating the consequences of heightened trade scrutiny in key export destinations.
Looking ahead, the market structure appears likely to evolve through a combination of consolidation, regional capacity rebalancing, and selective entry or expansion by producers seeking to capitalize on shifting trade routes and demand growth centers. Mature markets may see continued emphasis on supply security and compliance-ready sourcing, while growth markets may attract investment in capacity that aligns with local feed demand and import substitution objectives. New entrants will face the challenge of competing against established fermentation scale, customer relationships, and compliance infrastructure, making differentiation in grade quality, regional service, or niche application focus especially important.
L-Alanine Market
Forward View: Trends and Commercial Implications for 2026 to 2032
Trade Policy as a Structural Cost and Sourcing Variable
One of the clearest trends shaping the next several years is the entrenchment of trade policy as a structural factor in lysine sourcing and pricing. Anti-dumping investigations and duties in major import regions are not isolated events; they are part of a broader pattern that increases the importance of market-specific compliance planning. For producers, this trend creates both risk and opportunity: risk for those heavily dependent on exports to jurisdictions with active remedial measures, and opportunity for those able to redirect supply to less constrained markets or to serve demand through regionally located production.
For commercial actors, the strategic implication is that sourcing maps will increasingly be built around duty exposure, regional supply security, and documentation readiness. Companies that treat trade policy as a temporary disruption rather than a persistent variable may face repeated surprises in landed cost and supply availability. Those that proactively diversify sources, evaluate regional production options, and strengthen compliance capabilities are better positioned to stabilize procurement costs and reduce interruption risk.
Input Cost Sensitivity and the Push for Production Efficiency
The continued sensitivity of lysine production economics to corn and related agricultural inputs suggests that efficiency-driven competitiveness will remain central. Periods of elevated feedstock pricing sharpen the distinction between producers with cost-flexible operations and those with tighter input exposure. Over the forecast period, this is likely to reinforce investment in fermentation efficiency, feedstock management, and geographic placement that reduces exposure to input cost volatility.
The commercial opportunity here lies in linking production efficiency to customer value. Producers that can maintain stable pricing and reliable delivery through input cycles can build stronger long-term contracts and capture share from less resilient competitors. Buyers, in turn, can benefit from supplier partnerships that emphasize transparent cost dynamics and predictable service levels, rather than relying solely on spot-market alternatives.
Demand Diversification and Higher-Value Application Growth
While animal feed will continue to dominate volume, the medium-term growth narrative is likely to be supported by gradual expansion in food, dietary supplement, and pharmaceutical channels, especially where quality and specification requirements create higher barriers to entry. As these segments scale, they can offer differentiated margin opportunities for producers capable of meeting stricter quality demands and providing consistent documentation and technical service.
This trend also creates a segmentation opportunity. Not all lysine demand requires the same grade, certification, or service model. Suppliers that can efficiently manage multiple quality tiers and route product to the most appropriate channels may improve asset utilization and capture more value per unit than those competing strictly on commodity-grade volume. For downstream companies, selecting the right grade and supplier profile for each application becomes a lever for both cost control and performance reliability.
Potential Risks and Uncertainties
The outlook carries several uncertainties that merit careful monitoring. Continued trade policy escalation could further restrict market access or redirect trade flows in ways that alter regional price relationships. Feedstock and freight volatility can compress margins and complicate contract stability. Concentration in supply means that operational disruptions at major facilities can have outsized effects on regional availability and pricing. In addition, demand growth may not always track linearly with livestock production if formulation trends shift, alternative amino acid strategies gain traction, or economic conditions affect meat consumption patterns in key markets.
These risks do not negate the market's growth potential, but they reinforce the need for scenario-aware planning. Companies that build flexibility into sourcing, capacity expectations, and contract structures will be better positioned to manage disruption without losing strategic momentum.
Decision-Maker Action Priorities
For lysine manufacturers and producers, the priority is to strengthen resilience across the full value chain rather than focusing solely on fermentation capacity. That means evaluating feedstock exposure, logistics corridors, and market-specific regulatory risk in parallel with scale expansion. Companies should also consider how product-grade differentiation and application-specific service can support more defensible positioning in a concentrated market. Where export strategies depend on access to jurisdictions with active trade measures, scenario planning around redirection, regional partnerships, and compliance readiness becomes especially important.
For investors, the key is to assess which producers have durable advantages in cost structure, geographic diversification, and ability to navigate trade complexity. Scale alone is insufficient if it comes with concentrated input risk or heavy exposure to duties and border measures in major export markets. Investment theses should weigh the stability of demand channels, the credibility of compliance and documentation capabilities, and the flexibility of production footprints. Companies that can demonstrate consistent execution through input cycles and regulatory shifts are more likely to sustain value creation through the forecast period.
For procurement leaders and downstream buyers, the strategic task is to move beyond single-dimension price optimization. Diversifying approved suppliers, evaluating total landed cost including trade and compliance variables, and aligning grade selection with actual application requirements can reduce exposure to supply interruptions and unexpected cost swings. Building longer-term relationships with suppliers that offer transparent cost dynamics and reliable service can also improve planning stability. Where operations span multiple regions, regional sourcing strategies and inventory buffers should be calibrated to the specific trade and logistics risk profile of each market.
Executing these priorities effectively requires continuous access to detailed market data, supplier-level intelligence, and region-specific trade and cost analysis. The broader lysine market story is clear in its direction, but the actionable specifics—segment-level dynamics, pricing structures, demand shifts by application, and the implications of evolving trade measures—are where strategy becomes executable. Decision-makers who supplement high-level market awareness with deeper, current intelligence are better equipped to time investments, negotiate contracts, and adapt sourcing strategies as conditions change. A comprehensive research report can provide that layer of detail, offering the segmentation depth and customized context needed to translate market trends into concrete commercial decisions.
For detailed analysis of this topic, please visit the official page: Lysine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


