



Nitrogen Gas Springs Market: Why the 5.7% CAGR and 657M Outlook Redefine Strategy

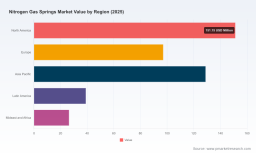
The Nitrogen Gas Springs Market: Strategic Shifts and Commercial Opportunities Through 2032
The nitrogen gas springs market has entered a phase of steady, structurally driven expansion. Valued at approximately 442.3 million USD in 2025, the market is projected to reach 657.3 million USD by 2032, reflecting a compound annual growth rate of 5.7 percent. This trajectory does not represent a cyclical rebound but rather a fundamental realignment of how downstream industries consume, specify, and integrate gas spring technologies. The historical volatility of the early 2020s has given way to a more predictable upward slope, yet the pace and composition of growth are being reshaped by digitalization, regulatory standardization, and shifting end-use demand profiles. For executives and investors navigating this space, the central question is no longer whether the market will expand, but how value will be captured across different segments, geographies, and technology tiers.
At the operational level, nitrogen gas springs have transitioned from commoditized tooling components to integrated elements within broader manufacturing and assembly ecosystems. Their role in metal stamping, injection molding, die making, and industrial machinery has been steadily reinforced by pressures for faster cycle times, higher precision, and safer tool handling. The market structure reflects this maturation, with a moderate concentration that leaves room for differentiated positioning. The top three players account for roughly 38 percent of revenue, while the top five collectively represent about 48 percent. This distribution indicates a landscape where scale matters, but technical specialization, regional proximity, and application-specific engineering remain decisive competitive levers.
Market Landscape and Core Challenges
The current market environment is defined by a tension between steady demand growth and structural friction points that constrain margin expansion and operational predictability. Three challenges stand out as particularly consequential for manufacturers, distributors, and downstream buyers.
First, the standardization framework is simultaneously a stabilizer and a constraint. Global specifications such as ISO 11901 govern dimensions, force ratings, and safety instructions for press tools and dies, while European deployments must align with PED 2014/68/EU compliance requirements. Additional mounting and interchangeability conventions, including VDI 3003 and CNOMO standards, further shape procurement and engineering workflows. These frameworks reduce integration risk and accelerate design cycles, but they also compress differentiation opportunities for suppliers that rely solely on mechanical performance. Companies that cannot embed compliance into their design and documentation processes face increasing friction in multi-region sourcing, while buyers must navigate a landscape where interchangeability is expected but not uniformly achieved across vendors.
Second, input cost volatility continues to pressure production economics. Steel prices fluctuate in response to supply chain disruptions, geopolitical tensions, and shifting demand patterns, and these movements translate directly into manufacturing cost variability for gas springs. Because many components rely on precision steel geometries, valve assemblies, and sealing systems, manufacturers operate in an environment where raw material exposure must be managed through hedging, supplier diversification, or engineered redesigns. The challenge is not simply higher prices, but the unpredictability that complicates long-term pricing commitments, inventory planning, and margin forecasting.
Third, the market is experiencing a functional shift from passive component supply to active performance monitoring and lifecycle management. Industry 4.0 initiatives in die tooling and stamping operations are driving interest in pressure and temperature telemetry, condition tracking, and predictive maintenance signals. This shift creates a transition cost for incumbents that lack digital integration capabilities, while also raising the bar for downstream adoption. Buyers increasingly expect components that can be monitored, serviced, and replaced with minimal downtime, which means the value proposition is expanding beyond force delivery to include reliability data, serviceability, and integration readiness.
Together, these challenges point to a market in which compliance, cost resilience, and digital capability are becoming baseline expectations rather than optional enhancements. Suppliers that treat these as separate initiatives will struggle to keep pace; those that integrate them into product architecture and commercial models will be better positioned to defend margins and capture share.
Key Drivers Reshaping the Market
The expansion path of the nitrogen gas springs market is being propelled by overlapping forces that influence both supply-side capabilities and demand-side behavior. Four drivers are particularly relevant for strategic planning.
Technological innovation and miniaturization pathways are expanding the functional envelope of gas springs. Standard nitrogen gas springs remain the volume backbone of the market, but compact, super compact, and micro variants are gaining relevance in applications where space constraints, weight sensitivity, and higher precision are critical. This is not merely a sizing trend; it reflects broader engineering demands in automotive tooling, aerospace assemblies, and advanced industrial machinery, where component packaging and force consistency must be optimized simultaneously. Manufacturers that can deliver reliable performance at smaller footprints, while maintaining safety and interchangeability, are able to enter design cycles earlier and secure specification preference.
Regulatory and standards-driven adoption is reinforcing demand in established industrial regions while also shaping entry barriers. Compliance with ISO 11901-5:2021, which specifies that only nitrogen in commercial-grade purity class 5.0 should be used to charge gas springs for stamping dies, provides a clear technical baseline and reduces ambiguity in procurement. PED 2014/68/EU requirements add another layer of assurance for European machinery and tooling applications. For suppliers, these standards create a credible quality narrative and reduce the risk of non-conforming installations. For buyers, they simplify specification and reduce integration risk. The net effect is a market where conformance becomes a competitive asset, particularly in sectors where safety, repeatability, and auditability are non-negotiable.
Demand-side shifts in automotive and aerospace tooling are reshaping application priorities. Automotive remains the largest application segment, reflecting the continued intensity of stamping, forming, and mold-based production across vehicle platforms. Aerospace continues to contribute a meaningful share of demand, driven by precision components, stricter performance tolerances, and higher lifecycle expectations. These sectors are not simply buying more gas springs; they are specifying them with greater attention to contamination resistance, slow-return behavior, high-temperature capability, and long-term reliability. As vehicle architectures evolve and aerospace programs demand more consistent tooling performance, gas springs are increasingly evaluated as part of a broader system-level reliability strategy rather than as isolated consumables.
Air Springs Market
Supply chain reconfiguration and cost structure adaptation are altering how manufacturers compete on availability, lead time, and total cost of ownership. In a market where steel price volatility and logistics uncertainty can erode planned margins, suppliers are responding with tighter inventory models, regional warehousing, and broader standard catalogs that enable faster fulfillment. The ability to offer steel and stainless steel variants, standardized mounting dimensions, and interchangeable designs is becoming a practical differentiator for procurement teams seeking to reduce downtime and simplify spare-part management. At the same time, manufacturers are re-examining BOM sensitivity, sealing technologies, and cylinder protection features to reduce vulnerability to contamination and premature wear, which lowers total maintenance burden over the life of the tool.
These drivers interact in practical ways. A compact or micro spring that meets ISO dimensions and is designed for contamination-resistant operation can unlock adoption in tighter industrial layouts. A product line that pairs compliance with stainless or steel variants and rapid fulfillment can reduce procurement risk in regions exposed to input cost swings. A digitally enabled series with integrated monitoring can align gas springs with broader Industry 4.0 tooling strategies. The strategic implication is that competitive advantage is increasingly cumulative: performance, compliance, availability, and intelligence must reinforce one another.
Competitive Landscape and Leadership Strategies
The competitive field is anchored by a mix of specialized manufacturers with strong regional footprints and global reach. Several companies illustrate the strategic directions currently shaping the market.
DADCO has built a broad portfolio spanning micro to very high-force nitrogen gas springs for stamping, injection molding, and tooling, with ISO-compliant series and a strong automotive OEM supply presence. Its recent move into IoT-enabled springs with integrated pressure and temperature monitoring reflects a push toward die tooling solutions aligned with Industry 4.0. The strategic logic is clear: by combining scale, specification breadth, and telemetry, the company positions itself not only as a component supplier but also as a partner in process visibility and tool management.
Special Springs has emphasized in-house manufacturing, safety-oriented designs such as OSAS, OPAS, and SKUDO, and interchangeable replacement capability for heavy-duty industrial and stamping applications. Recent updates include the Skudo-Flex accessory to extend cylinder life, a new US Series catalog, and improved reducer options for contaminated environments. The company is also actively supporting trade exhibitions with dedicated event kits. This approach underscores a strategy centered on durability, serviceability, and market engagement, with particular attention to environments where contamination and heavy-duty cycling raise failure risk.
Gas Spring Market
Hyson Products provides a full line of nitrogen gas springs for metal stamping dies, injection molds, and custom machines, including high-force, slow-return, and contamination-resistant models. Its breadth of force and functional variants suggests a focus on application flexibility and process-specific performance, which is valuable in shops where tooling requirements vary widely across jobs and material types.
Pascal Engineering Corporation supports manufacturers with nitrogen and mini gas springs for stamping dies and injection molding, emphasizing high-quality components that contribute to safety and productivity. Its positioning is aligned with manufacturers seeking dependable, application-focused components in precision workflows.
KALLER offers high-performance nitrogen gas springs for tool and die applications, including high-temperature variants capable of operating up to 250°C for hot stamping. This capability addresses a niche but strategically important requirement in processes where thermal exposure would limit conventional components.
Bordignon, with a history dating back to 1958, is known for longevity, reliability, and innovation in stamping and forming, reinforcing a value proposition built on proven performance and incremental improvement over time.
Isotech, Gemini Gas Springs, AZOLGAS, and FIBRO each contribute distinct angles to the market. Isotech emphasizes complete gas spring lines in steel and stainless steel variants for industrial applications. Gemini focuses on in-house manufactured lift supports and dampers meeting high industrial standards. AZOLGAS provides extensive catalogs and safety-compliant designs for metal stamping and multi-technology applications. FIBRO distinguishes itself through a large standard catalog and same-day delivery from a central European warehouse, which directly addresses availability and lead-time sensitivity.
Taken together, the competitive landscape reveals several differentiation pathways. One is application breadth and force range, where suppliers aim to cover everything from micro springs to very high-force units and thereby become a default specification source across multiple tooling contexts. Another is durability and safety engineering, where cylinder protection, contamination resistance, and interchangeable designs reduce downtime and simplify maintenance. A third is digital and lifecycle integration, where monitoring and telemetry align gas springs with modern tooling and maintenance strategies. A fourth is availability and fulfillment speed, where large standard catalogs, regional warehousing, and same-day delivery reduce procurement friction for time-sensitive production environments.
The market structure suggests a moderate trend toward consolidation at the top, but also continued room for differentiation among specialized players. Larger, broadly positioned suppliers can leverage scale, multi-region presence, and digital features to capture share in standardized, high-volume applications. Specialized manufacturers can compete on heavy-duty reliability, temperature resilience, contamination handling, and custom solutions in niche or demanding contexts. New entrants face a meaningful bar because compliance, interchangeability expectations, and established supplier relationships raise switching costs. At the same time, the growing emphasis on monitoring, safety, and lifecycle service creates openings for companies that can bundle component performance with operational intelligence or service support.
Forward-Looking Trends and Commercial Implications
Looking ahead to 2032, three trends are likely to shape how the nitrogen gas springs market evolves and where commercial opportunities emerge.
Trend one: digital integration will move from pilot adoption to procurement expectation in advanced tooling environments. As stamping and molding operations pursue traceability, condition monitoring, and predictive maintenance, gas springs equipped with pressure and temperature monitoring will become more relevant in high-value tooling programs. The commercial opportunity lies not only in selling smart components, but in linking component data to tool management workflows, service scheduling, and downtime reduction. Suppliers that can demonstrate measurable reliability benefits and seamless integration with existing tooling systems are likely to secure stronger specification preference in automotive, aerospace, and advanced industrial applications. The risk is that digital features may be over-specified in contexts where basic mechanical performance and compliance already suffice, creating cost and complexity without proportional return.
Trend two: high-temperature, contamination-resistant, and compact designs will capture incremental share in demanding applications. Hot stamping, harsh environments, and space-constrained tooling layouts will continue to reward designs that balance force delivery with environmental resilience and packaging efficiency. High-temperature variants, slow-return models, and contamination-resistant configurations are positioned to benefit as manufacturers seek to extend tool life and reduce failure-driven interruptions. The commercial opportunity here is application-led differentiation: suppliers that can validate performance in specific process conditions and offer interchangeable or protective accessories can build sticky relationships with tooling engineers and maintenance teams. The uncertainty lies in how quickly these features become standard expectations versus remaining specialized upgrades, which will affect pricing power and margin trajectories.
Trend three: availability, standardization, and material-cost resilience will become central to competitive positioning. With steel price volatility and supply chain disruption remaining part of the operating environment, the ability to provide steel and stainless variants, standardized dimensions, and fast fulfillment will matter increasingly to procurement teams. Large standard catalogs, regional inventory, and interchangeability aligned with recognized mounting conventions can reduce total sourcing risk and simplify spare-part management. The commercial opportunity is to compete on total cost of ownership rather than unit price alone, especially for buyers managing multiple plants, diverse tooling portfolios, and tight production schedules. The risk is that aggressive standardization may pressure margins if not paired with volume scale, efficient logistics, or value-added services that distinguish one supplier from another.
These trends point to a market where growth is likely to be underpinned by reliability, compliance, and integration rather than by volume expansion alone. The most durable opportunities will be those that align technical features with real operational outcomes: less downtime, safer tool handling, better condition visibility, and lower lifecycle maintenance burden.
Strategic Guidance for Decision Makers
For manufacturers and suppliers, the priority is to align product architecture with the converging demands of compliance, environmental resilience, and digital readiness. Rather than treating ISO conformance, contamination handling, high-temperature capability, and monitoring as separate product lines, companies should design families that can be configured around real application conditions. This includes offering interchangeable designs, protective accessories, and material variants that reduce total maintenance exposure. Equally important is the commercial narrative: positioning gas springs as part of a tool reliability and process visibility strategy can support stronger specification lock-in, especially in automotive and aerospace tooling where downtime and consistency are closely scrutinized.
PW Consulting
For investors, the market offers exposure to a steady-growth industrial component sector, but differentiation in risk-adjusted returns will depend on which business models capture compounding value. Companies with broad catalogs, reliable fulfillment, and credible digital or lifecycle features are better positioned to defend margins in an environment of input cost volatility. Investors should also monitor the pace at which smart monitoring transitions from premium option to standard expectation, since that shift will influence both pricing dynamics and the value of existing product portfolios. Exposure to heavy-duty, high-temperature, and contamination-resistant niches may provide resilience if demand in those areas continues to outpace broader commoditization.
For procurement and engineering leaders, the strategic emphasis should be on specification criteria that reduce total cost of ownership rather than focusing narrowly on upfront price. Interchangeability, compliance documentation, contamination resistance, slow-return options, and availability all contribute to lower downtime and simpler spare-part management. Where tooling environments are complex or multi-site, standardized dimensions and recognized mounting conventions can significantly reduce integration risk. Evaluating suppliers on lifecycle performance, service support, and condition-monitoring readiness can yield more durable value than selecting on unit cost alone.
Given the pace of product updates, regulatory alignment, and application-specific innovation, decision makers benefit from access to detailed segmentation data, regional demand patterns, and company-level benchmarking that go beyond headline market size. A comprehensive research view can help translate these dynamics into segment-level priorities, identify where compliance and digital readiness are becoming table stakes, and map out which supplier profiles are best aligned with specific application portfolios. For teams preparing capacity plans, sourcing strategies, or investment theses, that level of granularity is essential for moving from market awareness to actionable execution.
For detailed analysis of this topic, please visit the official page: Nitrogen Gas Springs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


