



Embedded Non-volatile Memory Market: Why 11.54% CAGR and Automotive Demand Redefine Industry Growth

The Embedded Non-Volatile Memory Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
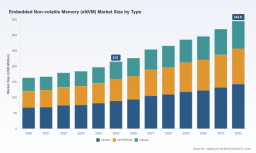
The embedded non-volatile memory market has entered a phase of sustained expansion, underpinned by a compound annual growth rate of 11.54 percent across the forecast horizon. Revenue trajectories from 2020 through 2025 reflect steady acceleration, with the market advancing from approximately 163 million units of currency to 215 million. Forward projections extend this climb, reaching roughly 226 million in 2026 and surpassing 344 million by 2032. This growth is not merely cyclical; it represents a structural realignment in how semiconductor architectures handle persistent data storage, security, and in-field programmability.
Automotive Embedded Storage (eMMC and UFS) Market
Several interconnected challenges are reshaping the competitive baseline. First, the integration of advanced eNVM variants into next-generation system-on-chip designs introduces substantial layout complexity and extended verification cycles. Embedding memory requires additional intellectual property blocks, specialized design rules, and rigorous testing protocols that lengthen development timelines and increase engineering overhead. This friction disproportionately affects fabless design teams and smaller manufacturers that lack established process integration expertise.
PW Consulting
Second, manufacturing economics remain a persistent constraint. High-cost fabrication equipment and process steps that diverge from standard CMOS pathways create integration bottlenecks. Many foundries must adapt existing lines or invest in specialized modules, which raises capital expenditure and narrows the margin window for volume products. As a result, cost-per-bit advantages can be delayed until design maturity and factory yield optimization converge.
Third, reliability and qualification requirements are intensifying across safety-critical verticals. Automotive and industrial eNVM products must satisfy stringent temperature ranges, long-term data retention targets, and grade-level certifications that validate performance under extreme operating conditions. These demands favor mature or thoroughly validated memory technologies, yet simultaneously create barriers for emerging solutions seeking rapid adoption in high-trust segments.
Key Drivers Shaping Market Dynamics
Technological innovation in memory physics and integration methodologies is accelerating the shift toward alternative eNVM types. Resistive, magnetic, and ferroelectric approaches are gaining traction where conventional flash encounters scaling limits or endurance constraints. Demonstrations of embedded ReRAM integrated into mature BCD processes for mixed-signal and high-voltage applications illustrate how non-traditional nodes can host advanced memory for power management, analog-intensive, and high-reliability designs. Similarly, MRAM and RRAM integration into FinFET and FD-SOI platforms shows that memory types once reserved for niche use cases are becoming credible candidates for mainstream microcontroller and SoC implementations.
Regulatory and certification pressures are reinforcing demand for resilient storage in mission-critical applications. Automotive and industrial programs increasingly require qualification frameworks that guarantee operation across wide temperature envelopes and sustained data integrity over extended service life. In parallel, specialized material platforms and testing protocols are gaining attention for aerospace-grade and radiation-tolerant deployments, where memory must withstand environmental stressors that conventional solutions cannot reliably tolerate. These requirements do not simply raise the compliance bar; they reshape procurement priorities and elevate the strategic value of memory suppliers with proven qualification track records.
Demand-side shifts are also redefining the addressable market. The proliferation of connected devices, edge intelligence, and vehicle electrification is expanding the installed base of microcontrollers and processors that require on-chip persistent storage for configuration, firmware updates, cryptographic keys, and calibration data. Consumers and enterprises alike are expecting systems that can be securely updated in the field and that retain essential state information across power cycles. This behavior creates recurring pull for embedded memory that balances performance, endurance, and security without relying on external storage components that add board space, cost, and failure modes.
Supply-chain and cost-structure dynamics are influencing where and how eNVM is adopted. Foundry strategies that embed MRAM and ReRAM directly into advanced and mid-range process nodes are reducing design fragmentation and enabling more efficient IP reuse across product families. At the same time, geopolitical factors continue to diversify sourcing options, with multiple foundry ecosystems offering embedded memory capabilities to global manufacturers. This broadening of supply choices can improve resilience and pricing competitiveness, but it also requires buyers to evaluate process maturity, qualification status, and long-term roadmaps rather than assuming uniformity across vendors.
Competitive Landscape and Leading Strategies
The market features a diverse mix of semiconductor manufacturers, memory specialists, and foundry platforms, each pursuing distinct value-creation strategies. Samsung Electronics continues to develop embedded STT-MRAM and flash eNVM solutions for microcontrollers, systems-on-chip, and high-performance applications, leveraging scale and process expertise to integrate memory across multiple product tiers. STMicroelectronics has focused on embedding PCM and RRAM into FD-SOI microcontrollers for automotive and industrial use cases, emphasizing platform-level integration that aligns memory choice with architecture-level efficiency. Infineon Technologies combines embedded FRAM and RRAM within automotive AURIX controllers and edge ML microprocessors, targeting applications where reliability and real-time processing intersect.
NXP Semiconductors delivers embedded MRAM in automotive microcontrollers built on advanced FinFET processes in collaboration with leading foundries, reinforcing its position in safety-critical vehicle systems. Renesas Electronics offers embedded STT-MRAM and flash for industrial and IoT microcontrollers, aligning memory selection with broad vertical coverage and long product lifecycles. Texas Instruments supplies ferroelectric and flash-based embedded memory across microcontrollers and processors, reflecting a balanced approach that spans mature and emerging technologies. Microchip Technology manufactures embedded flash and NOR eNVM for embedded systems and microcontrollers, maintaining emphasis on broad deployability and design familiarity.
On the IP and specialized memory side, Weebit Nano licenses embedded ReRAM IP for integration into foundry platforms, with recent demonstrations and qualifications spanning multiple process nodes and design environments. Everspin Technologies supplies embedded and standalone MRAM for automotive, aerospace, and industrial applications, and has expanded its high-reliability portfolio to address extended temperature and endurance requirements. TSMC embeds MRAM and ReRAM directly into advanced FinFET processes for microcontrollers and systems-on-chip, enabling designers to access memory capabilities within leading-edge node offerings. GlobalFoundries integrates embedded MRAM and ReRAM into mature and specialized platforms for high-reliability designs, providing an alternative path for applications that prioritize robustness and customization over aggressive scaling.
Leading strategies converge around three themes. The first is platform-level integration, where memory is treated as an intrinsic capability of the process and device family rather than an afterthought, reducing integration risk and enabling repeatable product derivatives. The second is qualification and reliability leadership, particularly in automotive and industrial segments where certifications and long-term retention claims are decisive procurement criteria. The third is ecosystem expansion through licensing and multi-foundry enablement, which broadens adoption by allowing design teams to deploy a consistent memory IP across different manufacturing partners and node options.
The competitive landscape is evolving through a combination of consolidation among integrated suppliers and new entry via IP licensing and specialty memory providers. Established manufacturers continue to strengthen their process roadmaps and portfolio breadth, while memory-technology specialists are expanding the set of supported nodes and design environments. This dual dynamic creates both pressure and opportunity: incumbents must defend their integration advantages and qualification portfolios, while newer entrants can gain relevance by demonstrating multi-platform compatibility, cost-effective integration, and strong technical support. Over time, the market is likely to fragment by application requirements and process node strategy rather than converge into a single dominant memory type.
Outlook for the Next Three to Five Years
One clear trend is the broadening adoption of non-flash embedded memory types in mainstream microcontroller and SoC designs. As MRAM, ReRAM, FRAM, and related technologies demonstrate improved integration maturity and cross-platform compatibility, they are expected to capture additional share in applications that demand higher endurance, lower power during write operations, or enhanced security features. The commercial opportunity lies in enabling product families that can address multiple verticals from a common architecture, reducing time-to-market and simplifying lifecycle management for manufacturers.
A second trend is the deepening of qualification-led competition in automotive and industrial segments. Requirements for wide temperature operation, long data retention, and robust reliability will continue to favor suppliers that can document consistent performance and provide transparent qualification data. This creates an opportunity for differentiated positioning through documented reliability, application-specific reference designs, and support for in-field update and secure-boot scenarios. The risk is that qualification lead times and testing costs may slow adoption of newer memory types in the highest-tier safety applications, creating a bifurcated market where mature technologies retain a multi-year advantage in the most demanding tiers.
A third trend is the increasing strategic importance of foundry and process choice. As multiple ecosystems offer embedded MRAM and ReRAM capabilities, design teams will evaluate memory integration alongside node selection, power targets, and supply resilience. This trend favors suppliers that can provide predictable integration paths, multi-node availability, and clear migration options. The uncertainty arises from the uneven pace of process optimization across foundries and the potential for cost pressures if specialized equipment or steps remain difficult to scale economically. Buyers should therefore treat memory adoption as a joint decision with process strategy rather than a standalone component selection.
Strategic Recommendations for Decision Makers
For semiconductor manufacturers and design-house leaders, the priority is to align memory selection with architecture strategy and process roadmap. Embedding eNVM early in the design cycle can reduce integration complexity later, but only if the chosen memory type has a credible path to the target node and a clear qualification trajectory for the intended applications. Companies should map memory options against product-tier requirements, plan for extended verification where necessary, and invest in reference designs that demonstrate security, endurance, and in-field update capabilities. A disciplined approach that balances emerging memory benefits with proven reliability will improve competitiveness in automotive, industrial, and connected-device markets.
For investors and strategic analysts, the value lies in tracking differentiation signals rather than headline revenue alone. Indicators such as multi-node IP enablement, qualification progress in safety-critical segments, foundry partnerships, and portfolio expansion into high-reliability products provide early insight into which players are building durable advantage. Attention should also be paid to cost dynamics and integration complexity trends, since manufacturing economics can determine whether a promising memory technology achieves volume adoption or remains confined to premium niches. Monitoring these signals helps differentiate cyclical growth from structurally advantaged positions.
Worldwide eMMC Flash Chip Market
For procurement and product-planning teams, the practical move is to evaluate embedded memory as part of a broader system strategy that includes supply resilience, certification status, and lifecycle planning. Given the range of available technologies and node options, buyers should request detailed integration specifications, qualification documentation, and roadmap alignment before committing to a memory choice for long-lifecycle programs. Detailed, segment-level intelligence is essential for comparing alternatives across applications, regions, and process technologies without relying on assumptions that may obscure important differences in cost, reliability, and availability.
Timely access to granular market data, segmentation detail, and company-specific developments can materially improve planning accuracy and reduce execution risk. Comprehensive research that covers segmentation breakdowns, regional dynamics, and recent product and partnership activity provides the context needed to translate broad market growth into specific action plans. For teams evaluating entry, expansion, or sourcing decisions, a full structured study offers the depth required to assess opportunities with greater confidence and to align technology choices with commercial objectives.
For detailed analysis of this topic, please visit the official page: Embedded Non-volatile Memory (eNVM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


