



GaN on Diamond Semiconductor Substrates Market 2026: 17% CAGR and Strategic Shifts Redefining RF Power Leadership

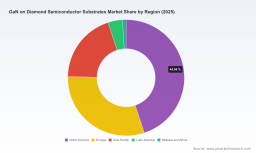
GaN on Diamond Semiconductor Substrates: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The GaN on Diamond semiconductor substrates market has entered a phase of accelerated expansion, driven by the compounding demands of high-frequency communications, defense electronics, and next-generation power systems. Measured in millions of U.S. dollars across a 2020 through 2032 horizon, the sector has moved from niche experimentation to commercial validation. Revenue grew steadily through the early 2020s as proof-of-concept devices gave way to production-grade architectures, and the pace quickened materially once supply ecosystems matured and end-users began certifying GaN-on-diamond components in operational systems. Forward projections indicate continued double-digit compound growth, with the market expected to cross the 90-dollar threshold by the early 2030s as edge deployments scale and thermal management requirements tighten across RF, microwave, and power applications.
This trajectory, however, is not uniform across value chains or geographies. The segment remains concentrated among a small group of established players who have invested early in substrate development, epitaxy compatibility, and bonding processes. Such concentration creates both momentum and friction: incumbents benefit from process know-how and early customer relationships, while the broader industry faces structural bottlenecks that complicate rapid scaling. Production of high-quality diamond wafers, particularly single-crystal variants, demands specialized chemical vapor deposition capabilities, stringent quality control, and capital-intensive cleanroom environments. Bonding GaN layers to diamond substrates without introducing defects or interfacial thermal resistance remains a disciplined engineering challenge, and yield optimization is still a differentiating factor rather than a commodity.
Three structural challenges now define the inflection point for this market. First, the thermal and electrical performance advantages of diamond substrates are well understood, but translating those advantages into repeatable, cost-effective manufacturing at volume remains uneven. Process variability, wafer-scale uniformity, and the economics of bonding and testing constrain the speed at which commercial programs can ramp. Second, demand is fragmenting across application profiles with different performance priorities. Some users prioritize maximum power density and thermal conductivity, while others require reliability at moderate performance levels with lower cost thresholds. This divergence complicates standardization and slows the emergence of common substrate specifications that could accelerate adoption. Third, supply resilience has become a strategic variable. The industry depends on a limited number of specialized synthesis and wafer processing nodes, which intensifies exposure to equipment availability, raw material readiness, and regional logistics dynamics. When those nodes face disruptions, even strong end-demand can be delayed by substrate availability rather than component design.
Taken together, the market is characterized by strong technological pull and uneven commercial readiness. The opportunity lies not only in demonstrating performance but in aligning substrate supply, bonding reliability, and application-specific design to create repeatable value chains.
Key Drivers Shaping the Market
The growth path for GaN on Diamond substrates is anchored in a combination of technical breakthroughs, regulatory momentum, demand-side evolution, and supply-side restructuring. Each driver reinforces the others, but not uniformly, and the interplay between them determines which segments scale first.
Technical innovation remains the primary catalyst. Advances in chemical vapor deposition have improved the purity, grain structure, and thermal conductivity of diamond substrates, which directly supports higher power density and lower junction temperatures in GaN devices. Alongside substrate improvements, progress in wafer bonding, interface engineering, and epi-layer compatibility has reduced the risk of performance degradation at the GaN-to-diamond interface. These advances matter because the value proposition of diamond is not just thermal conductivity in isolation; it is the ability to transport heat away from active regions under high-duty-cycle conditions without compromising RF performance or long-term reliability. Recent product launches and platform demonstrations reflect this trajectory, including new single-crystal wafers optimized for RF and power device applications, and power amplifier unveilings that emphasize reduced thermal resistance for satellite communications. The cumulative effect is closing the gap between laboratory potential and fielded hardware.
Policy and procurement dynamics are adding a second layer of support. Government programs and defense procurement pathways increasingly favor substrate and packaging technologies that extend performance envelopes in latency-sensitive, thermally constrained environments. Contracts and funding initiatives have reinforced interest in GaN-on-diamond integration for defense, radar, and hypersonic-related applications where thermal and power density requirements are explicit. This is not simply a question of subsidies; it shapes demand visibility, encourages investment in domestic capability, and signals long-term procurement preferences. In parallel, broader semiconductor support measures have influenced funding availability for satellite communications and advanced RF ecosystems, helping de-risk early-stage commercialization for companies pursuing diamond-cooling approaches. The practical impact is stronger demand forecasting and a higher tolerance for early-stage supply investment where the end-use case is strategically prioritized.
On the demand side, application behavior is changing in ways that favor higher-performance substrates. Satellite communications is expanding the need for compact, efficient RF front ends that can operate reliably under continuous load and in constrained thermal environments. Radar and millimeter-wave sensing systems increasingly require wideband performance and stable gain under temperature extremes, which makes thermal management a design driver rather than an afterthought. In commercial RF deployment, the push toward higher throughput and denser arrays also raises the thermal bar, encouraging component designs that would be difficult to sustain on conventional substrates alone. These shifts are not abstract; they translate into product roadmaps where substrate selection becomes part of system optimization, not a discrete component choice.
Single Crystal Diamond Market
Supply-side and cost dynamics complete the picture. Fabrication and bonding economics still place a premium on diamond wafer production, and the costs associated with CVD processes and bonding steps influence overall substrate pricing. At the same time, supply chain bottlenecks in diamond wafer production and high production costs constrain commercial scaling unless capacity and process maturity improve together. Regional imbalances in substrate availability have also emerged from geopolitical pressures and logistics disruption, which has prompted customers and manufacturers alike to consider diversification, near-shoring, and vertical integration strategies. These pressures are reshaping how companies plan capacity, qualification, and customer commitments. Notably, consolidation and partnership activity is increasing as firms seek to improve control over critical steps in the value chain, while consortium-based regional facilities are being advanced to support supply resilience.
Worldwide Synthetic Single Crystal Diamond Market
Competitive Landscape and Leading Strategies
The competitive field is defined by a handful of companies that have moved beyond material research into concrete product routes and targeted applications. The differences among them are less about whether GaN-on-diamond is promising and more about where each player chooses to compete: substrate supply, device integration, application focus, or vertical integration.
Element Six has built a reputation around synthetic diamond substrates and GaN-on-diamond technology for high-thermal-conductivity applications in RF, power, and defense electronics. Its strategic positioning leans on deep material expertise and controlled substrate quality, which supports customers seeking consistent performance in demanding environments. By launching ultra-high-purity single-crystal diamond wafers optimized for RF and power device applications, the company has reinforced its emphasis on material-grade differentiation as a foundation for downstream device performance.
Akash Systems has targeted satellite communications technology and related substrates, with a clear link between diamond-cooling concepts and space-grade or satellite RF performance. Securing funding tied to CHIPS Act support to advance diamond-cooling GaN-on-diamond satellite technology indicates a strategy aligned with public-sector programs and long-cycle satellite roadmaps. This positions the company where performance, thermal management, and mission-critical reliability intersect, rather than competing broadly across all RF applications.
Qorvo operates as both a components producer and an integrator in the RF and satellite space, manufacturing GaN-on-diamond transistors and power amplifiers. Its product unveiling of a GaN-on-diamond power amplifier for satellite communications that reduces thermal resistance reflects a device-level strategy: rather than selling substrate capability in isolation, it demonstrates how the substrate improves end-device performance metrics that matter directly to system designers. That route can shorten the adoption cycle because it ties substrate benefits to amplifier behavior customers can measure and specify.
RFHIC Corporation has focused on GaN-on-diamond epi wafers and technology for radar, microwave, and satellite uses. Its profile suggests a strategy oriented toward enabling partners and programs that require tailored epi and substrate combinations for high-frequency applications, including defense and satellite domains. This support-layer positioning can be strategically valuable when customers need integration flexibility or customized device structures rather than standard catalog products alone.
Coherent Corp. has moved into offering GaN-on-diamond wafers scaled for commercial RF applications, which points to a strategy centered on broader commercialization and volume orientation. Scaling for commercial RF implies a different balancing act between performance and cost compared with niche or defense-first approaches, and it suggests attention to process throughput, wafer consistency, and application breadth.
Blue Wave Semiconductor has commercialized GaN-on-diamond substrates for high-power RF and defense electronics, which places it in a space where thermal performance and power handling are central. Its commercial focus aligns with programs that need robust substrate performance under sustained high-power operation, again linking substrate choice to application risk management.
PW Consulting Information & Electronics Research Center
The landscape is evolving along several axes. Vertical integration is becoming more visible, as illustrated by an acquisition in the diamond synthesis space intended to strengthen control over upstream capability for GaN-on-diamond products. That move signals a recognition that substrate and material readiness can be a strategic bottleneck, not just a component specification. At the same time, consortium-based regional facilities are emerging to support supply chain resilience, reflecting a broader shift toward diversified capacity and regional redundancy. These developments suggest the market will likely see further consolidation where material control matters, while also encouraging new regional players or partnerships aimed at reducing dependency on limited supply nodes. Differentiation will increasingly come from application-tailored solutions, process maturity, and the ability to reduce thermal and reliability risk in real systems rather than from substrate claims alone.
Future Outlook and Strategic Opportunities
Looking ahead three to five years, the market is likely to move along a path shaped by scale, specialization, and supply-chain reorganization. The most consequential trend is the gradual shift from performance demonstration to production repeatability. As bonding yields, wafer uniformity, and qualifying standards improve, GaN-on-diamond will become less of an exceptional choice and more of a standard option in selected high-performance RF and power portfolios. That transition creates commercial opportunity for companies that can offer predictable supply, documented reliability, and design support that reduces integration risk for system manufacturers.
A second trend is the deepening linkage between substrate selection and application-specific program requirements. Defense, radar, satellite, and high-end communications will continue to push toward higher power density and thermal resilience, but they will not all value the same trade-offs. Some programs will prioritize maximum performance and tolerate complex supply or cost structures, while others will seek a balanced combination of performance, reliability, and cost. This divergence opens space for tiered offerings, application-focused qualification paths, and partnerships that align substrate supply with end-use certification timelines.
A third trend concerns supply resilience and regionalization. Given the concentration of specialized diamond wafer capability and the exposure created by logistics and geopolitical pressures, more customers and manufacturers are expected to prioritize regional availability, diversified sourcing, and tighter integration across material and device stages. Where that occurs, it creates opportunities for regional capacity initiatives, strategic partnerships, and vertically coordinated offerings that can promise steadier delivery and lower program risk.
These trends carry commercial upside, but they also include uncertainty. Yield and process consistency remain central risks, especially for single-crystal paths where scale-up is technically demanding. Cost structures may persist at elevated levels for advanced substrates, which can slow adoption in price-sensitive branches of the market. Demand timing can also diverge from supply readiness when procurement cycles, qualification requirements, or regional availability issues extend program schedules. The businesses that navigate this period most effectively will be those that treat thermal performance as a system-level advantage while building credible supply and qualification pathways around it.
Actionable Guidance for Decision-Makers
For manufacturers and device developers, the priority is to align substrate strategy with realistic production and qualification pathways rather than with performance claims alone. That means investing early in bonding reliability, thermal interface engineering, and application-specific testing that mirrors field conditions. It also means evaluating whether the target application truly requires the upper end of diamond thermal performance or whether a balanced substrate approach can meet requirements at better cost and availability. The most defensible strategies will connect device architecture, substrate selection, and supply readiness into one plan, so that performance gains do not stall at the interface between design and manufacturing.
For investors, the value lies in distinguishing between material promise and commercial readiness. Platforms with clear application anchors, credible supply strategies, and demonstrable progress in yield or integration tend to offer stronger strategic positioning than those relying on performance narrative alone. Attention should also be paid to consolidation patterns and regional capacity initiatives, since these can reshape competitive advantage by changing who controls critical nodes in the value chain. The key judgment is whether a company is building durable differentiation through process maturity and customer alignment, or whether its position depends on assumptions that have not yet been validated at scale.
For procurement and program leaders, the focus should be on supply risk, qualification timelines, and design support as much as on nominal performance. In applications where thermal limits shape system architecture, substrate availability and reliability can be as decisive as device specs. Evaluating suppliers in terms of consistency, capacity visibility, and integration assistance can reduce later schedule exposure and improve total system outcomes. Where programs span multiple regions or rely on constrained supply nodes, diversification and redundancy planning should be treated as part of the technical decision, not as a separate procurement exercise.
For decision-makers seeking a fuller picture of end-use segmentation, regional dynamics, competitive positioning, and scenario-based projections, a dedicated, detailed research view can provide the granularity needed for planning. In markets moving this quickly, detailed segmentation data and customized strategic interpretation are often what separate reactive positioning from proactive advantage.
For detailed analysis of this topic, please visit the official page: GaN on Diamond Semiconductor Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


